

First Abu Dhabi Bank: Six Analyses of Banking Business and Digital Investment

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
First Abu Dhabi Bank Strategy Analysis Bundle
First Abu Dhabi Bank is a bank in the United Arab Emirates serving personal and private banking customers. Its publicly described offering includes credit cards, Islamic banking, investment services, loans and mortgages, placing customer finance, advice, risk management and service delivery at the centre of the business model.
That breadth creates connected strategic questions rather than a single simple priority: which propositions deserve resources, how customer value is delivered, how digital and regulated banking pressures affect choices, and where internal capabilities meet external change. This bundle provides six structured lenses for examining those questions without presenting assumptions as established company findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
How should First Abu Dhabi Bank compare the resource needs of different banking propositions when market growth and relative market share may point in different directions?
The First Abu Dhabi Bank BCG Matrix helps organise portfolio discussion around market growth and relative market share, rather than treating every product as equally important. Personal lending, cards, mortgage propositions, investment services and Islamic banking can be assessed as possible portfolio areas only where suitable market and competitive evidence is available. The framework uses Stars, Cash Cows, Question Marks and Dogs as analytical categories; it does not assign FAB offerings to a quadrant without supporting data. This distinction matters in banking because investment in customer acquisition, risk capacity, technology and specialist advice can have very different payback profiles.
- Portfolio comparison. Contrast mature income-generating propositions with areas where customer demand or competitive intensity may be changing.
- Capital discipline. Consider where growth ambitions must be weighed against credit risk, operating capacity and the economics of servicing customers.
- Decision worksheet. Use the Excel framework to map evidence and assumptions, then use the detailed Word analysis to interpret portfolio trade-offs.
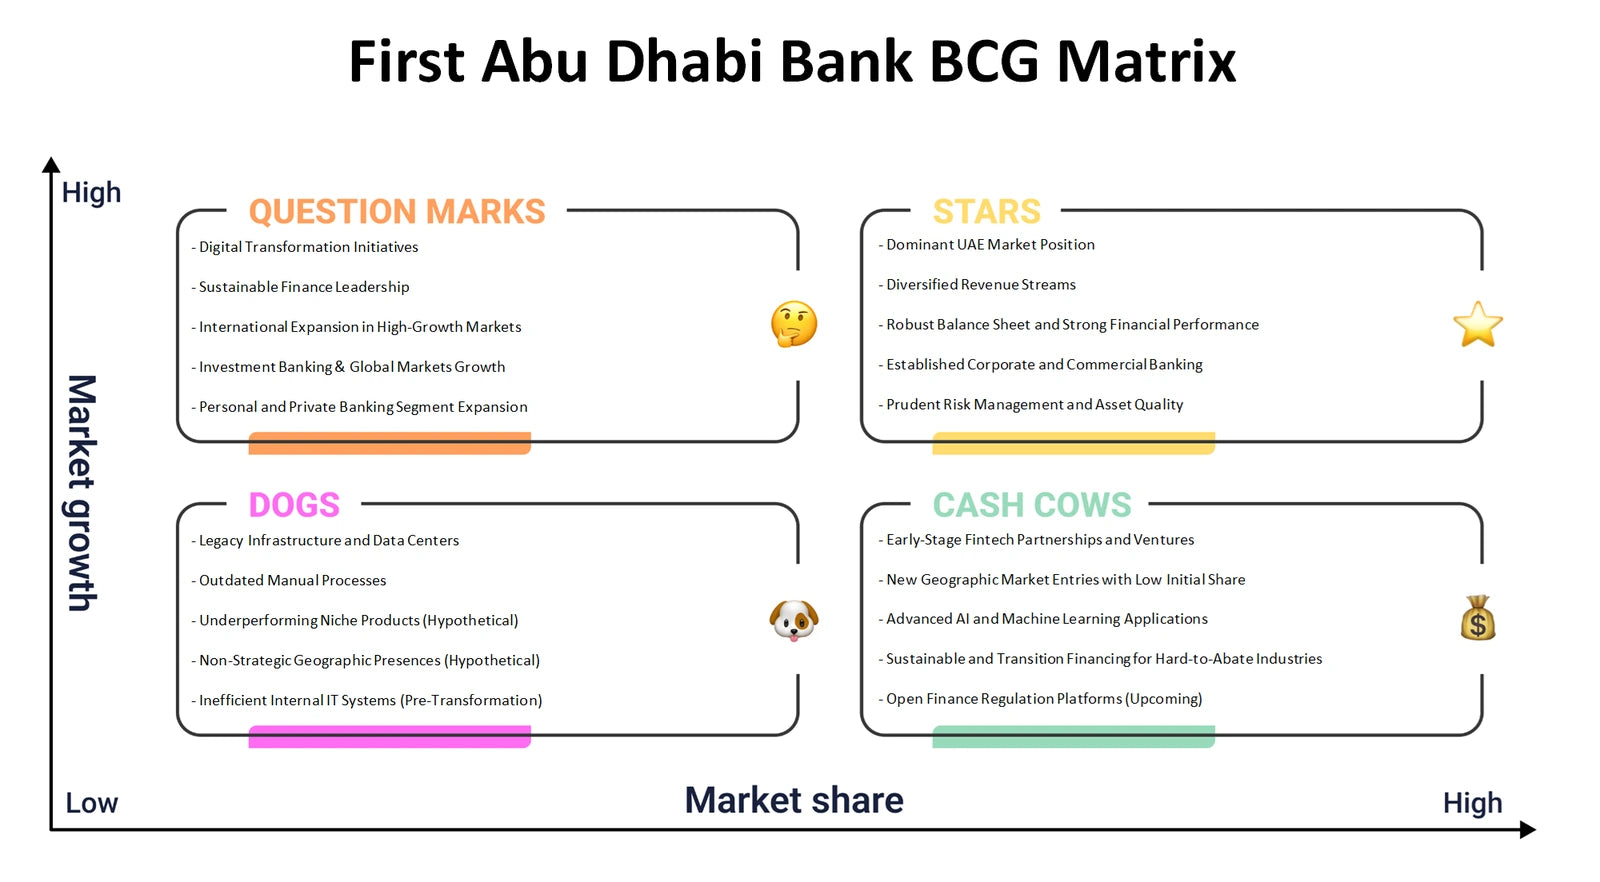
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do First Abu Dhabi Bank's customer propositions, delivery routes, risk controls and revenue logic fit together as one banking model?
The First Abu Dhabi Bank Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a UAE bank offering personal and private banking services, the useful question is not simply what is sold, but how trust, suitable products, onboarding, servicing and prudent risk decisions combine to create value. Cards, finance, investment and mortgage needs may involve different customer journeys, yet they can draw on shared capabilities such as data, compliance, credit assessment and service operations. The canvas makes those dependencies visible before conclusions are drawn.
- Customer-value fit. Examine how personal and private banking customer needs relate to financing, saving, investing and payment propositions.
- Economic connections. Link revenue streams and relationship models to the resources, activities, partners and cost commitments required to support them.
- Model narrative. Populate the Excel blocks systematically, then use the Word analysis to explore the links and tensions between the nine elements.
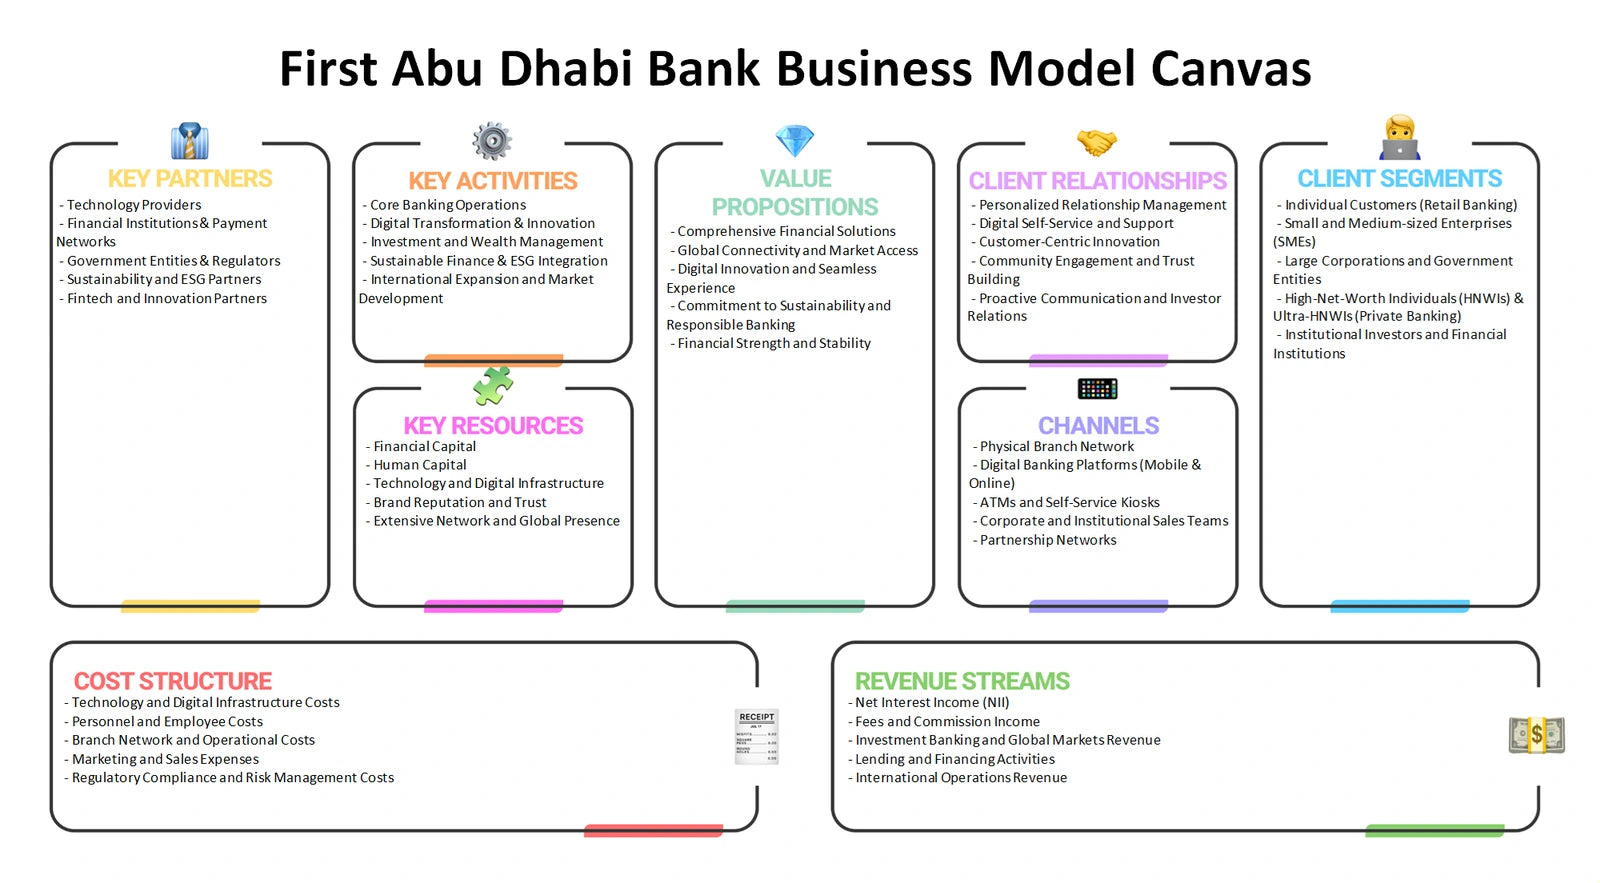
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Which industry pressures can shape the attractiveness of the UAE banking activities relevant to First Abu Dhabi Bank?
First Abu Dhabi Bank Porter's Five Forces analysis examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes in the financial sector. Banking competition is shaped by customer trust, pricing and service expectations, while regulation, capital requirements and risk infrastructure can affect entry barriers. Supplier power may include technology providers, payment infrastructure, funding sources and specialised compliance or risk talent. Buyer power concerns customers comparing service, convenience and financing terms. Substitutes are broader than direct banks: alternative payment methods, financing options or investment routes can meet similar needs. The framework avoids unsupported force scores while helping identify where pressure could influence margins and differentiation.
- Competitive pressure. Separate direct banking rivalry from substitutes that may alter how customers pay, borrow, save or invest.
- Structural barriers. Assess how trust, licensing, data security, capital and operational resilience can affect potential entrants and incumbents.
- Industry comparison. Use the Excel grid to record force-specific evidence and the Word analysis to relate each pressure to banking strategy.
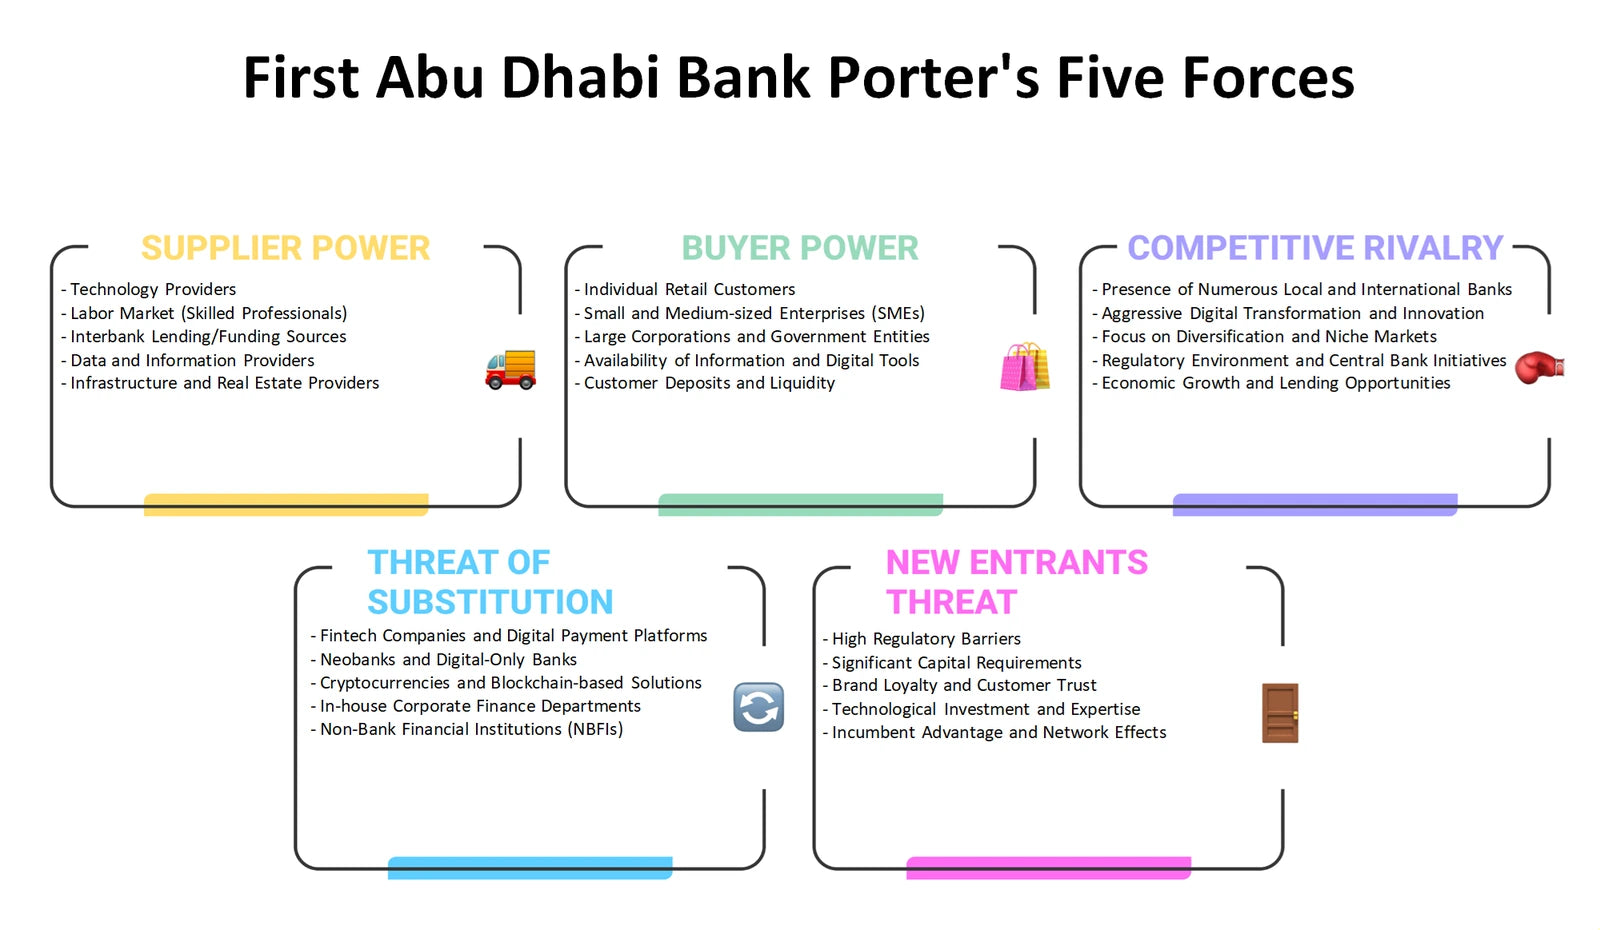
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can First Abu Dhabi Bank align its banking offers, pricing logic, customer access and communications in a regulated service environment?
The First Abu Dhabi Bank Marketing Mix considers Product, Price, Place and Promotion through the realities of financial services. Product analysis can distinguish cards, Islamic banking, investment, lending and mortgage propositions by the needs they are designed to address. Price is not limited to a headline rate: it may involve fees, risk-based terms, profitability requirements and, for relevant offerings, Islamic finance structures. Place asks how customers access information, apply, transact and receive ongoing support through suitable digital and service routes. Promotion must communicate clearly and responsibly because financial decisions depend on confidence, eligibility and understanding, not impulse alone.
- Offer architecture. Compare how product features and service support may vary across borrowing, payments, wealth and property-finance needs.
- Route-to-customer. Examine the balance between digital journeys, relationship-led support and other customer contact points without assuming channel shares.
- 4P planning. Use the Excel framework to test product-price-place-promotion consistency, supported by the detailed Word discussion of banking trade-offs.
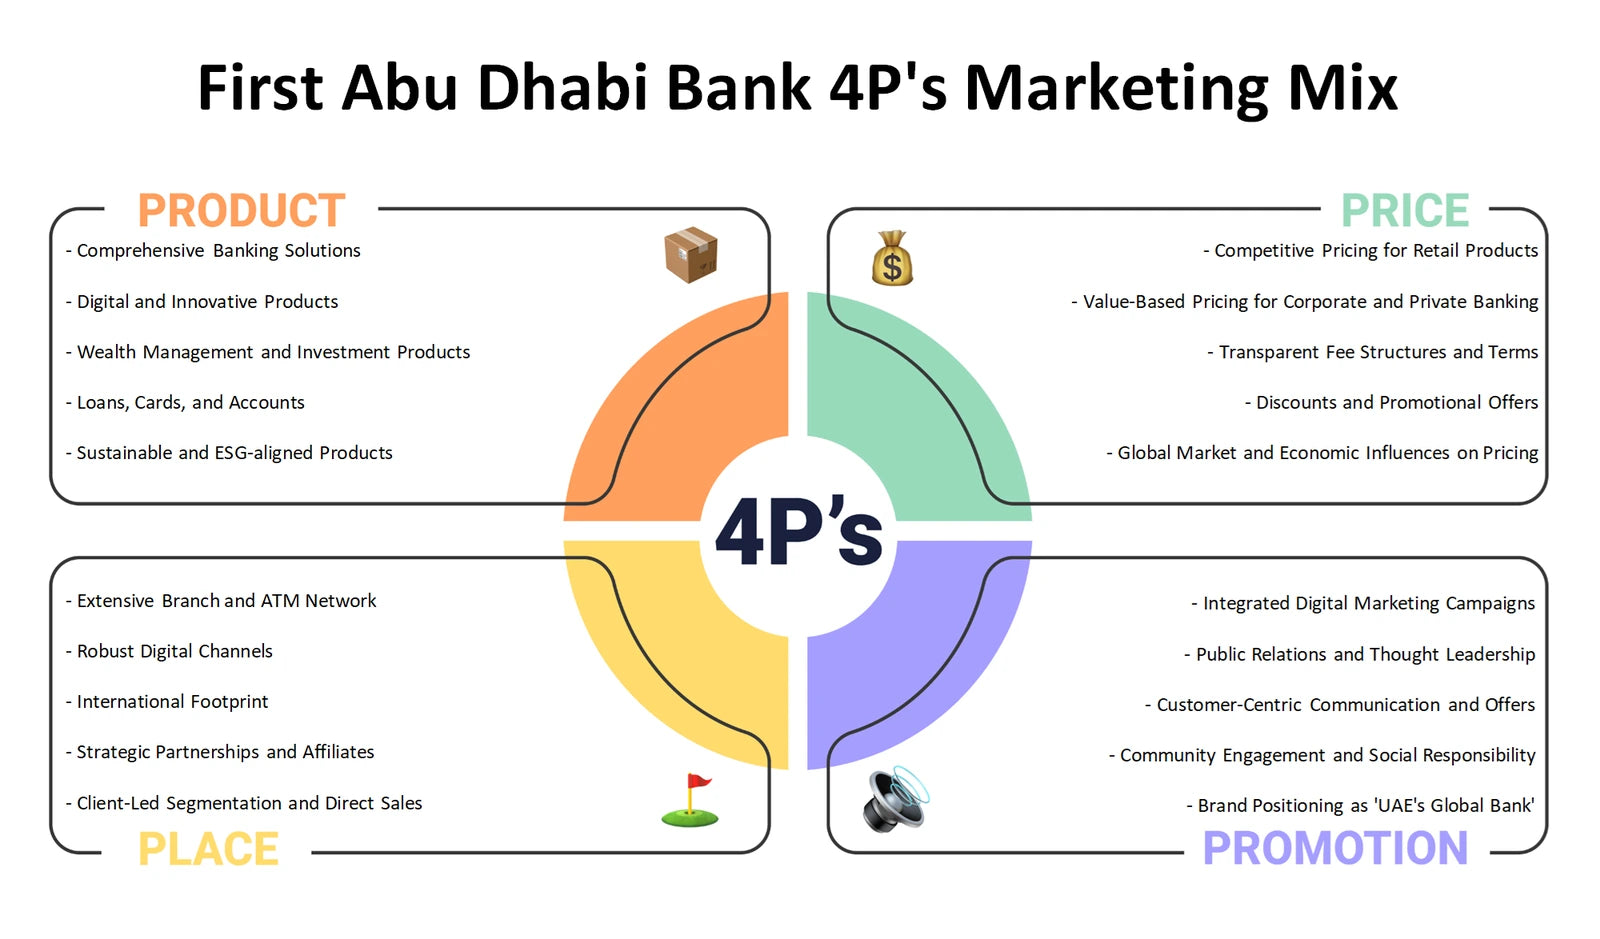
Marketing Mix (4Ps) summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored when assessing First Abu Dhabi Bank's operating context in the United Arab Emirates?
First Abu Dhabi Bank PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political questions can include the policy setting for financial-sector stability and economic development. Economic analysis can test the effect of financing demand, liquidity conditions and rate movements without claiming a current rate outcome. Social factors include changing expectations for convenience, trust and financial wellbeing. Technology covers secure digital journeys, data use and cyber resilience; legal factors include consumer protection, anti-financial-crime obligations and prudential requirements. Environmental considerations can include climate-related risk and evolving sustainability expectations affecting finance decisions.
- External scan. Distinguish documented external conditions from questions that require further monitoring or country-specific research.
- Risk linkage. Connect macro, regulatory and technology developments to customer demand, controls, operational cost and credit exposure.
- Monitoring map. Organise signals in the Excel PESTLE framework and use the Word analysis to consider why each external factor matters to the bank.
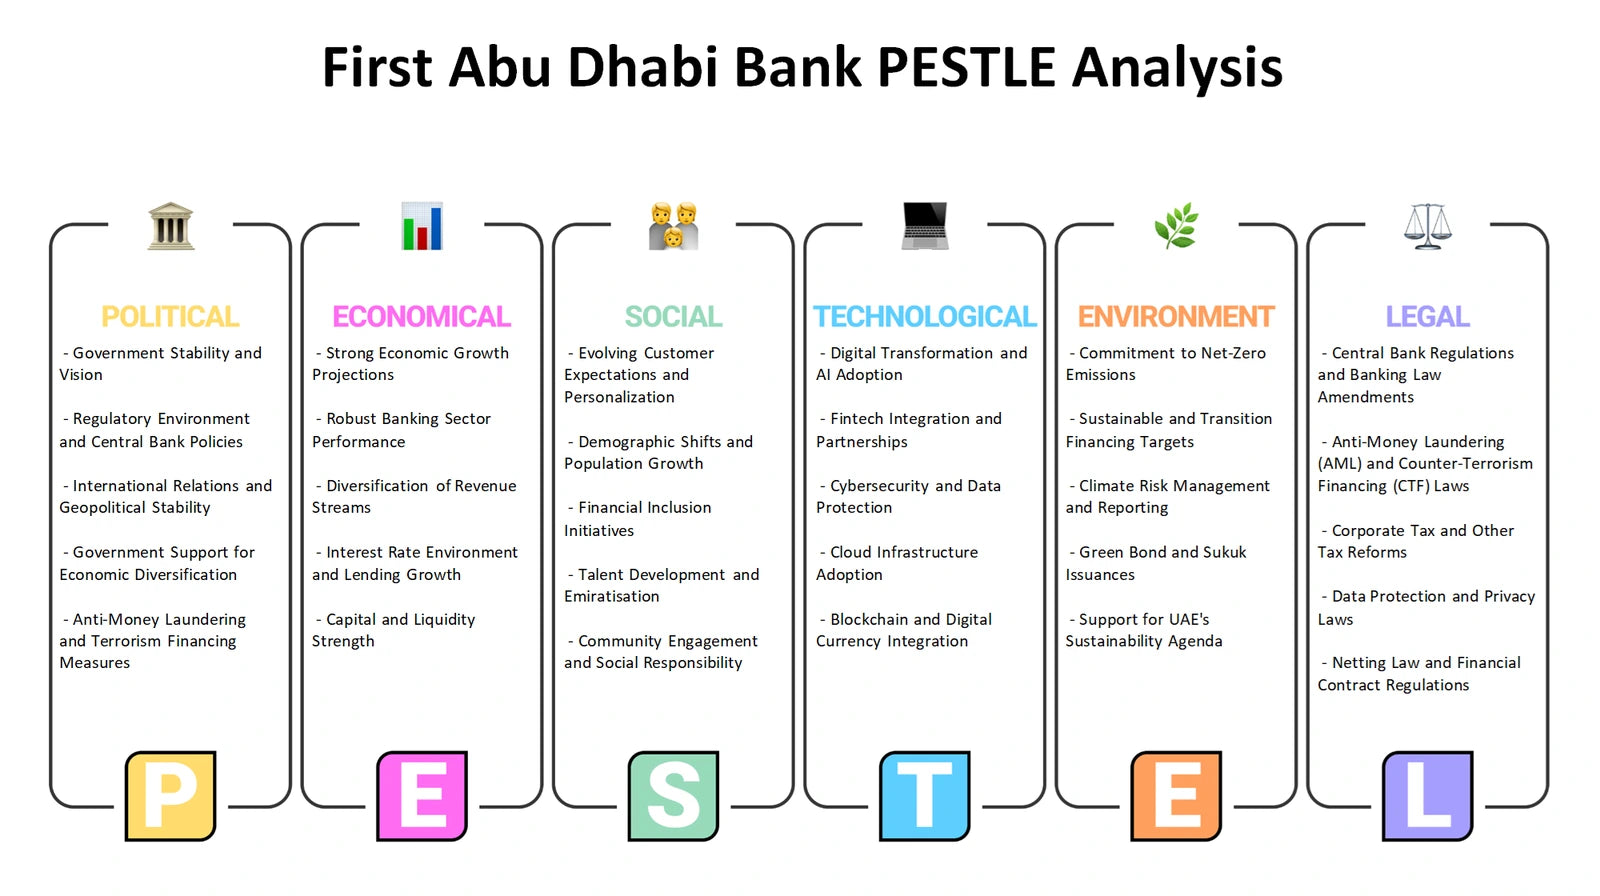
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can First Abu Dhabi Bank distinguish its internal capabilities and limitations from external opportunities and threats?
The First Abu Dhabi Bank SWOT analysis keeps internal and external issues in their proper categories. Strengths and weaknesses concern capabilities the bank can influence, such as the coherence of its personal and private banking proposition, service processes, specialist expertise, technology or risk-management capacity. Opportunities and threats arise outside the organisation: shifts in customer preferences, new financial technology, economic conditions, regulatory expectations and competitive alternatives. The framework does not claim that a possible strength or weakness has been independently proven. Instead, it provides a disciplined way to test potential themes against evidence and to avoid calling an external market trend an internal capability.
- Classification discipline. Separate controllable operating capabilities from external conditions that may create opportunities or introduce threats.
- Strategic fit. Explore whether possible banking strengths could support responses to changing customer, technology or regulatory conditions.
- Evidence-led review. Use the Excel SWOT layout to prioritise observations, with the Word analysis providing context for balanced internal-versus-external interpretation.
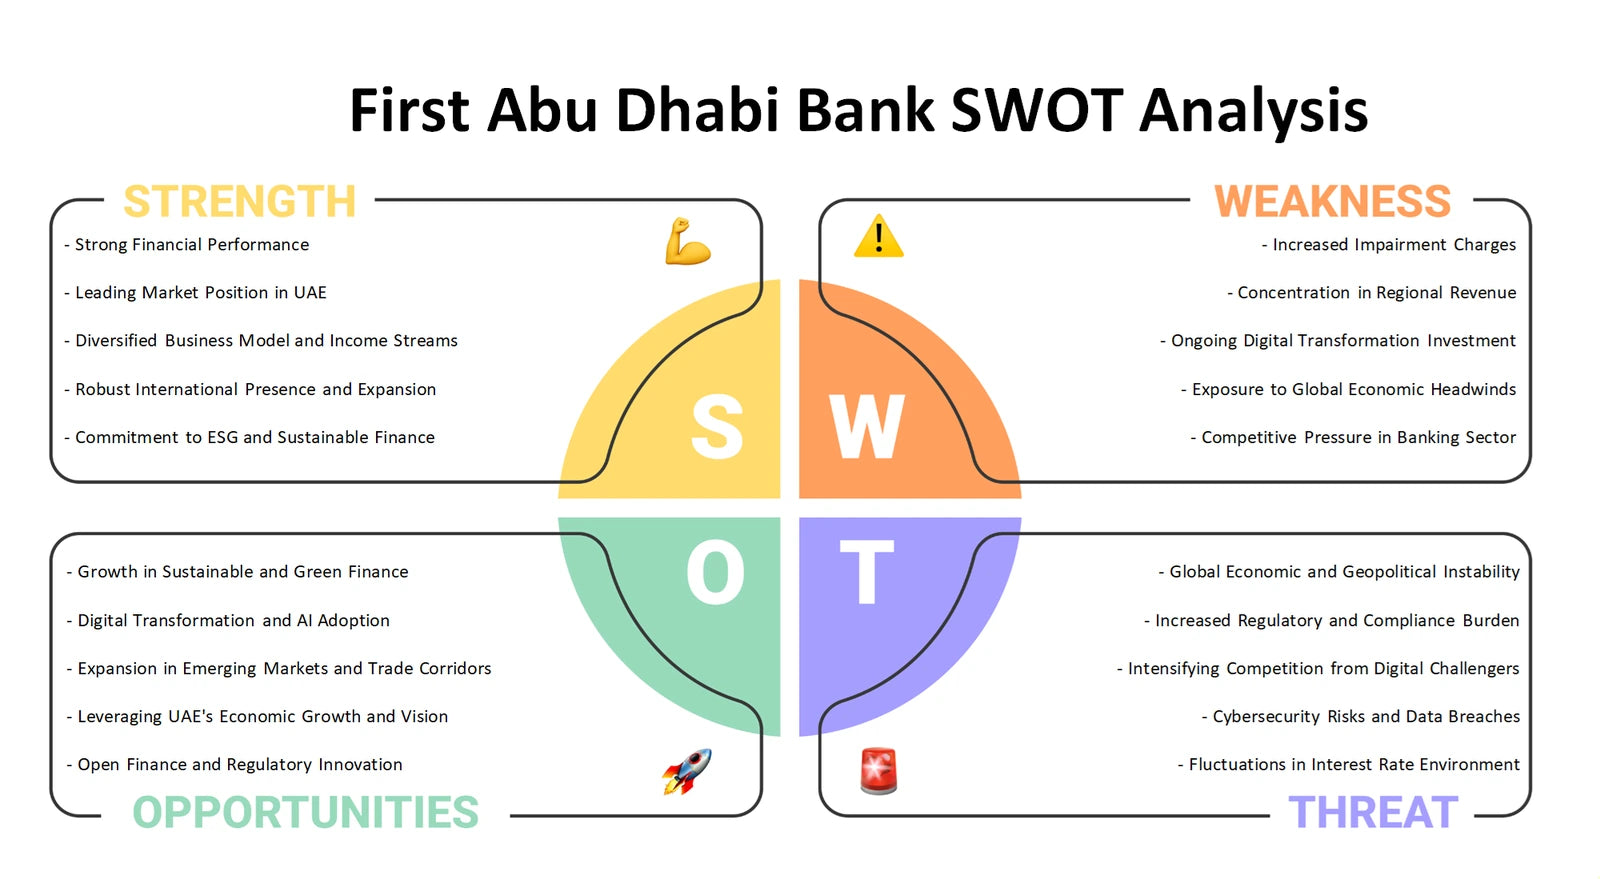
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of First Abu Dhabi Bank
Together, the six perspectives move from portfolio choices and business-model logic to industry pressure, customer-facing decisions, external conditions and strategic positioning. The Excel frameworks provide organised places to compare evidence and questions, while the detailed Word analysis helps develop a company-specific understanding of how banking propositions, risk, customer service and market change can interact.
Company background: First Abu Dhabi Bank — Personal Banking & Financial services page.