

Bâloise Group: Insurance Business – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Bâloise Group Strategy Analysis Bundle
Bâloise Group is the Swiss insurance business identified as Bâloise in public company references. Its core task is to help insurance customers manage financial exposure to uncertain events, while balancing underwriting capacity, claims obligations, customer service and capital resilience. This bundle frames those connected choices through six practical strategy lenses rather than treating insurance as a single, uniform market.
The supplied business context highlights risk-sharing with reinsurers and service partnerships relevant to health and casualty insurance. Those facts raise useful questions about portfolio priorities, the economics of risk transfer, access to service networks and changing external pressures. The Excel frameworks and detailed Word analyses help organise those questions without assuming unverified market shares, financial results or pre-set strategic conclusions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance activities merit capacity, service investment or tighter resource discipline as customer demand and relative market position change?
The Bâloise Group BCG Matrix helps separate portfolio discussion from assumptions about which line is automatically attractive. It compares market growth with relative market share and provides a disciplined way to consider Stars, Cash Cows, Question Marks and Dogs. For an insurer, the exercise can connect product families and customer needs to capital use, claims volatility, distribution effort and reinsurance support. It is especially useful where an area may grow quickly but require significant underwriting expertise or protection against severe losses.
- Portfolio comparison. Assess insurance activities against growth conditions and relative competitive position without assigning unsupported quadrant placements.
- Capacity trade-offs. Compare where underwriting appetite, service investment and risk-transfer capacity could matter most.
- Working view. Use the Excel grid to test classification assumptions, then use the Word analysis to record the evidence and strategic implications behind each category.
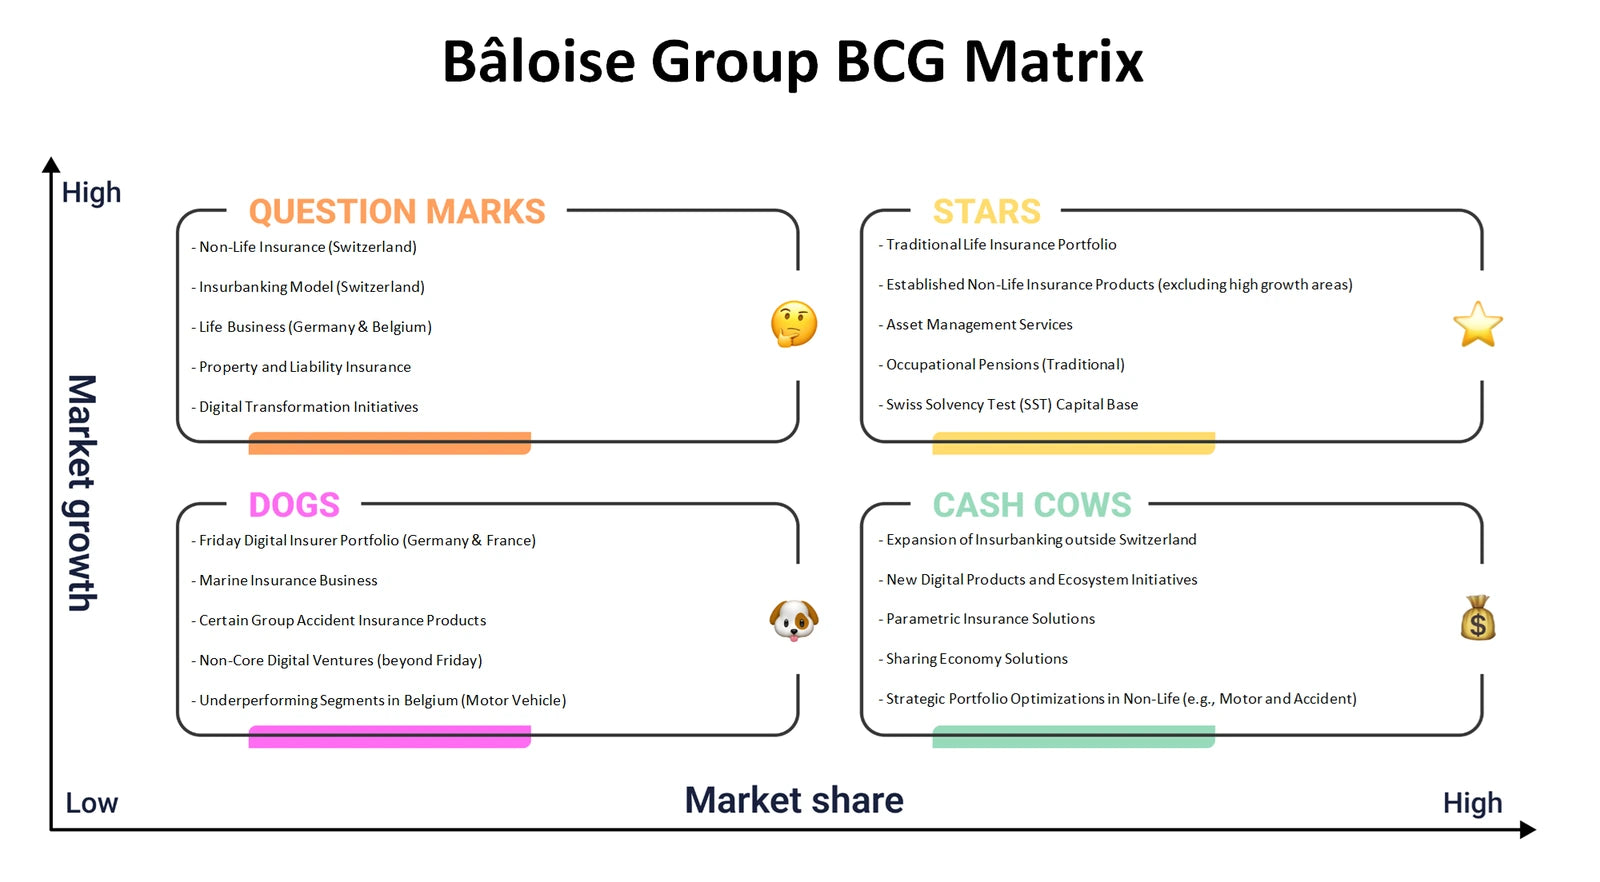
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, insurance services, partners and risk economics fit together in Bâloise Group's value-creation model?
The Bâloise Group Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In insurance, value is not only the policy promise; it also depends on underwriting, claims handling, trust, distribution and access to relevant service networks. Reinsurance relationships can be examined as partnerships that share selected risk and influence capacity, while healthcare-provider or service-network relationships can be assessed for their role in policyholder access and experience. The canvas helps make these operational and financial connections visible together.
- Customer logic. Examine how differing insurance customers may value protection, convenience, advice, claims support and access to services.
- Economic connections. Relate premium-based revenue streams and cost structure to underwriting work, claims obligations, technology and risk-sharing arrangements.
- Model mapping. Populate the Excel canvas block by block, using the Word analysis to explain dependencies, assumptions and questions for further validation.
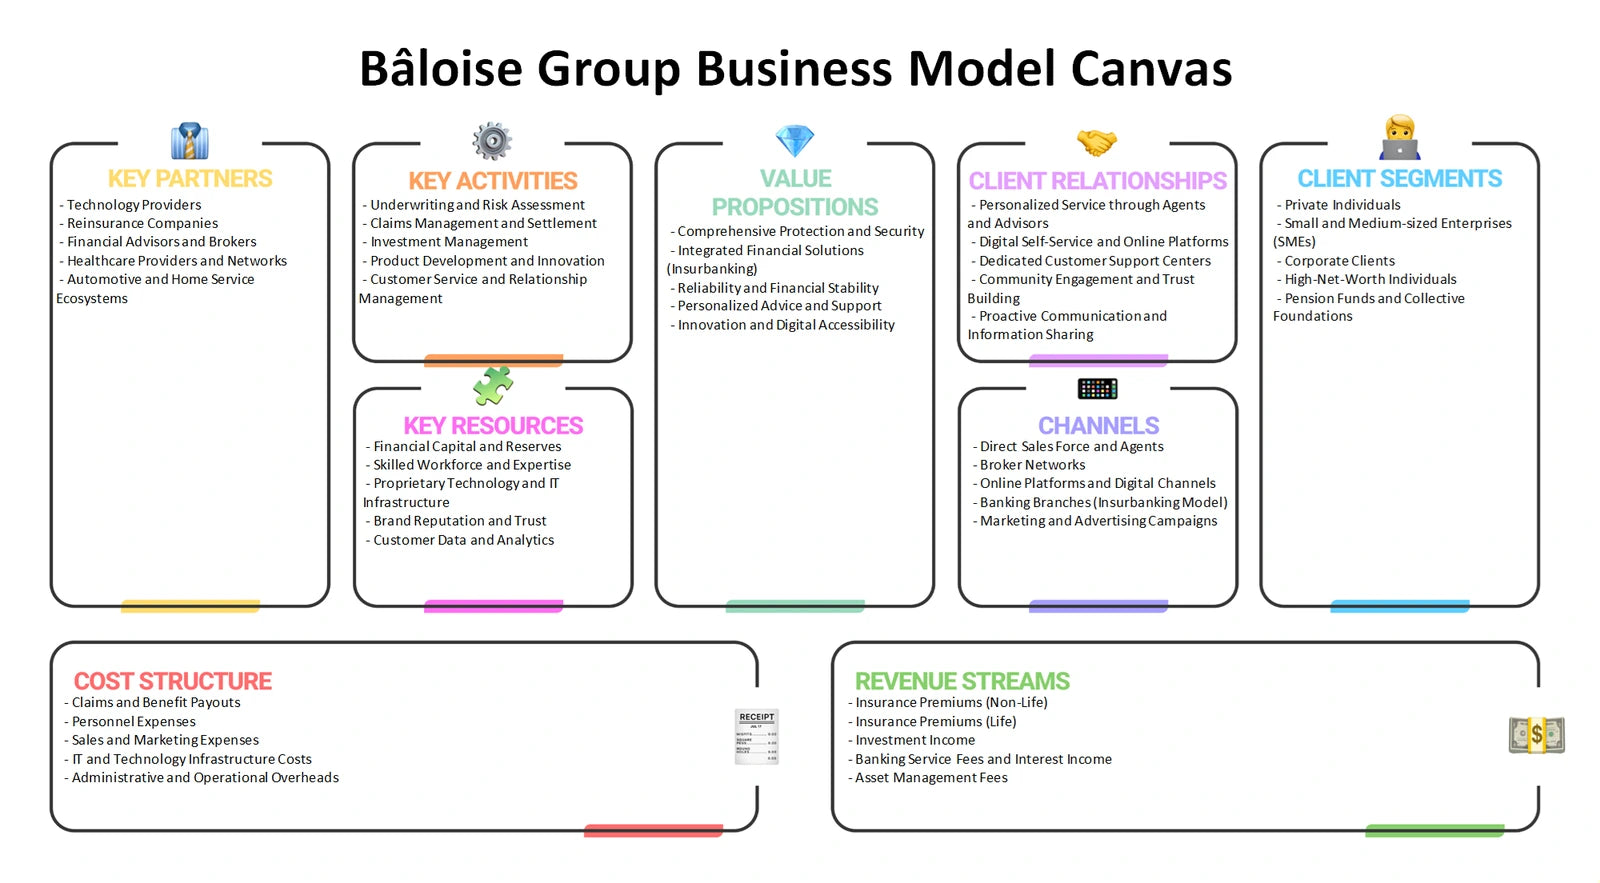
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape underwriting margins, customer retention and the cost of delivering insurance protection?
Bâloise Group Porter's Five Forces focuses on the structure surrounding a Swiss insurer rather than naming winners or assigning force scores. Rivalry can affect product differentiation, service standards and pricing discipline. Buyer power can rise where customers compare coverage, renewals and claims experiences, while supplier power may appear through technology, repair, medical-service, distribution or specialist-risk inputs. New entrants may seek selected digital or niche opportunities. Substitutes include alternative ways for households or businesses to absorb, self-fund or manage risk, not simply another insurer. This lens helps reveal where market pressure may alter the economics of protection.
- Rivalry and entry. Consider how competitive intensity and specialist entrants could influence customer choice and underwriting discipline.
- Counterparty leverage. Examine bargaining dynamics with policyholders, service providers, intermediaries and other essential contributors to delivery.
- Pressure map. Use the Excel framework to compare the five forces, then consult the Word analysis to interpret which questions deserve management attention.
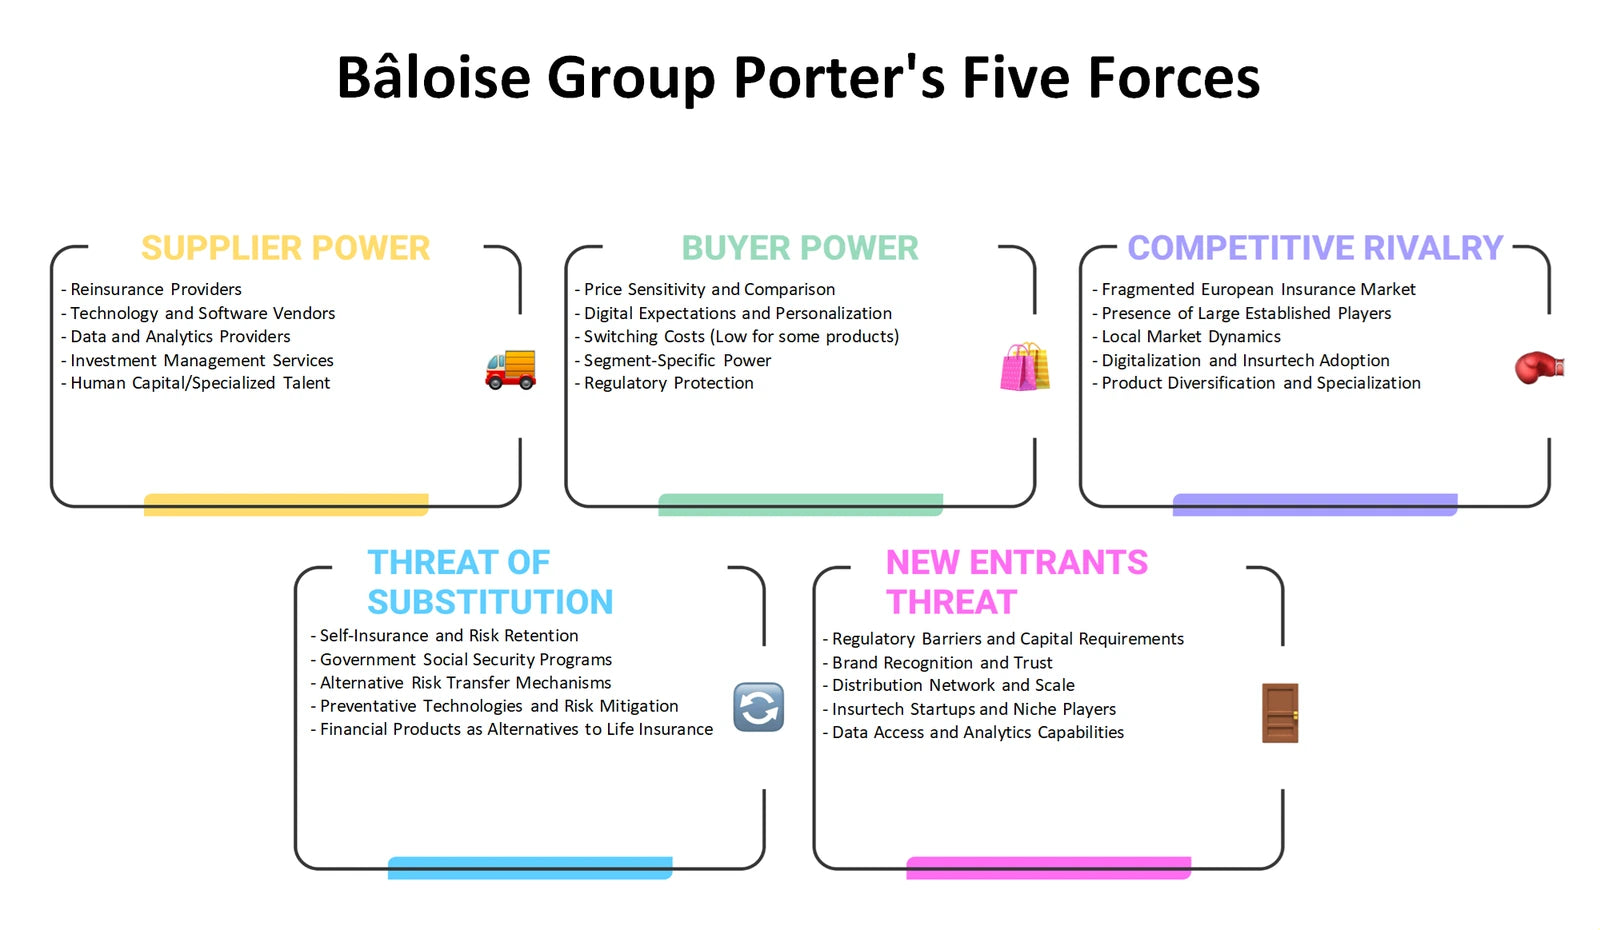
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can insurance propositions be assessed through the linked choices of product design, pricing, customer access and communication?
The Bâloise Group Marketing Mix applies Product, Price, Place and Promotion to a regulated, trust-based service purchase. Product analysis can consider coverage, service support and the practical experience around health or casualty claims. Price is broader than a visible premium: it can be assessed through risk selection, policy terms, perceived value and affordability questions. Place examines routes through which customers obtain information, advice and service, including relevant partner networks. Promotion considers how an insurer communicates protection, exclusions and service value clearly enough for customers to make informed choices. The four elements should be considered together, not as separate campaign ideas.
- Offer clarity. Explore how coverage design and claims-related service may address distinct customer risks and expectations.
- Route-to-customer fit. Compare the role of direct contact, advice and partner-enabled access without assuming channel shares.
- Mix review. Use the Excel 4Ps structure to compare choices by customer need, then use the Word analysis to capture trade-offs in positioning and communication.
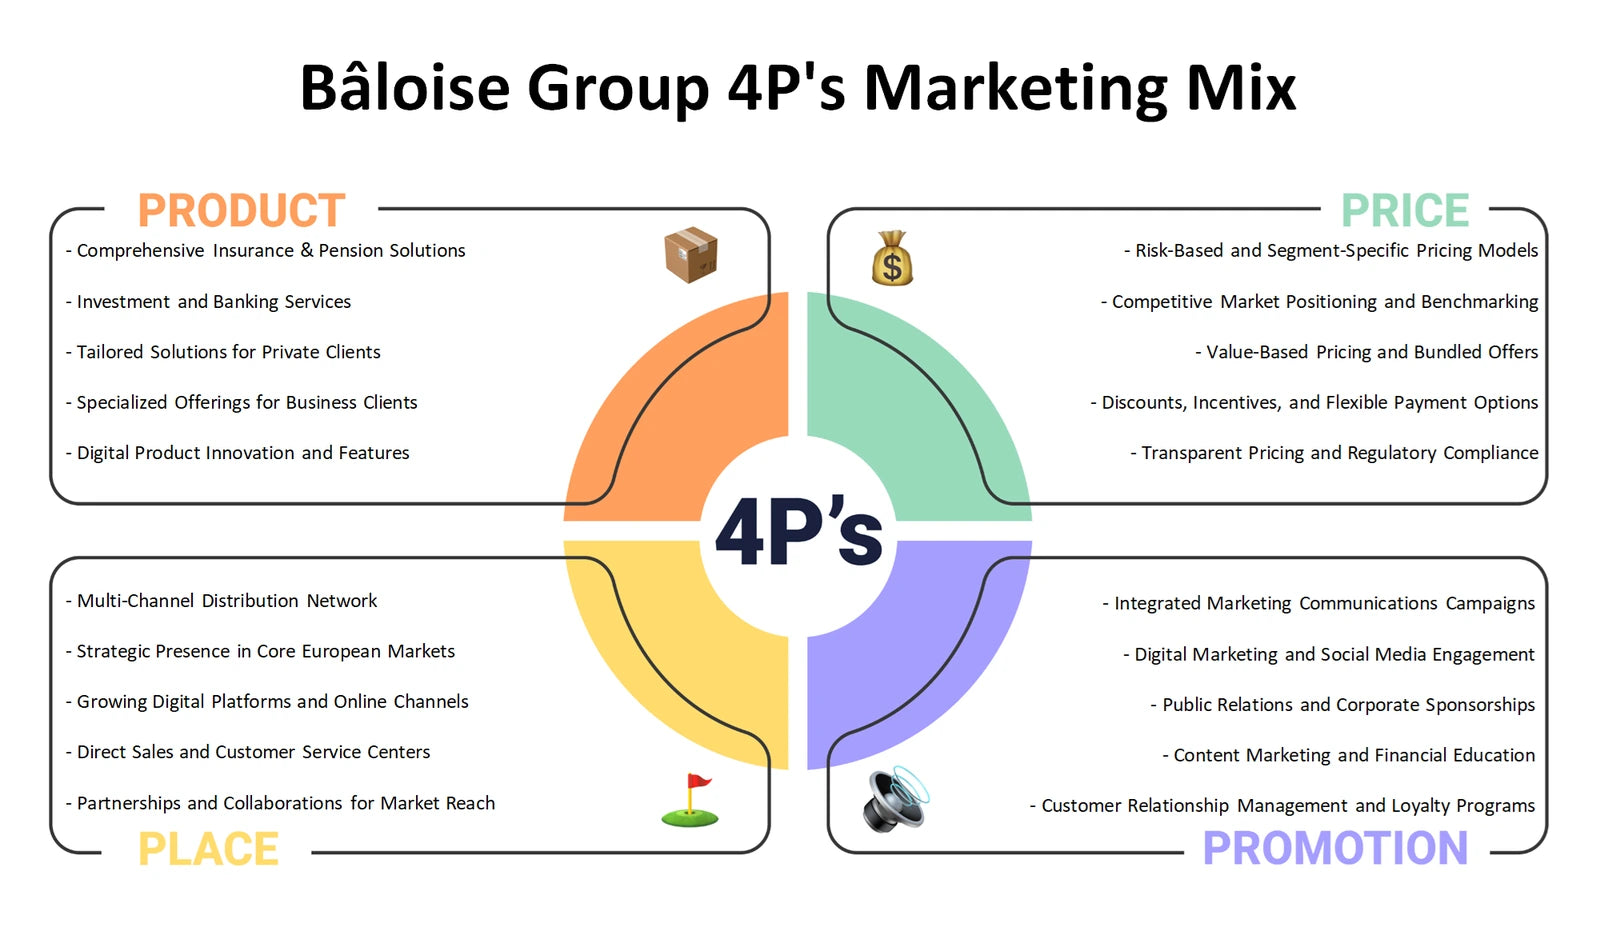
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter insurance demand, risk exposure, compliance work and operating costs for Bâloise Group?
Bâloise Group PESTLE analysis, also commonly called PESTEL, separates external change into Political, Economic, Social, Technological, Legal and Environmental dimensions. For a Swiss insurance business, relevant questions can include policy and supervisory expectations, household and business confidence, demographic and health-service needs, digital-service expectations, data and consumer-protection obligations, and the physical consequences of environmental events. Economic conditions may influence affordability, investment conditions and claims costs, but the framework should not treat a possible rate movement as a documented outcome. Environmental exposure matters because severe events can affect both claims patterns and reinsurance planning.
- External scanning. Organise developments by category so regulatory, customer, technology and environmental questions are not blended together.
- Exposure pathways. Trace how an external change could affect demand, underwriting, claims, capital resilience or operating processes.
- Scenario discipline. Use the Excel matrix to rank relevance and uncertainty, with the Word analysis providing context for discussing possible responses rather than predictions.
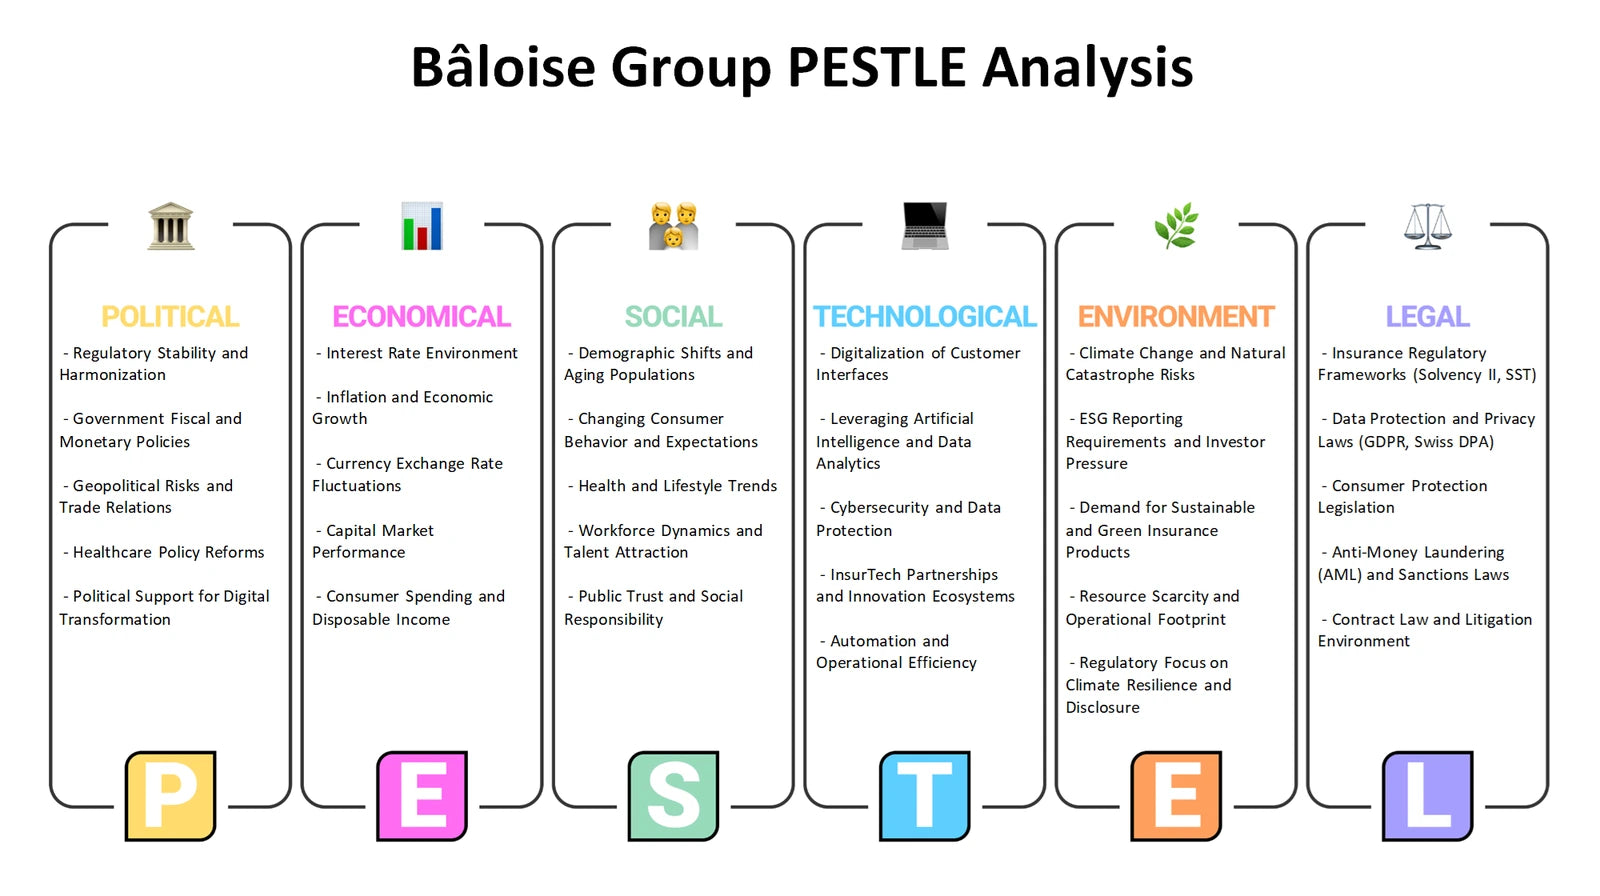
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Bâloise Group distinguish internal capabilities and limitations from opportunities and threats in its insurance environment?
The Bâloise Group SWOT analysis keeps internal and external factors in their proper categories. Strengths and weaknesses concern capabilities the business can influence, such as underwriting expertise, customer relationships, claims processes, partner management, data use or organisational complexity. Opportunities and threats arise outside the organisation, including shifts in customer expectations, regulation, technology adoption, catastrophe exposure and competitive conditions. The supplied context around reinsurance and healthcare-related partnerships offers useful themes to examine, but it does not prove that any theme is automatically a strength or weakness. SWOT is valuable when it links evidence to choices rather than becoming a list of generic insurance terms.
- Internal diagnosis. Consider which resources, processes and relationships may support reliable service and disciplined risk management.
- External fit. Compare those capabilities with changing market conditions, customer needs and sources of uncertainty.
- Decision record. Use the Excel four-quadrant framework to separate observations, while the Word analysis helps explain links between themes and possible strategic priorities.
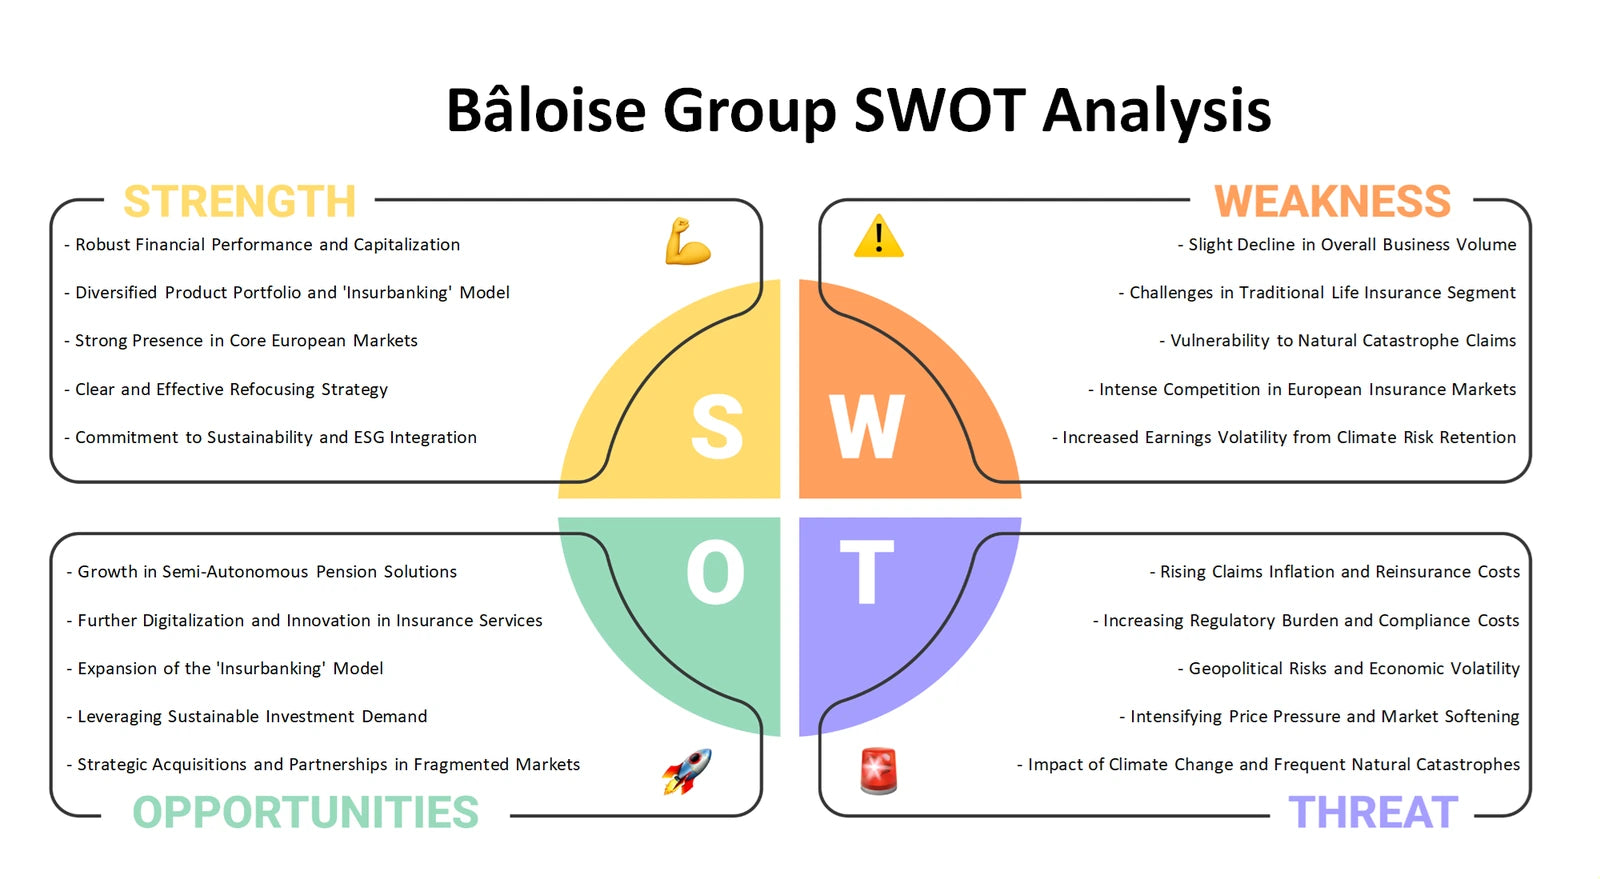
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices to insurance value creation
Together, the six perspectives help turn broad questions about Bâloise Group into a more connected strategic picture. The BCG Matrix considers portfolio priorities; the Canvas maps value creation; Five Forces and PESTLE examine external pressure; the 4Ps tests customer-facing choices; and SWOT brings internal and external themes together. Use the Excel frameworks to structure comparisons and the Word files to develop a reasoned company-specific discussion.
Company background: Bâloise Group — Wikidata company profile.