

Atlantic Union Bank: Banking Business and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Atlantic Union Bank Strategy Analysis Bundle
Atlantic Union Bank is a Virginia-based retail bank serving customers through branches in Virginia, Maryland and North Carolina. Its role is to support households and businesses with deposit, credit and related financial-service relationships in local markets where trust, convenience and responsive banking access can shape customer choice.
The supplied business context describes third-party distribution relationships that can extend access to mortgage, insurance and wealth offerings, alongside community investment partnerships connected to CRA-related goals. These are useful analytical inputs rather than pre-set conclusions: the bundle helps compare portfolio priorities, partner economics and competitive pressures in relationship-driven banking.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking activities and local market opportunities merit the greatest capital, management attention and relationship-building effort?
The Atlantic Union Bank BCG Matrix helps separate the appeal of a market from the bank's relative market share within it. For a retail bank, the relevant units may be customer-product and geography combinations rather than a single corporate total: for example, core deposit relationships, lending activity or partner-supported fee opportunities in defined local markets. The framework uses market growth and relative share to test possible Stars, Cash Cows, Question Marks and Dogs; it does not assign any Atlantic Union Bank activity to a quadrant without evidence. This distinction matters because a fast-growing banking need may still require careful investment, while a mature relationship base may generate capacity to support selective expansion.
- Market definition. Compare each potential unit by customer need, service line and geography so relative share is assessed against an appropriate banking market.
- Resource priority. Consider where branch capacity, digital service investment, lending expertise and partner-management effort could be most productively concentrated.
- Matrix workflow. Use the Excel framework to organize growth and relative-share assumptions, then use the Word analysis to record the strategic rationale and evidence limits behind each comparison.
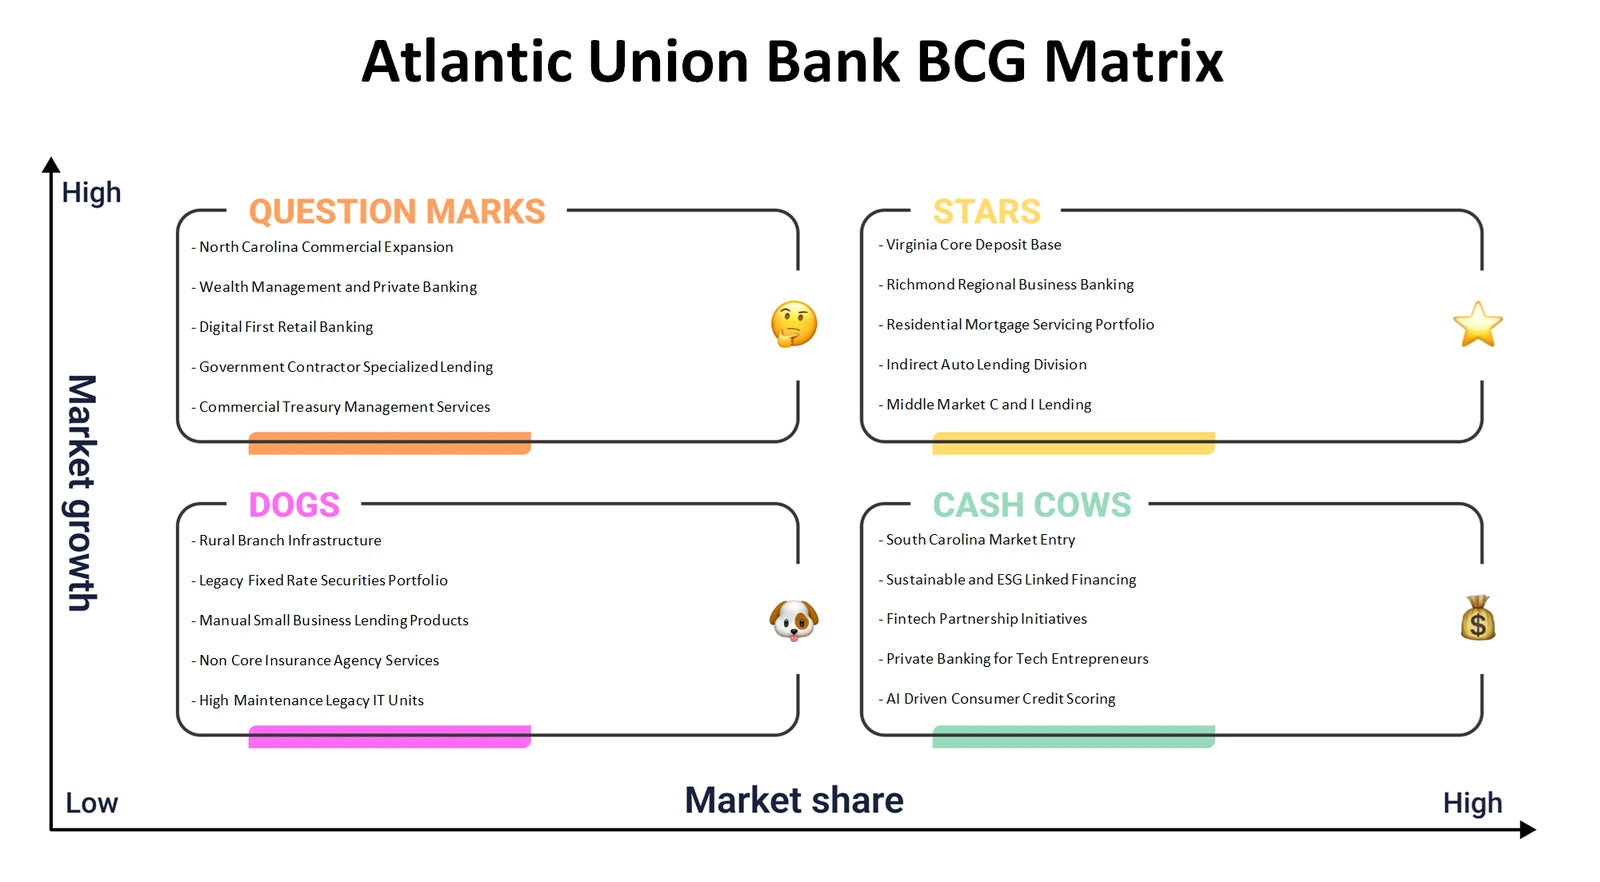
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do local banking relationships, delivery channels and partnerships connect to a sustainable revenue and cost model?
The Atlantic Union Bank Business Model Canvas brings the nine building blocks into one operating view. It examines customer segments such as households and businesses; value propositions built around banking access and relationship service; and channels spanning branches, digital touchpoints and relevant partner routes. Customer relationships, revenue streams and cost structure can then be considered alongside key resources, key activities and key partnerships. The supplied context makes partnership questions especially relevant: distributors may broaden mortgage, insurance or wealth-service access, while community partners can connect commercial goals with local-development activity. The canvas helps show the trade-offs between offering breadth, control of the customer relationship, compliance demands and noninterest fee potential.
- Value chain links. Trace how a customer need moves from relationship management and channel access to banking revenue, partner economics and operating cost.
- Partnership choices. Examine where external distribution or community collaboration may complement internal capabilities without assuming every service must be owned directly.
- Connected model. Populate the Excel canvas block by block, then use the Word analysis to explore dependencies between relationships, resources, activities and financial logic.
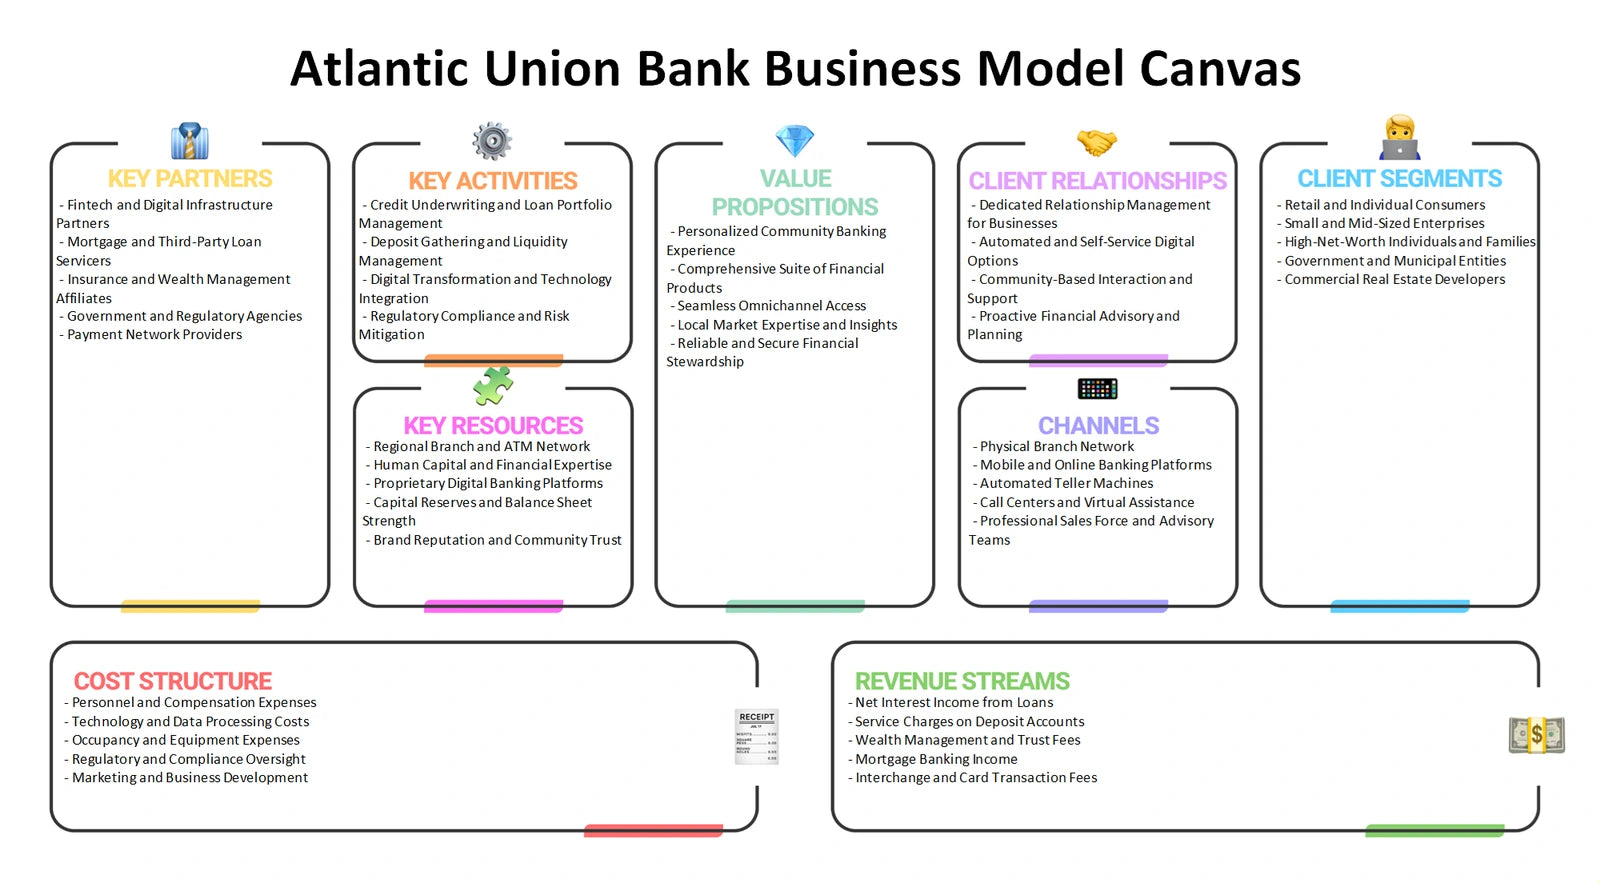
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness of relationship-based retail banking in Atlantic Union Bank's markets?
Atlantic Union Bank Porter's Five Forces analysis examines the structure surrounding retail banking rather than making unsupported claims about a specific rival. Rivalry can arise through competing banks and financial-service providers seeking deposits, lending relationships and local business customers. Buyer power considers how readily households or businesses can compare rates, fees, service quality and digital convenience. Supplier power is relevant to funding, technology, specialist talent and third-party providers. The threat of entrants includes new banking models and digitally focused providers, while substitutes include alternative ways customers meet payment, saving, lending or wealth-management needs. Looking across all five forces helps explain why differentiated relationship service and disciplined operating economics may matter together.
- Customer switching. Assess the conditions that can increase customer bargaining power, including transparent product comparison and convenient alternative providers.
- Service substitutes. Distinguish direct banking competitors from alternative payment, lending, investment or insurance routes that solve part of the same customer need.
- Pressure map. Use the Excel framework to compare the five forces consistently and the Word analysis to document how each pressure may affect margins, retention or channel decisions.
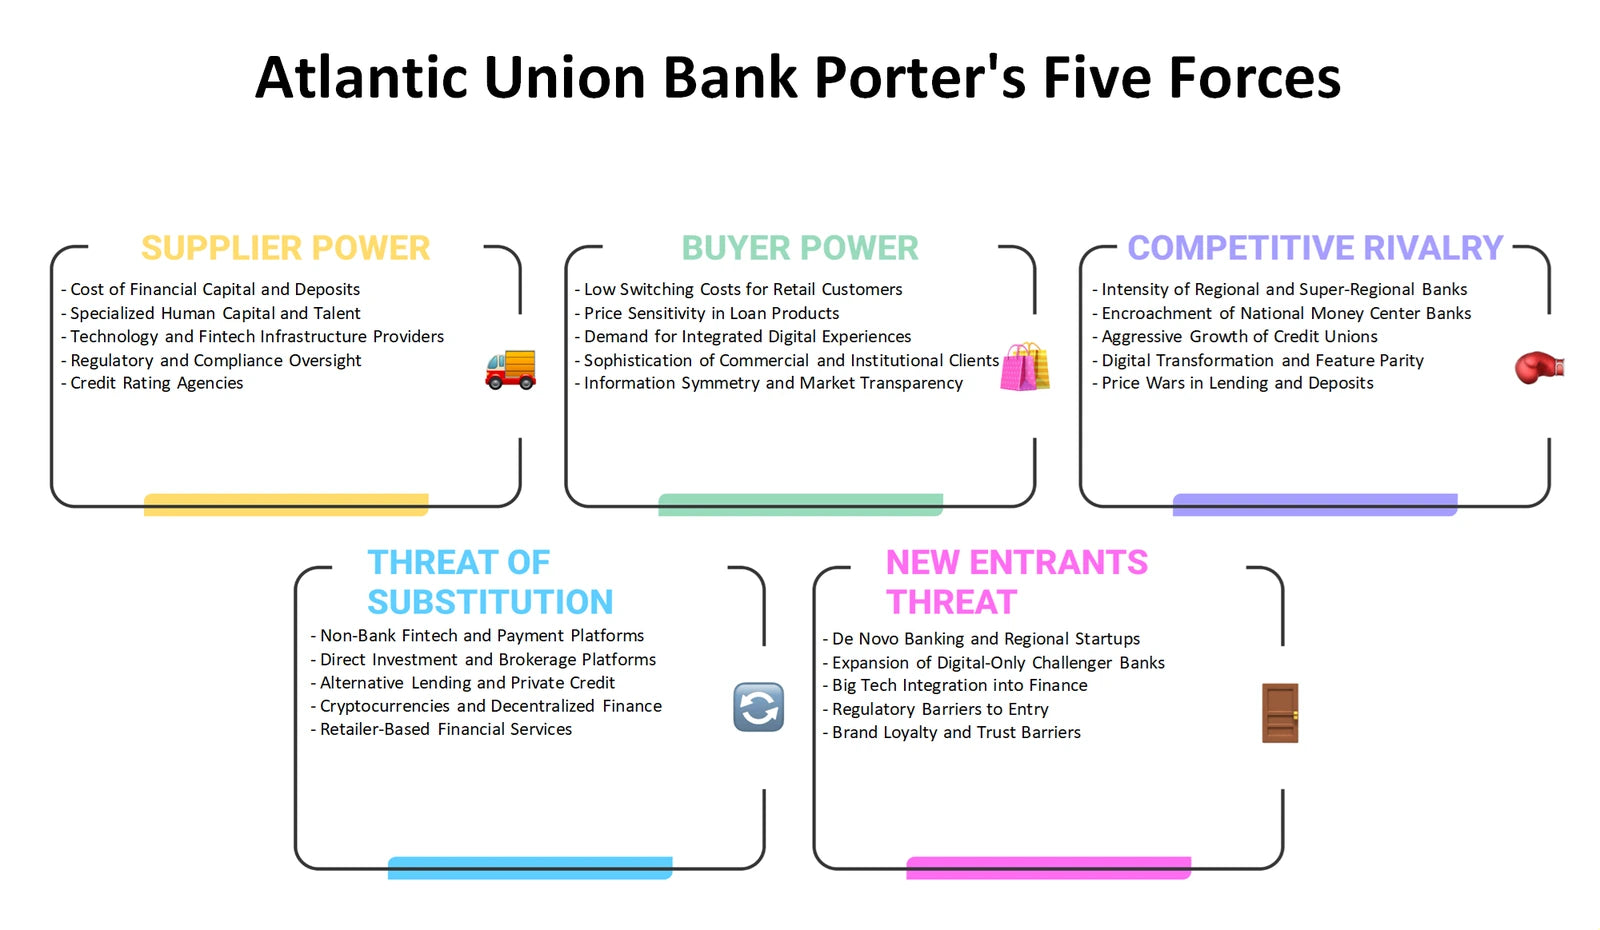
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, delivery access and communication reinforce a trusted banking relationship?
The Atlantic Union Bank Marketing Mix considers Product, Price, Place and Promotion in a regulated service setting. Product analysis can examine how deposit, credit and related financial-service needs are assembled for households and businesses, including where partner-enabled offerings may complement core banking. Price is broader than a posted fee: it includes rates, fees, terms, perceived value and the clarity with which customers can understand them. Place covers branch access across the bank's footprint, digital service journeys and relevant third-party routes. Promotion asks how the bank can communicate useful, understandable value while maintaining the care expected in financial-services marketing. The four Ps help connect customer acquisition with retention and relationship depth rather than treating promotion as an isolated campaign question.
- Offering fit. Compare customer needs with the role of core banking products and adjacent services in a coherent relationship proposition.
- Access and clarity. Evaluate how branch, digital and partner channels affect service convenience, disclosure, confidence and follow-through.
- Planning tool. Use the Excel structure to align the four Ps for each target audience, while the Word analysis provides narrative context for the resulting trade-offs.
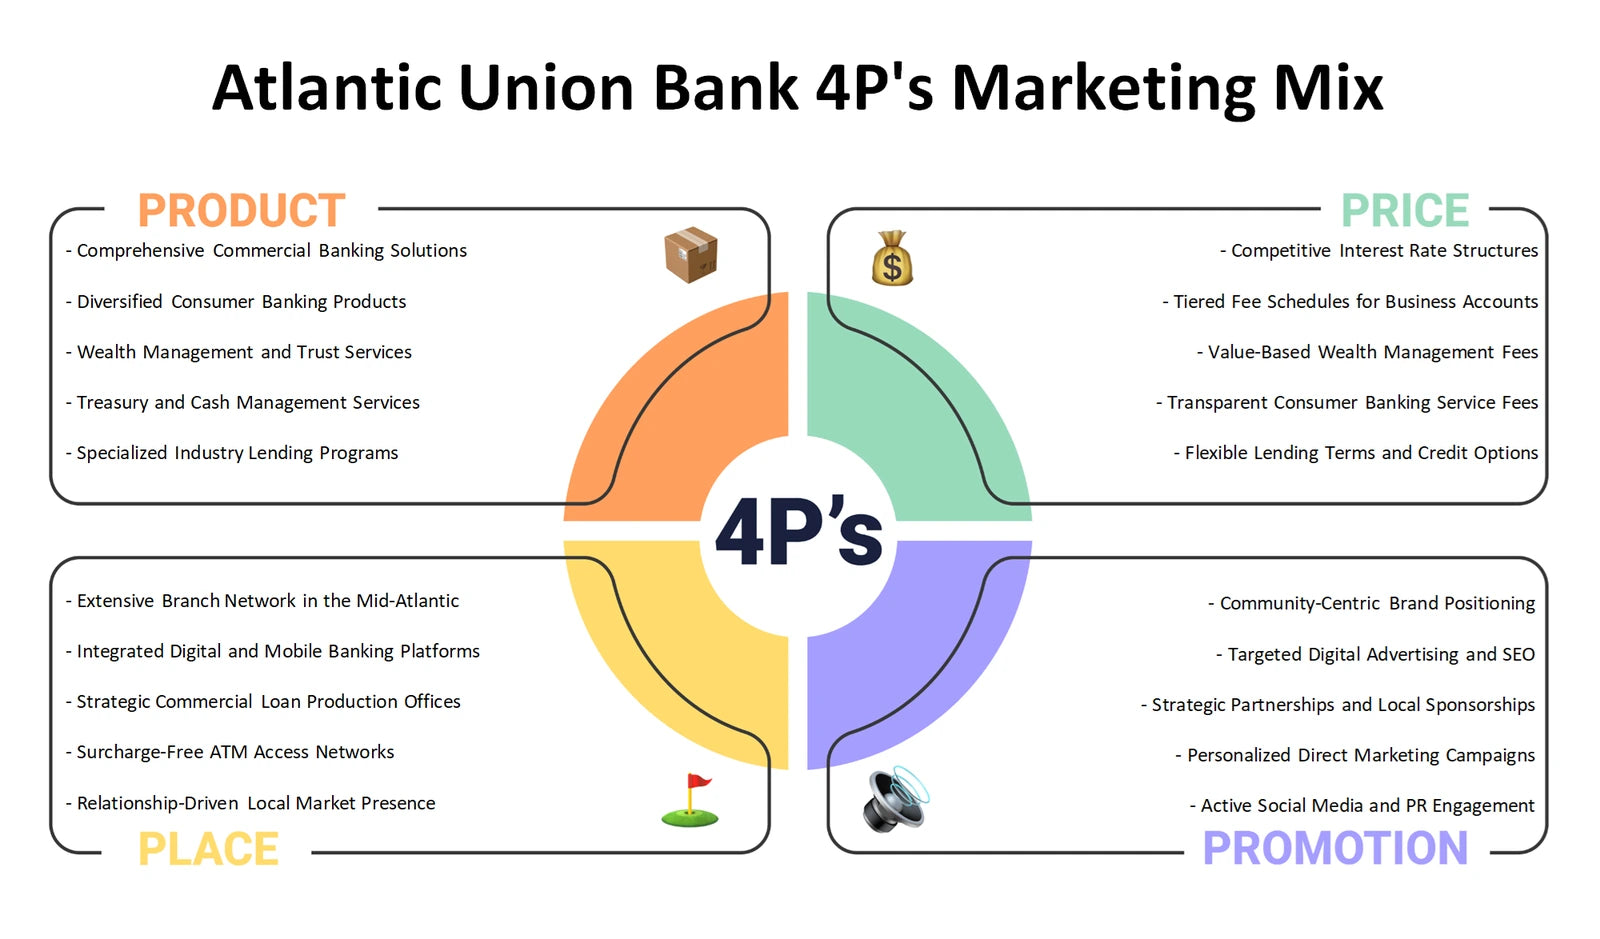
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored when planning retail banking services across Virginia, Maryland and North Carolina?
The Atlantic Union Bank PESTLE analysis, also commonly called PESTEL, organizes the external conditions that can reshape customer needs and banking operations. Political and Legal factors include the policy, supervisory and consumer-protection environment relevant to financial institutions. Economic questions include interest-rate conditions, household affordability, business demand and credit quality; they should be analyzed rather than assumed from any current-rate claim. Social factors cover demographic patterns, trust, financial confidence and expectations for local service. Technological change can alter digital banking, payment expectations, cybersecurity needs and third-party dependencies. Environmental considerations may affect property, community resilience and lending exposures. This lens helps keep external change separate from internal capability.
- Regional exposure. Consider how economic and social conditions may differ across the bank's branch markets rather than applying a single national assumption.
- Compliance horizon. Track policy and legal questions as possible planning influences without presenting an unverified rule change as a documented fact.
- Monitoring register. Use the Excel framework to categorize and prioritize external signals, then use the Word analysis to explain possible implications for customers, channels and risk decisions.
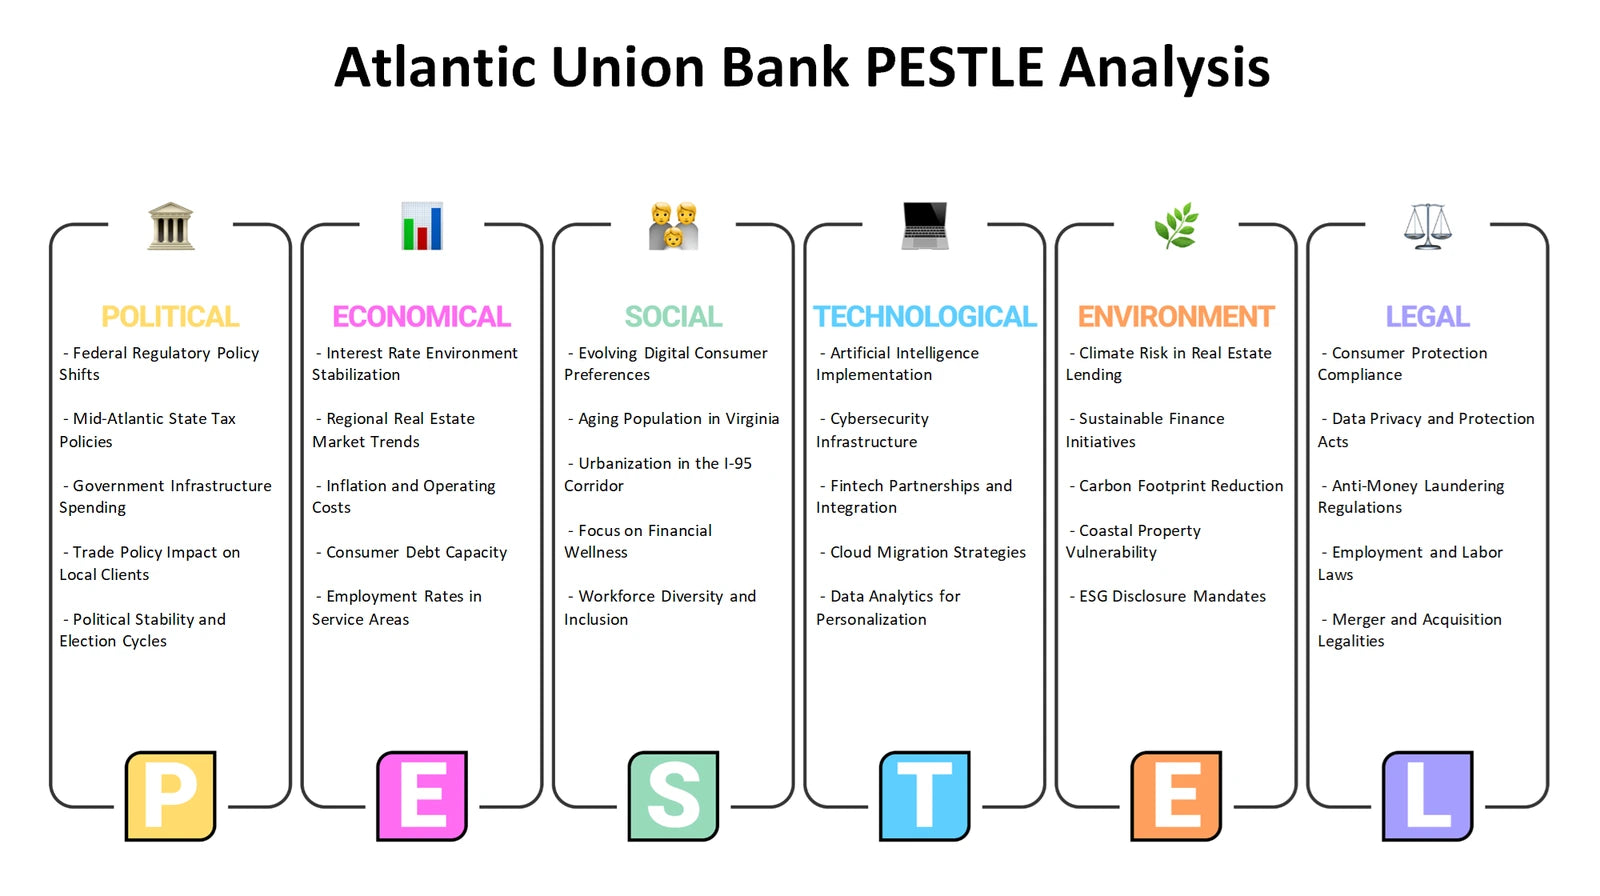
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be weighed against external opportunities and threats in relationship-led banking?
The Atlantic Union Bank SWOT analysis separates internal conditions from the outside market. Strengths may be investigated through local relationships, branch-market knowledge, service capabilities and partnership-management capacity; weaknesses may include capability gaps, cost pressures, channel complexity or limits in scale. Opportunities are external possibilities, such as changing customer needs or underserved relationship niches, while threats include competitive intensity, economic uncertainty, technology risk and regulatory pressure. The framework should not convert plausible themes into confirmed findings. Instead, it gives a disciplined way to test whether an internal capability can support an external opportunity, or whether a weakness increases exposure to a threat. That distinction is valuable when balancing community ties, digital expectations and the economics of a broader service offering.
- Correct classification. Separate controllable internal resources and constraints from market conditions that the bank must monitor and respond to.
- Strategic fit. Explore whether relationship strengths or partner capabilities could address a particular opportunity while identifying risks that need mitigation.
- Decision narrative. Use the Excel grid to capture concise evidence and priorities, then use the Word analysis to develop the reasoning behind selected strength-opportunity and weakness-threat links.
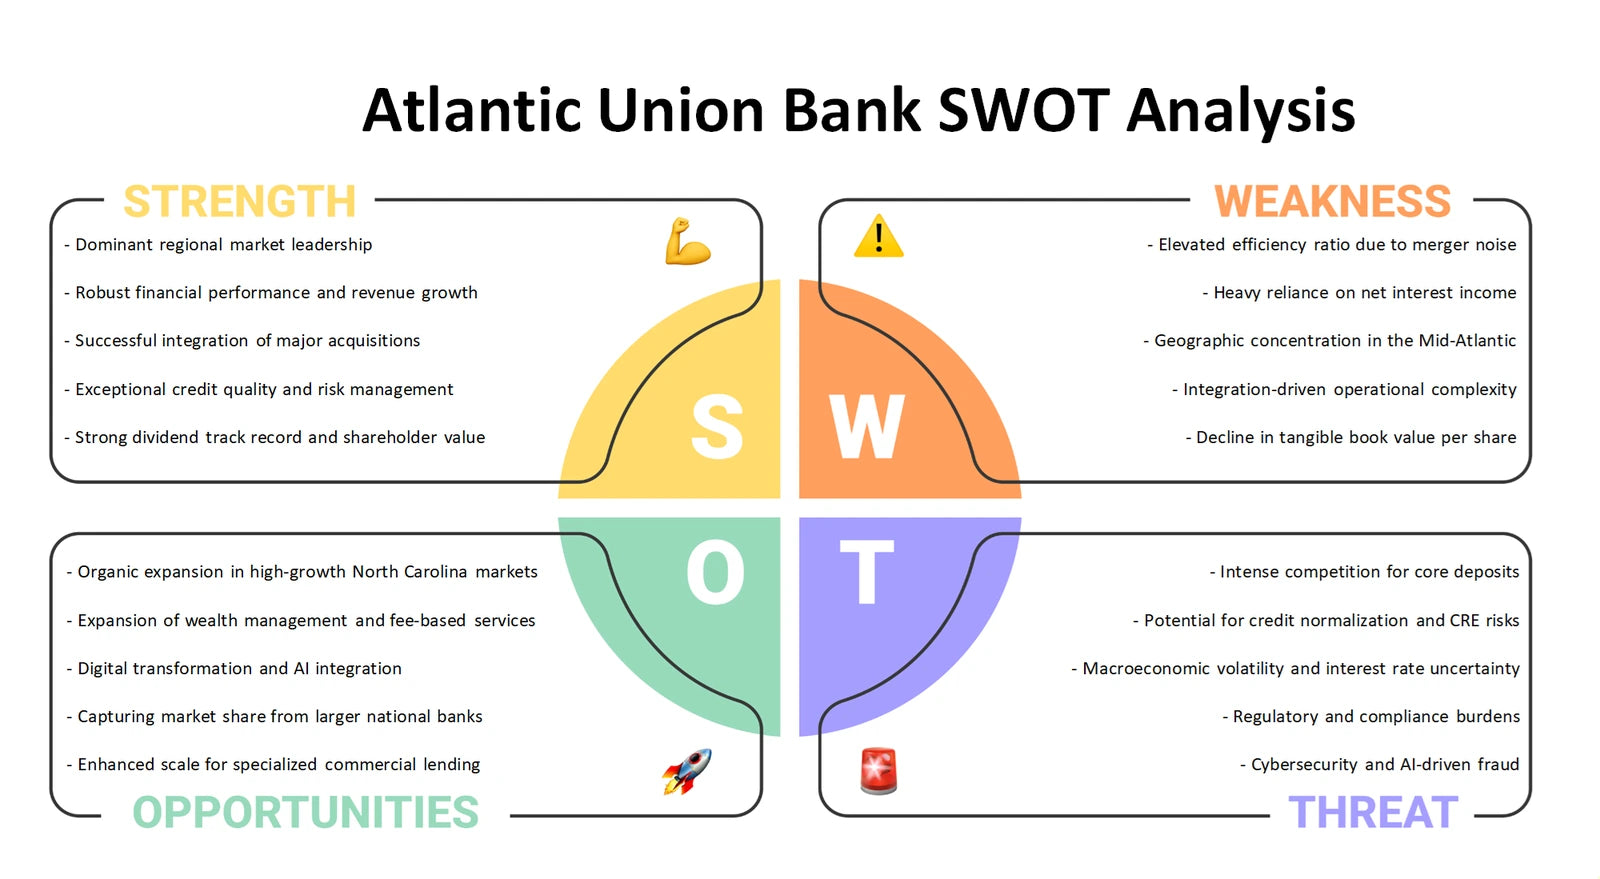
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more connected view of Atlantic Union Bank
Together, the six perspectives move from portfolio choices and business-model economics to industry structure, customer-facing decisions, external change and strategic fit. The Excel frameworks help organize comparable questions, while the detailed Word analysis supports fuller interpretation of banking relationships, partner roles, local-market realities and trade-offs. Used together, they provide a structured starting point for discussion, planning and investor-focused analysis without presenting assumptions as established results.
Company background: Atlantic Union Bank — official website.