

Amerisafe: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Amerisafe Strategy Analysis Bundle
Amerisafe refers here to AMERISAFE INC., the SEC-reporting insurer serving small and mid-sized employers with specialized workers’ compensation coverage for higher-hazard industries. Its business model depends on underwriting discipline, relationships with insurance agents and brokers, and reinsurance arrangements that help manage concentrated or volatile loss exposure.
In its Form 10-Q filed July 23, 2026, AMERISAFE INC. reported revenue of USD 91.971 million and GAAP net income of USD 14.595 million for April 1 through June 30, 2026. Those figures provide context for questions about profitable underwriting capacity, distribution economics and external claims pressures; they do not indicate when the downloadable analysis files were prepared.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance product or customer-market priorities deserve capacity, protection or tighter resource discipline?
The Amerisafe BCG Matrix applies market growth and relative market share to a portfolio discussion rather than assuming that every workers’ compensation opportunity should receive the same underwriting appetite. For a specialist insurer, the useful comparison can involve classes of high-hazard employers, distribution opportunities or product-market positions. The framework distinguishes the logic of Stars, Cash Cows, Question Marks and Dogs while leaving actual quadrant placement to evidence-based review. It helps connect growth ambitions with capital, reinsurance capacity, claims expertise and the need to protect underwriting quality.
- Portfolio lens. Compare mature, cash-generating areas with emerging or uncertain opportunities without treating premium volume alone as strategic success.
- Capacity trade-off. Examine where specialist underwriting attention and risk-transfer support may be most valuable when exposures differ by customer class.
- Structured comparison. Use the Excel framework to organize relative-share and market-growth assumptions, then use the Word analysis to interpret priority questions and evidence gaps.
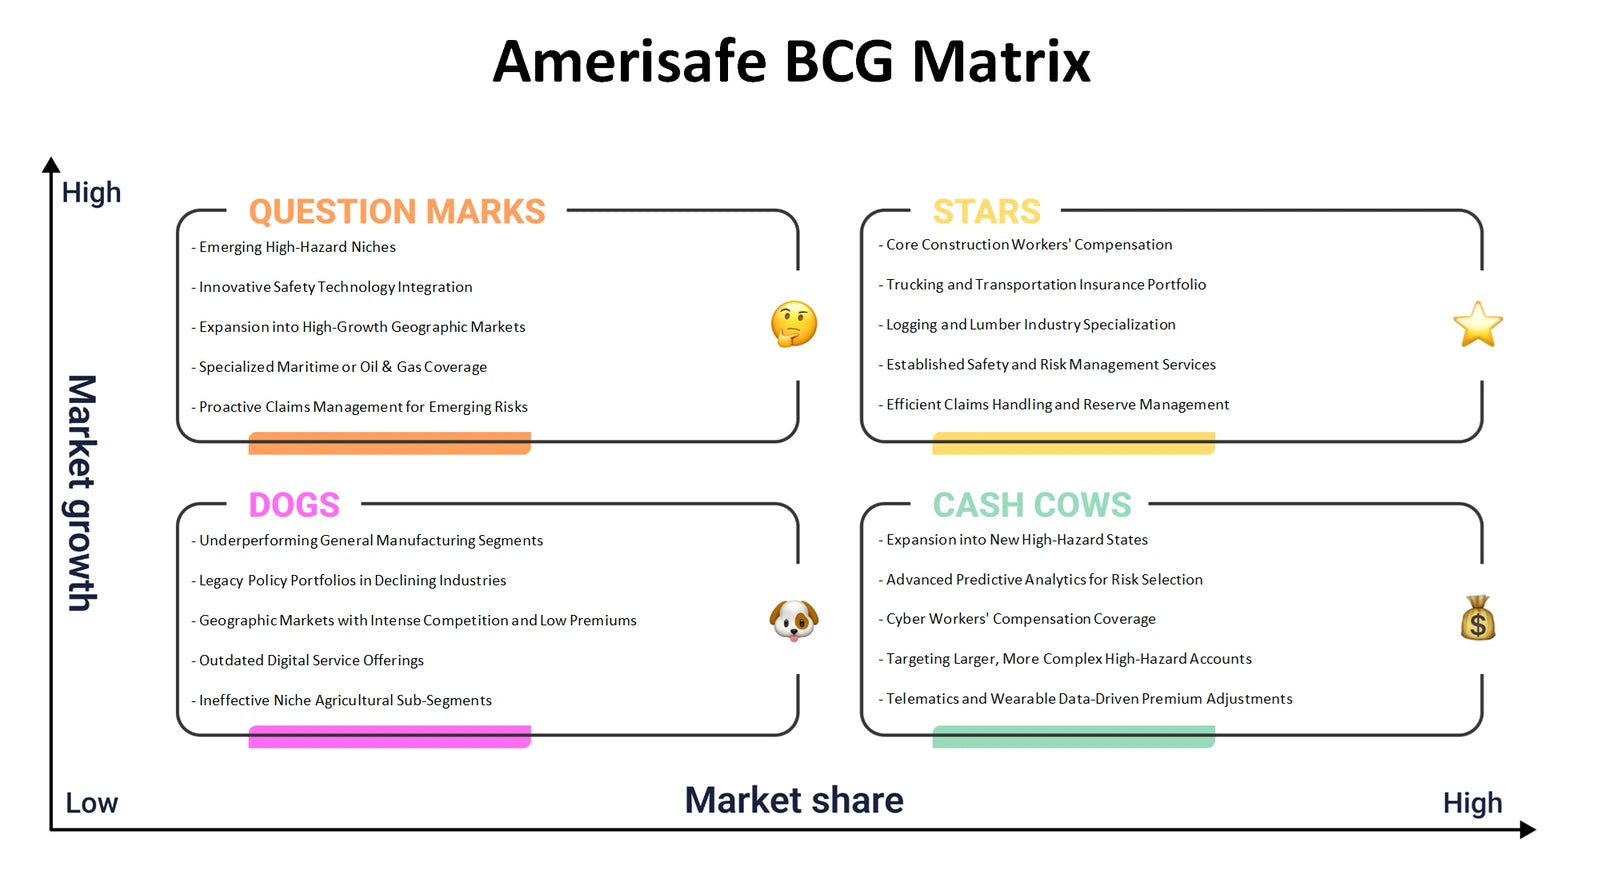
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do underwriting expertise, intermediary distribution and risk sharing combine to create economic value?
The Amerisafe Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It is especially useful for connecting high-hazard employers’ insurance needs with the broker and agent channel that reaches them. The analysis can explore how underwriting, policy administration, claims capability and risk selection support the customer proposition, while reinsurance partnerships influence capacity and financial resilience. It also helps distinguish earned insurance revenue logic from the operating costs and loss-related obligations behind it.
- Customer connection. Assess how specialized coverage needs of smaller and mid-sized businesses shape the value proposition and intermediary-led customer access.
- Economic engine. Map the relationship between revenue streams, underwriting activities, expert resources, reinsurance partners and the cost structure of serving riskier occupations.
- Model mapping. Populate the Excel canvas as a connected operating map and use the Word analysis to add explanation behind each block and its dependencies.
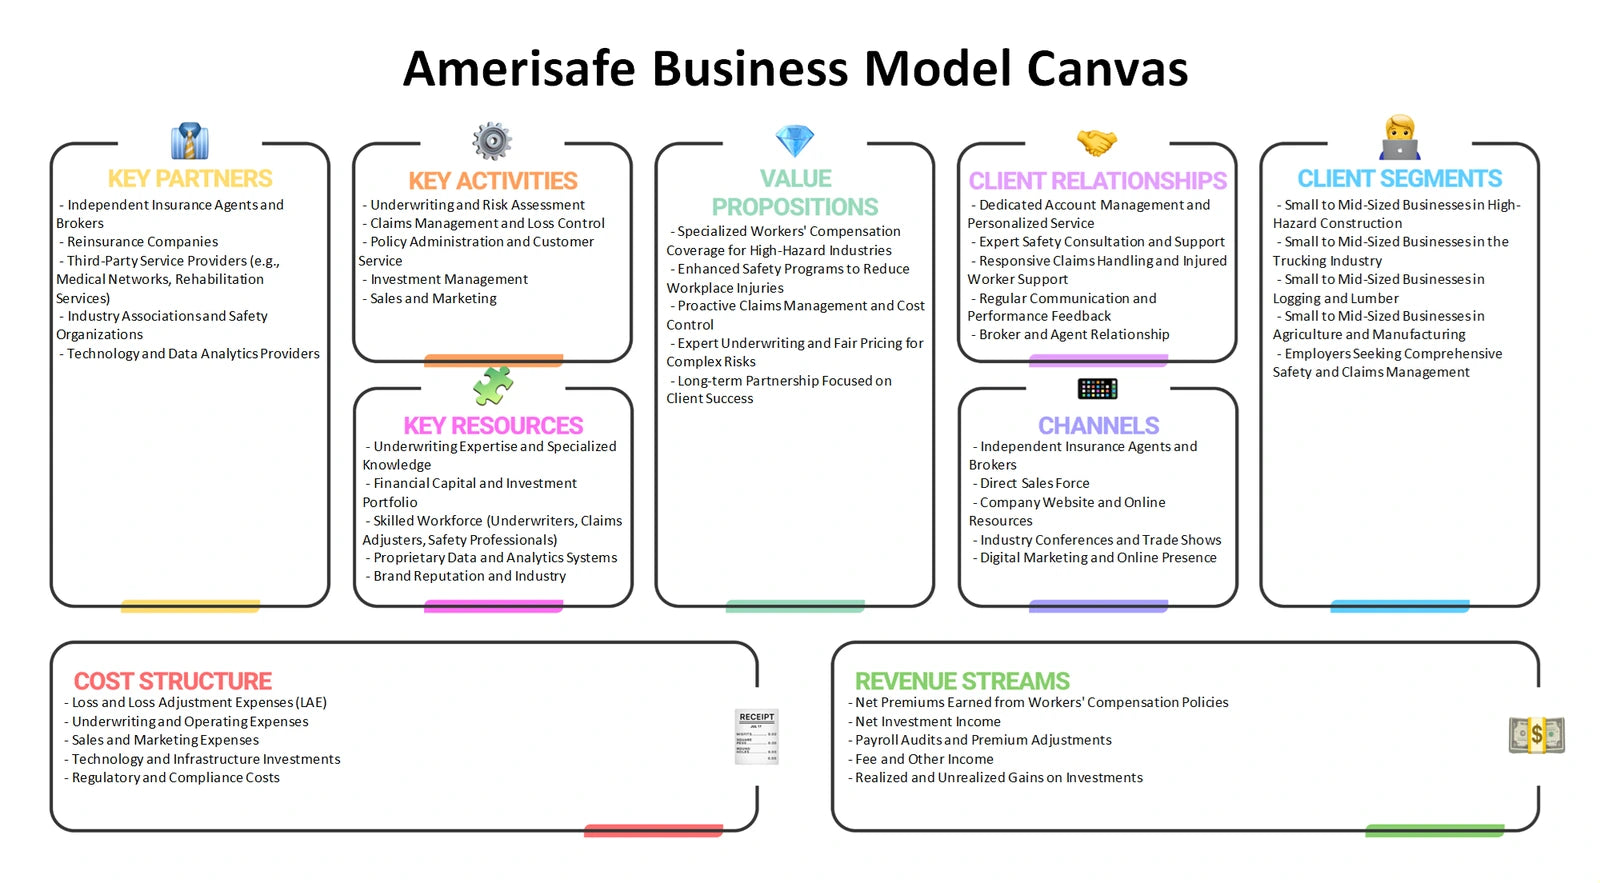
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect pricing discipline, channel access and returns in specialized workers’ compensation?
Amerisafe Porter's Five Forces examines the competitive setting around workers’ compensation insurance without assigning unsupported force scores. Rivalry can influence underwriting terms and retention; buyer power can arise through insured employers, brokers and the availability of alternative carriers. Supplier power is relevant where reinsurance capacity, specialist talent, data and service providers affect the ability to write risk. The review also considers potential entrants with capital or niche expertise, plus substitutes such as self-insurance, captives, risk-retention arrangements or changed workforce practices that reduce the need for conventional cover.
- Competitive discipline. Consider how a specialist position may be tested when insurers compete for accounts that fit desired risk profiles.
- Intermediary influence. Examine how agents and brokers can shape customer choice, information flow and the cost of reaching suitable employers.
- Pressure testing. Use Excel to compare evidence and assumptions across the five forces, with the Word analysis providing context for each insurance-market pressure.
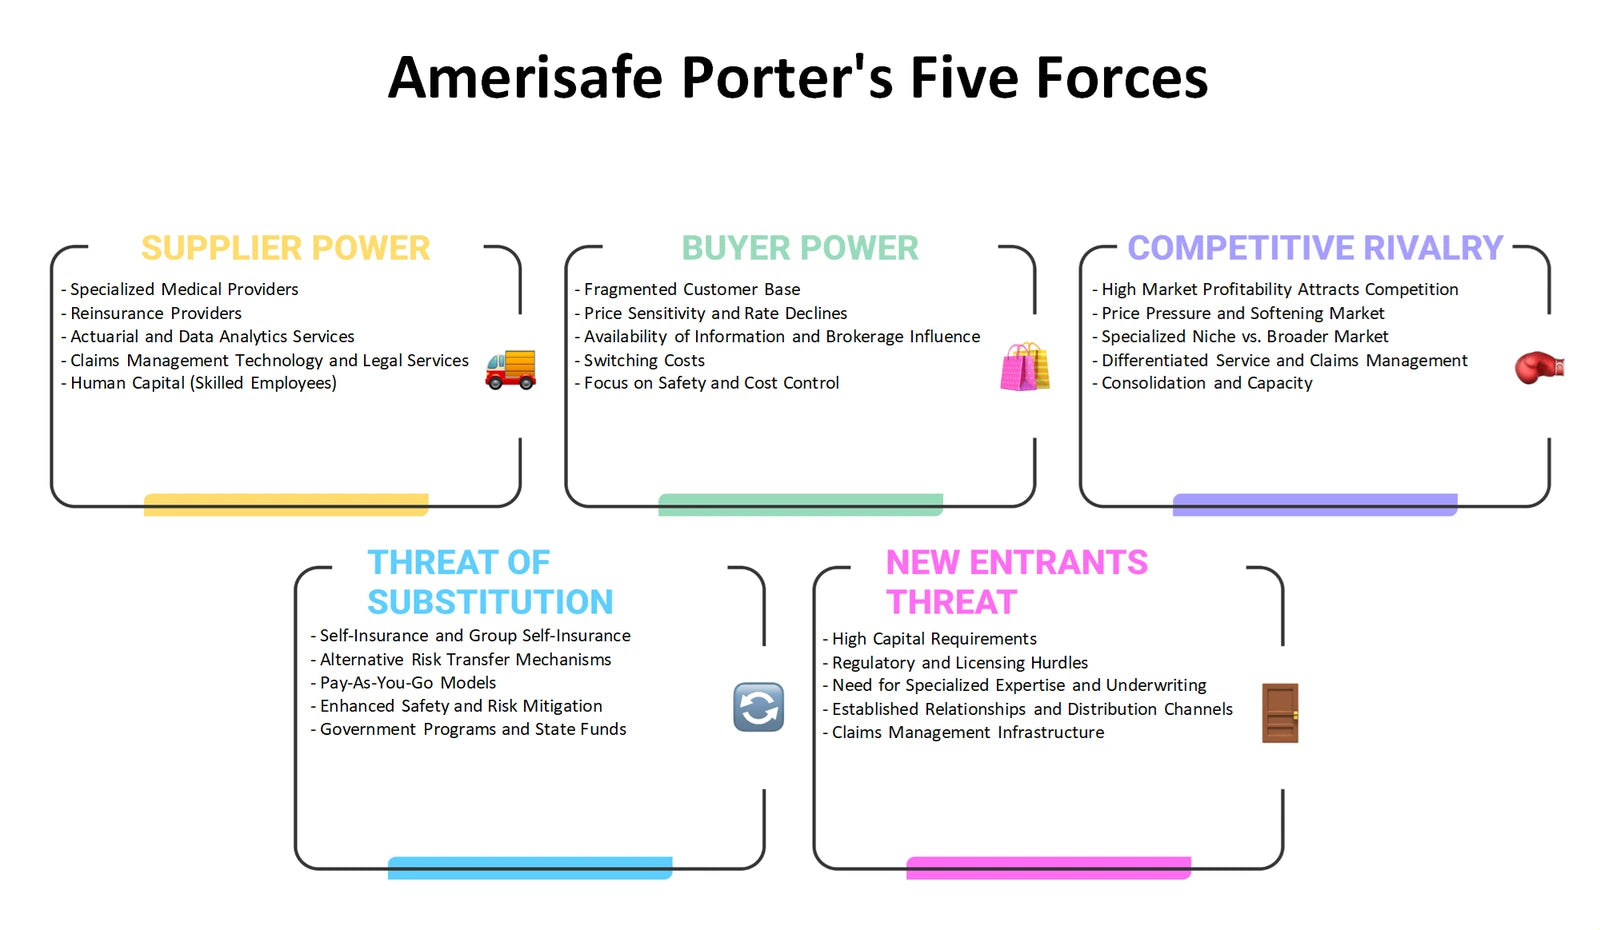
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should a specialist workers’ compensation insurer align its offer, underwriting price, intermediary access and market communication?
The Amerisafe Marketing Mix considers Product, Price, Place and Promotion in a regulated B2B insurance context. Product analysis focuses on the coverage and service proposition relevant to higher-hazard employers, rather than treating insurance as a uniform commodity. Price concerns the logic of risk-based underwriting, loss experience, policy terms and capacity constraints, not an invented premium level. Place evaluates agent and broker routes to appropriate small and mid-sized businesses. Promotion addresses how a specialist insurer can communicate expertise, appetite and service relevance to intermediaries and prospective policyholders without assuming specific campaigns or channel shares.
- Offer fit. Explore whether coverage features and service expectations correspond to the operational realities of high-risk occupations.
- Channel coherence. Compare the role of broker and agent relationships with direct communication needs throughout the policyholder journey.
- Decision worksheet. Use the Excel structure to align the four Ps, then consult the Word analysis for company-specific questions that can guide review of positioning choices.
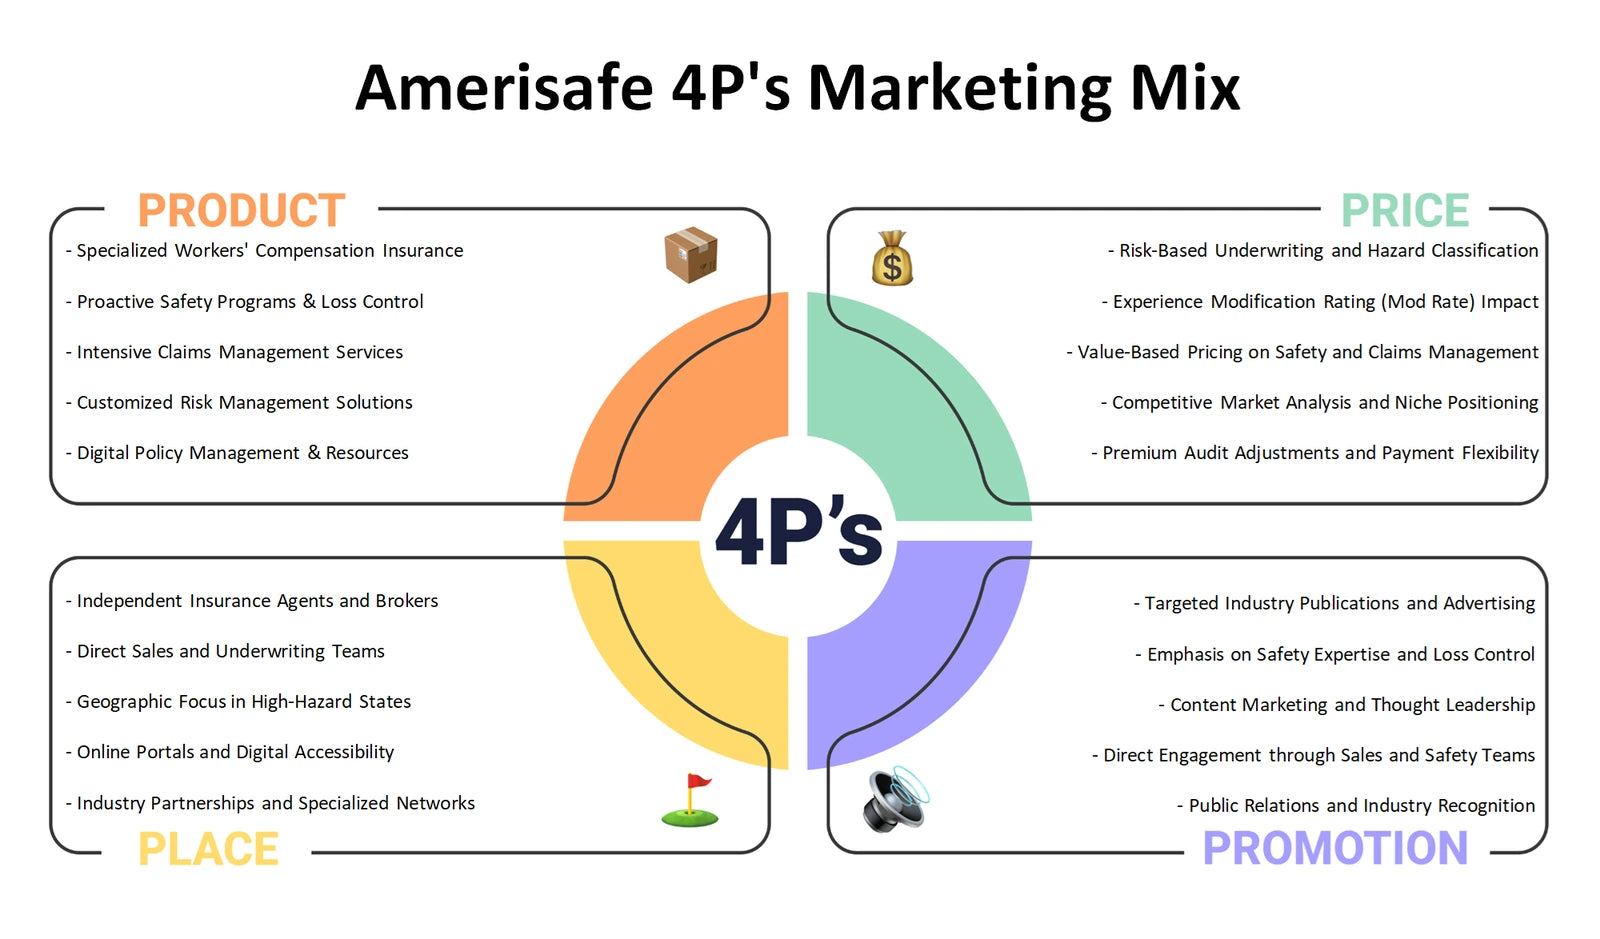
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could reshape workers’ compensation demand, claims severity, capital conditions or compliance needs?
The Amerisafe PESTLE analysis, also commonly called PESTEL, separates external conditions from internal capabilities. Political and Legal factors can include workers’ compensation regulation, insurance supervision and policy uncertainty. Economic conditions may affect payrolls, employment levels, business formation and investment income assumptions. Social factors can include workplace safety expectations and labor patterns, while Technological change raises questions about underwriting data, claims processes and cyber resilience. Environmental conditions matter where severe weather, climate-related workplace disruption or hazardous operating environments may affect insured exposures. These are analytical areas to monitor, not claims that a particular change has occurred.
- Regulatory horizon. Track how jurisdictional rules and compliance expectations may influence coverage design, claims handling and operating requirements.
- Exposure signals. Relate employment, safety, technology and environmental developments to potential shifts in frequency, severity or customer needs.
- Monitoring framework. Use the Excel categories to log external signals and employ the Word analysis to distinguish relevant strategic questions from documented company facts.
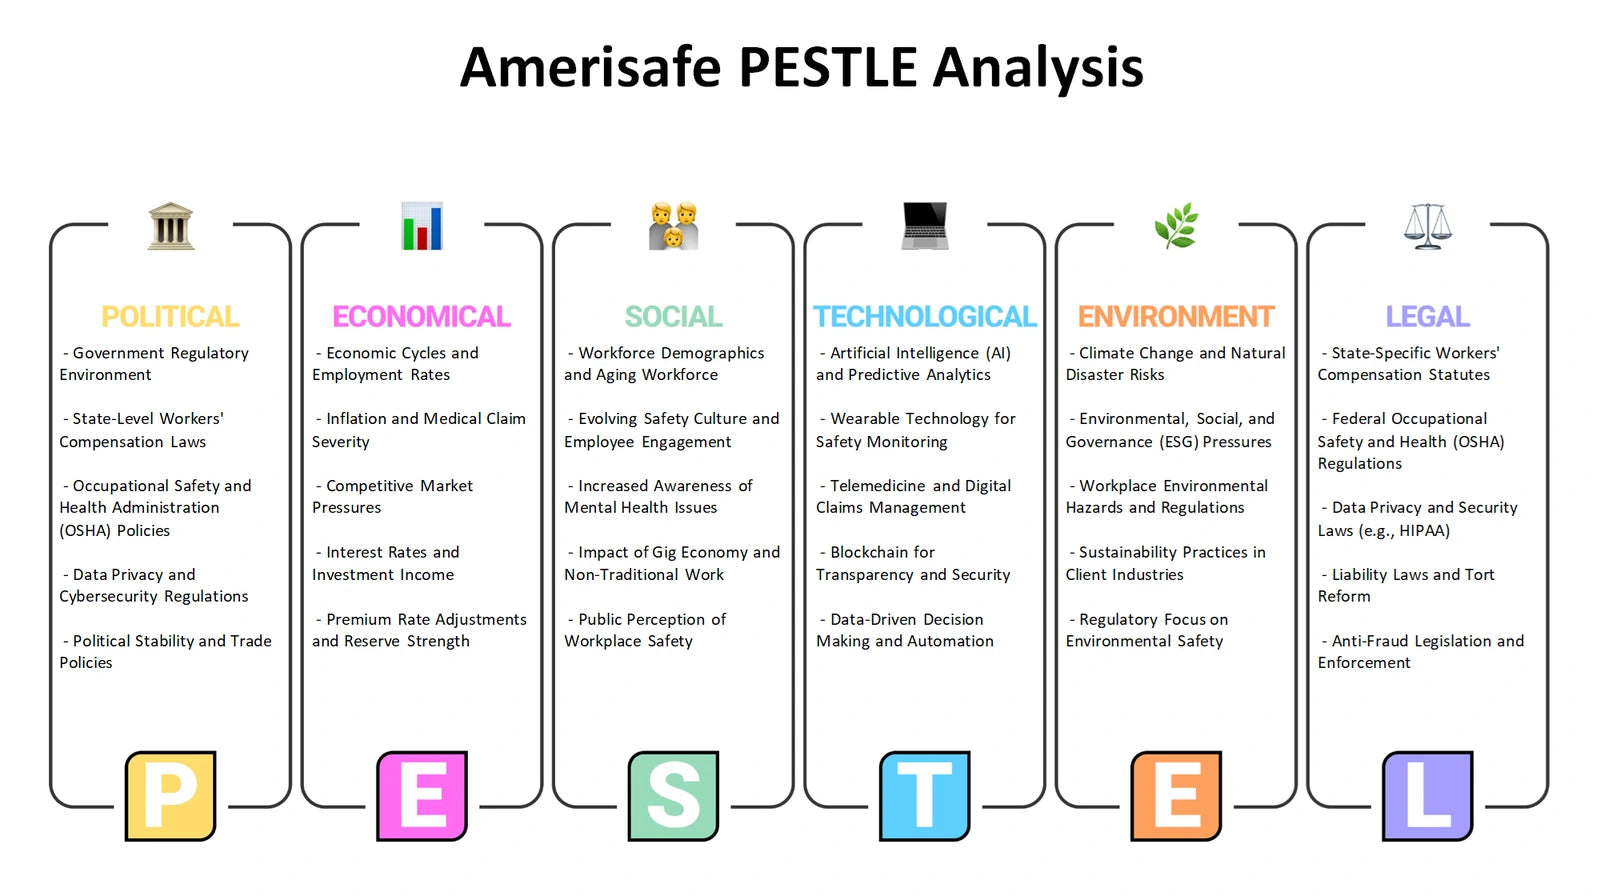
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal specialist capabilities and constraints be weighed against changing opportunities and external threats?
The Amerisafe SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. It offers a disciplined way to consider potential internal advantages such as experience in specialized workers’ compensation, relationships with distribution partners or risk-transfer capability, while testing possible constraints such as concentration in higher-hazard exposures or dependence on intermediary access. Opportunities and threats sit outside the company: changing employer needs, market-cycle conditions, regulation, new competitors, alternative risk financing and claims volatility. The framework does not present these themes as established findings; it helps a buyer evaluate what evidence would support each classification.
- Internal clarity. Distinguish operational capabilities, underwriting resources and partnership dependencies from conditions the company cannot directly control.
- Strategic fit. Explore whether external opportunities can be pursued without weakening risk selection, capital discipline or service quality.
- Actionable synthesis. Use the Excel matrix to prioritize evidence and discussion points, then use the Word analysis to connect them to business-model and market context.
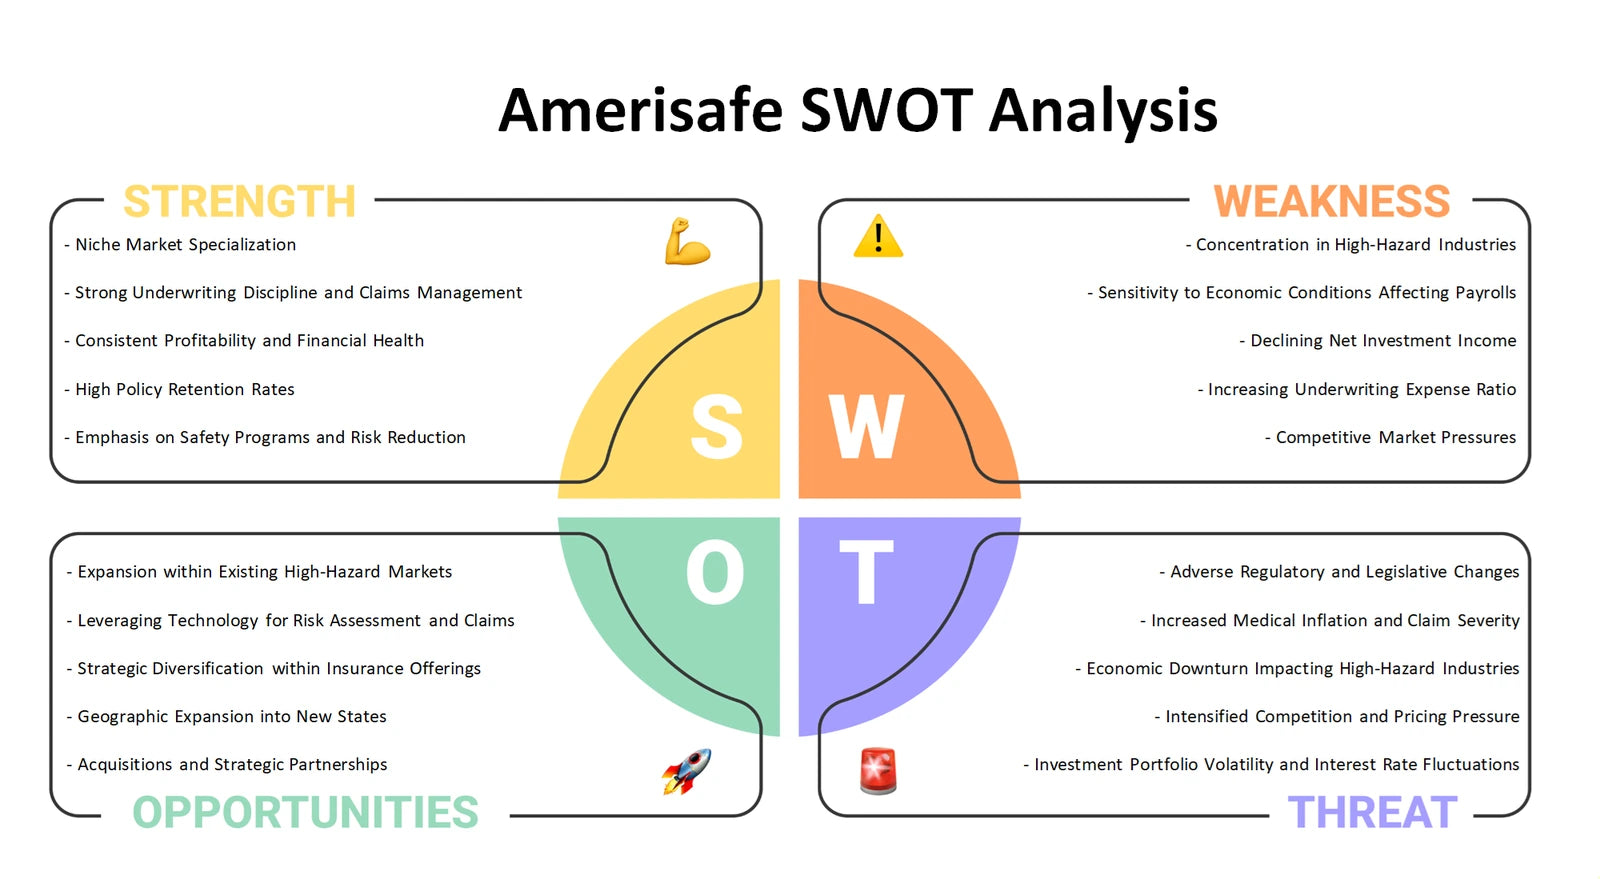
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect underwriting choices with the wider strategic picture
Together, the six perspectives move from portfolio priorities and business-model economics to industry structure, customer routes, external change and strategic fit. The Excel frameworks provide organized spaces for comparison and discussion, while the detailed Word analysis helps put Amerisafe’s specialist workers’ compensation context, broker distribution and reinsurance considerations into a connected strategic view.
Company background: Amerisafe — SEC company submissions profile.