

AIG: Distribution and Customer Acquisition – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
AIG Strategy Analysis Bundle
This bundle is scoped to the AIG insurance business described in the supplied product context: an insurer serving complex risk placements through broker and agent relationships, while using reinsurance to manage large and catastrophic exposures. Its commercial logic depends on evaluating risk carefully, offering coverage that clients and intermediaries can place with confidence, and maintaining capacity when losses are volatile.
The available context highlights the importance of broker distribution, global and regional reinsurance partners, capital efficiency and loss absorption. Those documented themes make useful starting points for questions about portfolio priorities, customer value, distribution economics and external risk. The Excel frameworks and detailed Word analysis help turn those questions into a structured view rather than treating them as isolated insurance issues.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which AIG insurance activities warrant capacity, investment and management attention when growth prospects and relative market share differ?
An AIG BCG Matrix provides a disciplined way to compare a portfolio of insurance products, customer groups or distribution-led businesses using market growth and relative market share. The familiar Stars, Cash Cows, Question Marks and Dogs are analytical categories, not conclusions about any AIG unit. For an insurer, the exercise matters because high-growth opportunities can consume underwriting talent, technology investment, reinsurance capacity and capital, while mature activities may support stability but still require careful risk selection. It helps separate growth ambition from the economics and risk appetite needed to support it.
- Portfolio comparison. Review possible product and market areas against relative competitive position and the growth of the risk markets they serve.
- Capital discipline. Consider where underwriting capacity and reinsurance support may be most valuable instead of assuming all premium growth deserves equal resources.
- Structured review. Use the Excel matrix to map alternative assumptions, then use the Word analysis to document the strategic rationale and questions behind each position.
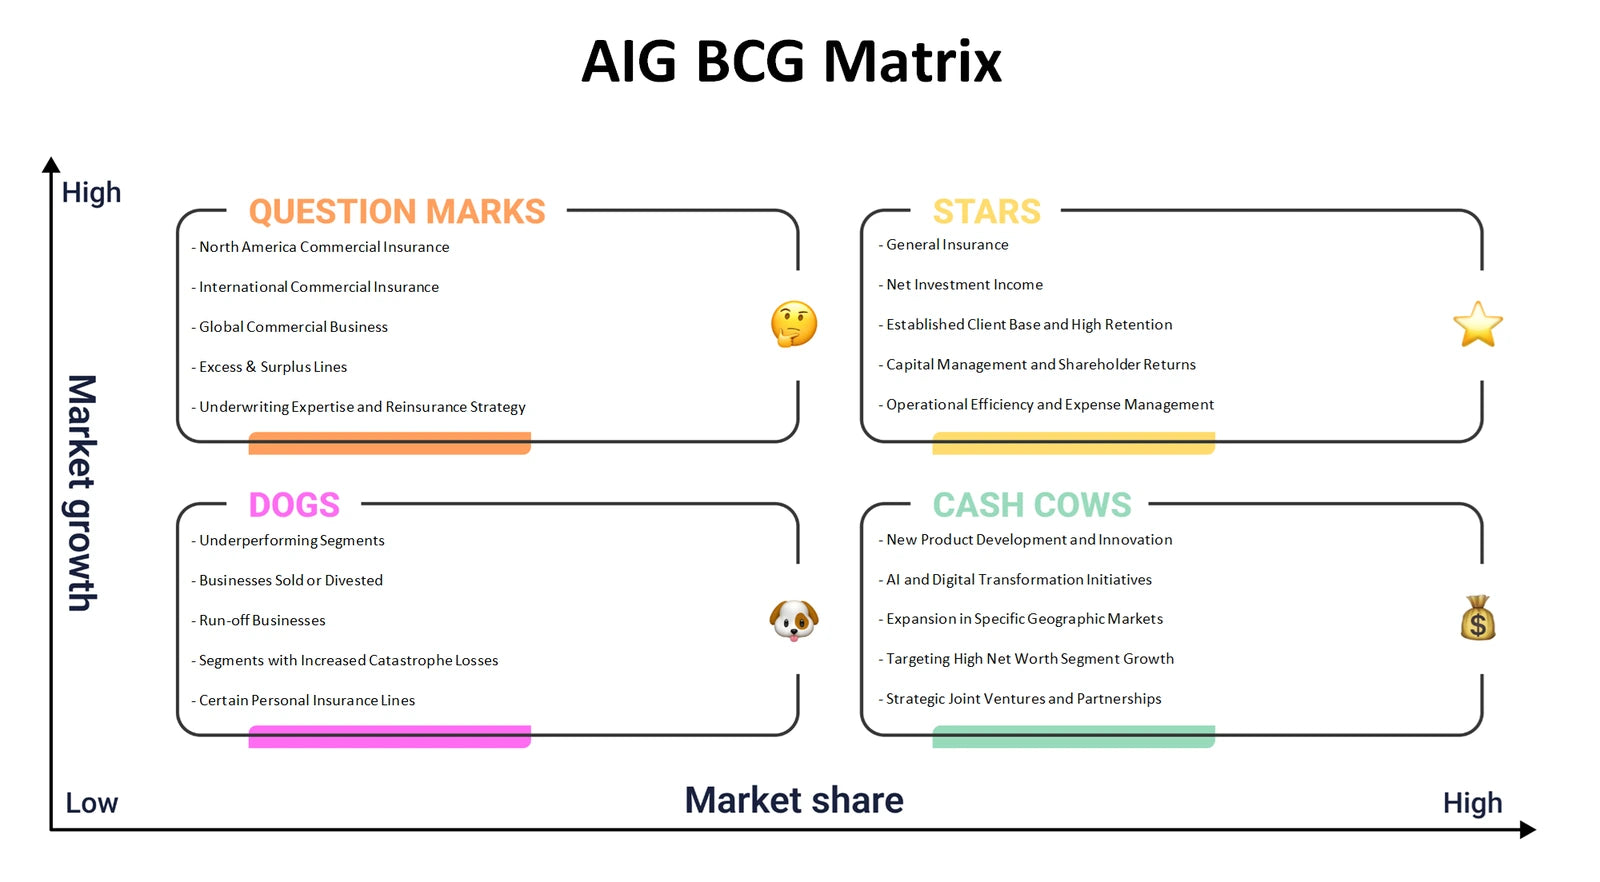
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do AIG's customer relationships, broker-led access and reinsurance partnerships connect to value creation and insurance economics?
The AIG Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In this insurance context, it helps examine how clients with complex exposures receive coverage and service through brokers and agents; how relationships with intermediaries influence placement and retention; and how underwriting, claims capability, capital, risk expertise and reinsurance support delivery. Revenue streams and cost structure can then be considered alongside the cost of risk transfer, distribution, operations and losses, rather than as disconnected financial lines.
- Value chain links. Trace how risk expertise, distribution access and reinsurance capacity may support a proposition for clients needing tailored or high-limit protection.
- Economic dependencies. Examine how channels, relationships, key activities and partnerships affect premiums, acquisition costs, claims obligations and capital use.
- Model mapping. Populate the Excel canvas as a connected operating map and use the Word analysis to explain the trade-offs between service, capacity, partnership reliance and profitability.
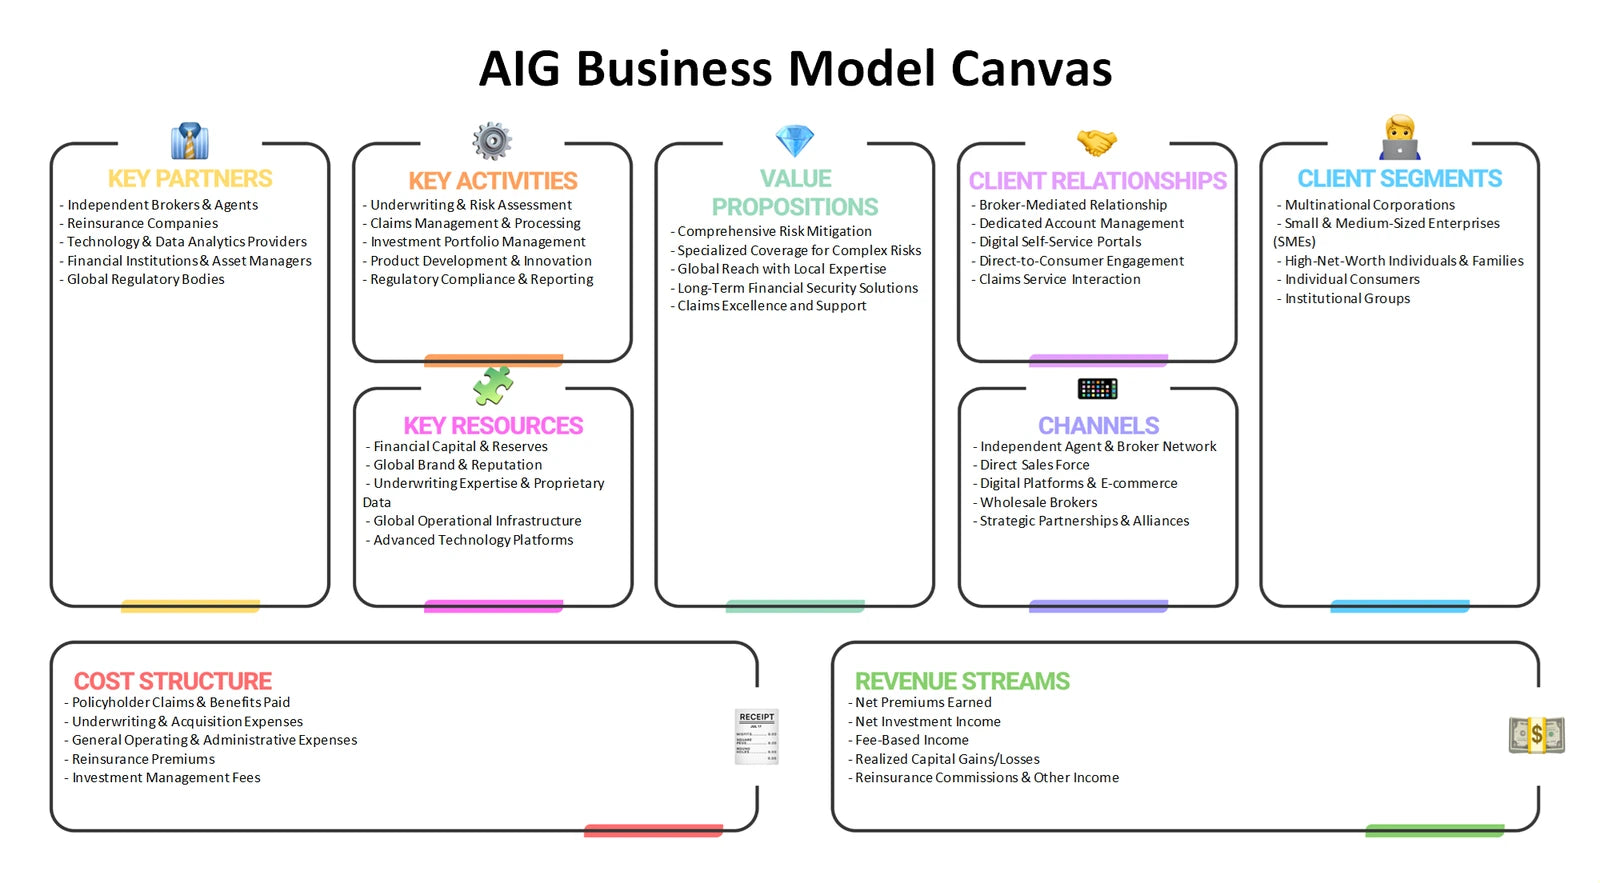
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape the attractiveness and bargaining dynamics of the insurance markets in which AIG seeks to place risk?
AIG Porter's Five Forces analysis examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes in relevant insurance markets. Rivalry can include competition for desirable risks, specialist expertise and broker attention. Buyer power may vary by the size, sophistication and alternatives available to insured clients, while broker influence can affect access and negotiation even where the broker is not the policy buyer. Reinsurers are important suppliers of risk capacity in the supplied context, so their pricing, terms and willingness to cover peak-loss layers can affect underwriting choices. Substitutes may include self-insurance, captives, contractual risk transfer or other ways clients finance exposures.
- Negotiating leverage. Assess where brokers, clients and reinsurers may influence terms, service expectations, capacity and the economics of a placement.
- Alternative protection. Compare insurance demand with other risk-financing approaches rather than treating only direct insurers as substitutes.
- Evidence trail. Use the Excel force-by-force structure to record observations and use the Word analysis to interpret how the forces could affect market selection and underwriting discipline.
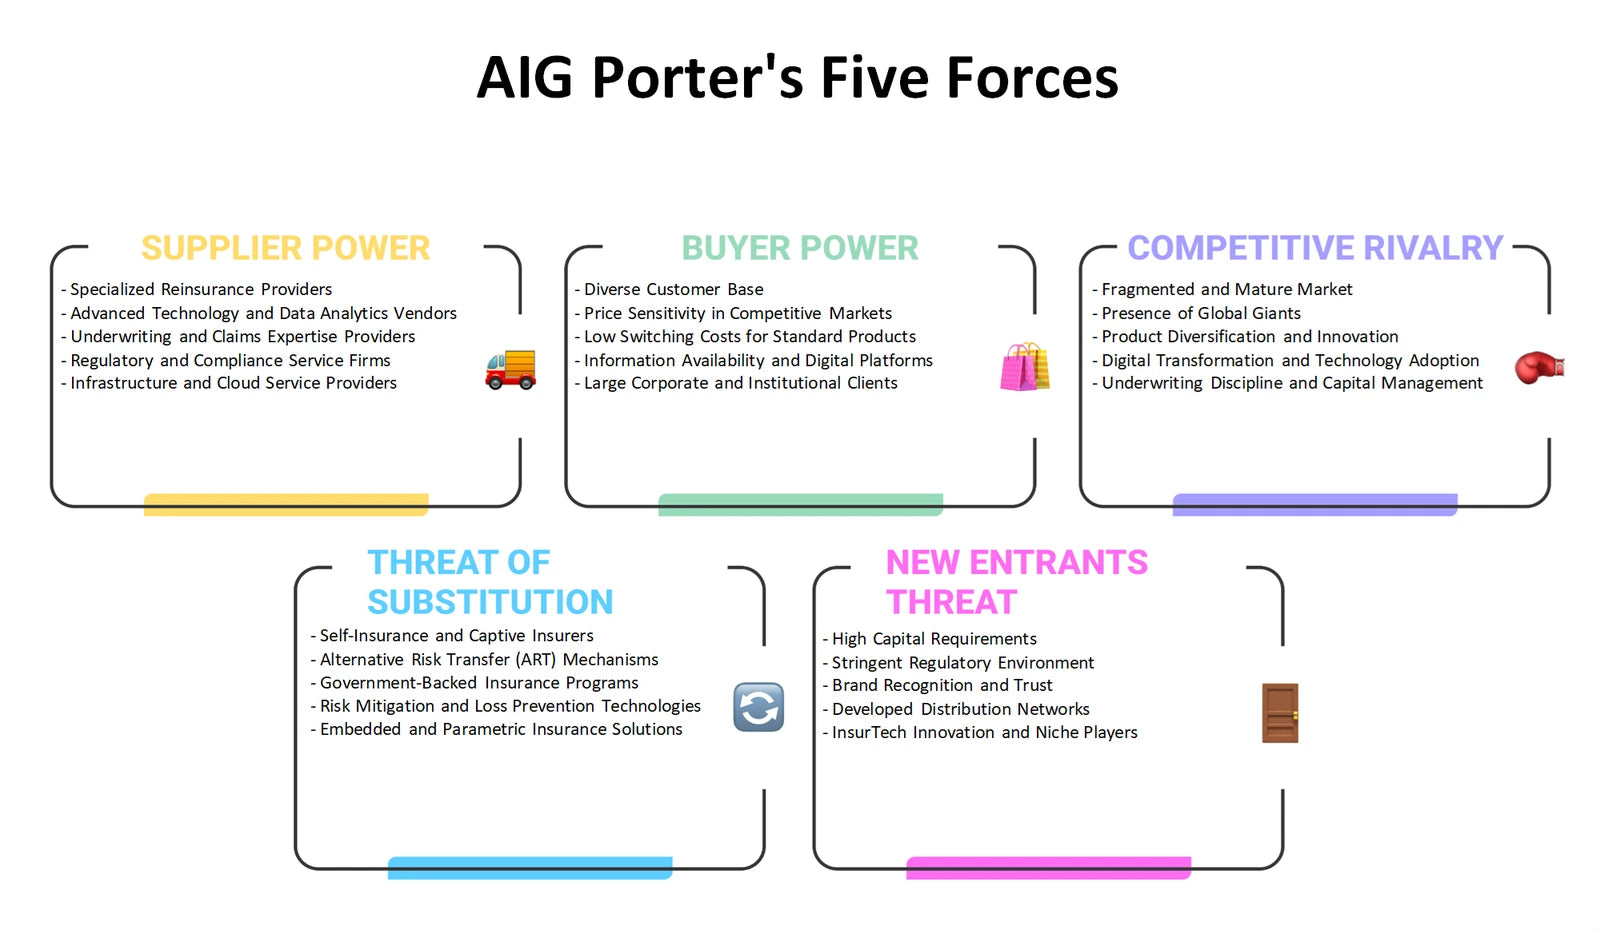
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can AIG align insurance offerings, pricing logic, distribution routes and market communication with the needs of complex-risk customers?
An AIG Marketing Mix considers Product, Price, Place and Promotion in a relationship-led, regulated insurance setting. Product analysis can examine the coverage, limits, service support and risk-transfer design relevant to complex or catastrophic exposures. Price is not simply a sticker price: it can reflect expected loss, limits, deductibles, reinsurance costs, capital requirements and the value of risk expertise. Place focuses on broker and agent routes to market, where trusted intermediary relationships can shape deal flow and client fit. Promotion concerns how proposition, expertise and service standards are communicated to brokers and insureds without assuming any particular campaign or channel share.
- Offering fit. Compare potential coverage and service propositions with the risks, buying processes and placement requirements of target customer groups.
- Distribution logic. Explore how broker and agent relationships can influence market intelligence, product feedback, cross-sell opportunities and retention.
- Go-to-market planning. Use the Excel 4Ps framework to organize choices and use the Word analysis to connect each choice to insurance economics, customer trust and intermediary execution.
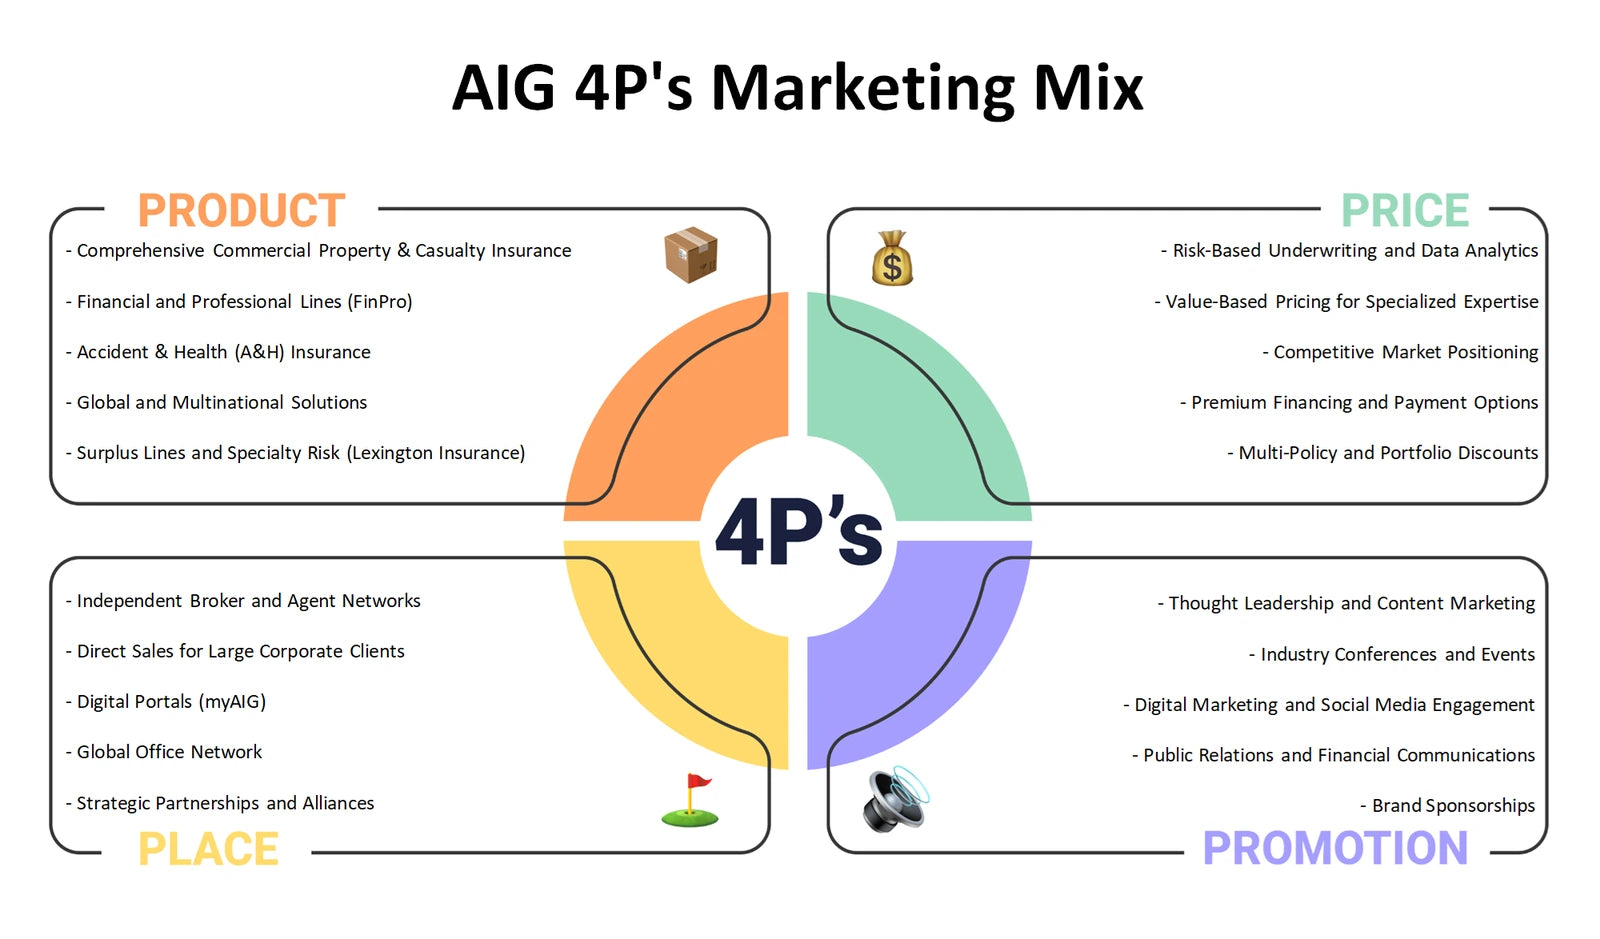
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external forces could change the demand, regulation, pricing assumptions and risk capacity relevant to AIG?
An AIG PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences on an insurer. Political and legal factors raise questions about supervisory requirements, insurance regulation and cross-border operating conditions. Economic conditions can affect customer budgets, claims inflation, investment conditions and the affordability of coverage. Social changes may alter risk awareness and service expectations, while technology creates both new distribution or underwriting possibilities and cyber, data and operational exposures. Environmental conditions are particularly relevant when catastrophe risk, loss accumulation and resilience shape the availability and cost of protection. These are questions for analysis, not claims that a specific policy or rate change has occurred.
- External scan. Distinguish broad macro drivers from the specific transmission paths through which they could affect insurance demand, losses, regulation or reinsurance.
- Risk horizons. Consider whether a factor is an immediate operating issue, a medium-term market change or a longer-term exposure-management challenge.
- Scenario organization. Use the Excel framework to group and prioritize external signals, then use the Word analysis to explain why selected scenarios matter for capacity, customers and strategy.
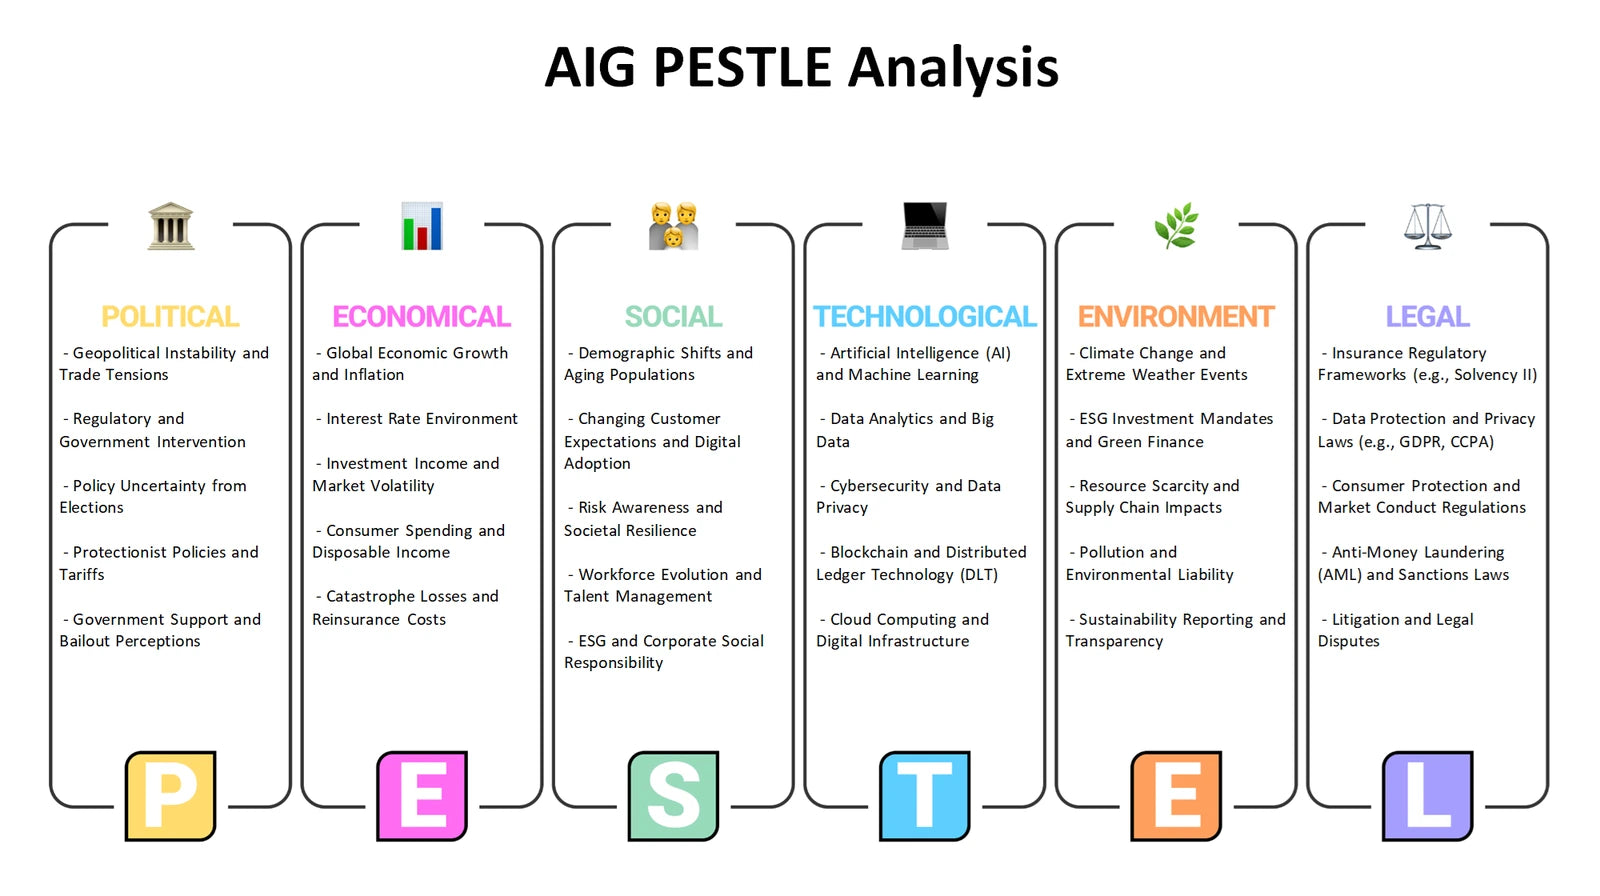
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can AIG distinguish internal capabilities and constraints from external opportunities and threats in a volatile insurance environment?
An AIG SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. The supplied context makes reinsurance relationships, broker and agent connections, complex-placement knowledge and the ability to manage peak-loss layers relevant topics to assess as possible capabilities; it does not establish them as scored strengths. Potential internal constraints may concern concentration, cost, execution complexity or reliance on partners. Opportunities and threats belong outside the organization: changing client risk needs, new forms of exposure, competitive conditions, regulation, catastrophe severity and alternative risk-financing choices can all be examined in that category. Keeping the distinction clear prevents a broad market condition from being mislabeled as an internal weakness.
- Classification discipline. Test whether each factor is controlled internally or arises in the market, regulatory environment, customer base or risk landscape.
- Strategic fit. Explore how a capability such as broker access or reinsurance design could be matched to an external opportunity while reducing exposure to a threat.
- Decision record. Use the Excel SWOT grid to compare factors transparently and use the Word analysis to capture assumptions, implications and possible strategic responses.
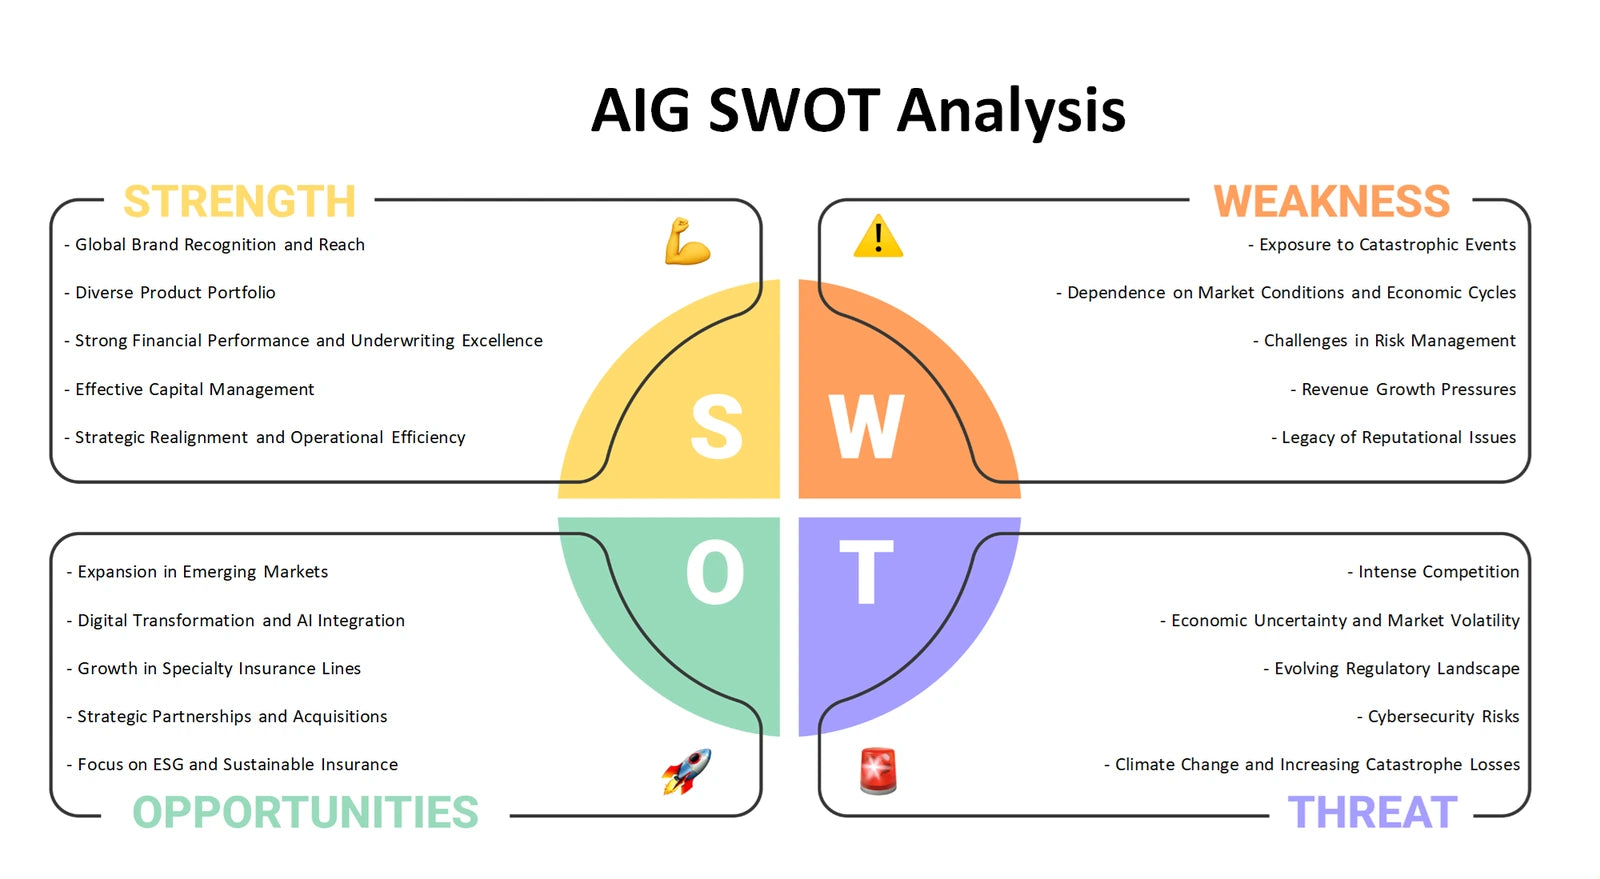
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with insurance-market realities
Together, the six perspectives allow customers to move from portfolio questions to business-model logic, industry bargaining power, market execution, external change and strategic priorities. The Excel materials provide structured places to compare inputs and organize discussion, while the detailed Word analysis supports interpretation of AIG's broker relationships, reinsurance context, risk capacity and complex-insurance business considerations. Used together, they can help develop a more consistent basis for strategic review without treating any framework as a substitute for underwriting, legal or investment judgement.
Company background: AIG — supplied product-context page.