

Affin Bank: Banking Business and Deposit Funding – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Affin Bank Strategy Analysis Bundle
Affin Bank is a Malaysian banking business identified in public company directories. Available business context points to retail, SME and corporate lending, deposit mobilisation, wealth and investment advice, and protection solutions distributed through bancassurance and bancatakaful relationships. This makes its strategy relevant to customers balancing everyday banking, financing, savings, investment and Shariah-compliant needs.
The bundle turns that operating context into connected strategic questions: which banking activities warrant resource priority, how lending and fee-based services reinforce the model, and how external banking conditions may alter customer choices or risk. The Excel frameworks provide structured comparison tools, while the Word files support fuller company-focused interpretation without claiming predetermined findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Affin Bank service areas should be examined for investment, protection of earnings, selective development or reduced resource use?
An Affin Bank BCG Matrix helps organise a banking portfolio around two separate criteria: market growth and relative market share. Rather than assigning loans, deposits, wealth advice or protection products to a quadrant without evidence, the framework asks what data would be needed to distinguish Stars, Cash Cows, Question Marks and Dogs. That matters where capital, relationship-manager time, technology budgets and risk appetite cannot be expanded everywhere at once. A mature deposit or lending activity may have different economics from a developing advisory or partner-distributed protection proposition, even when both contribute to customer relationships.
- Portfolio boundaries. Compare relevant activities such as consumer banking, SME finance, corporate lending, deposits, wealth services and protection distribution without treating the bank as one undifferentiated product.
- Capital discipline. Assess how growth potential, relative competitive position, credit exposure and fee contribution could affect resource-priority discussions.
- Structured comparison. Use the Excel matrix to map assumptions and evidence, then use the Word analysis to interpret what each possible quadrant means for banking portfolio choices.
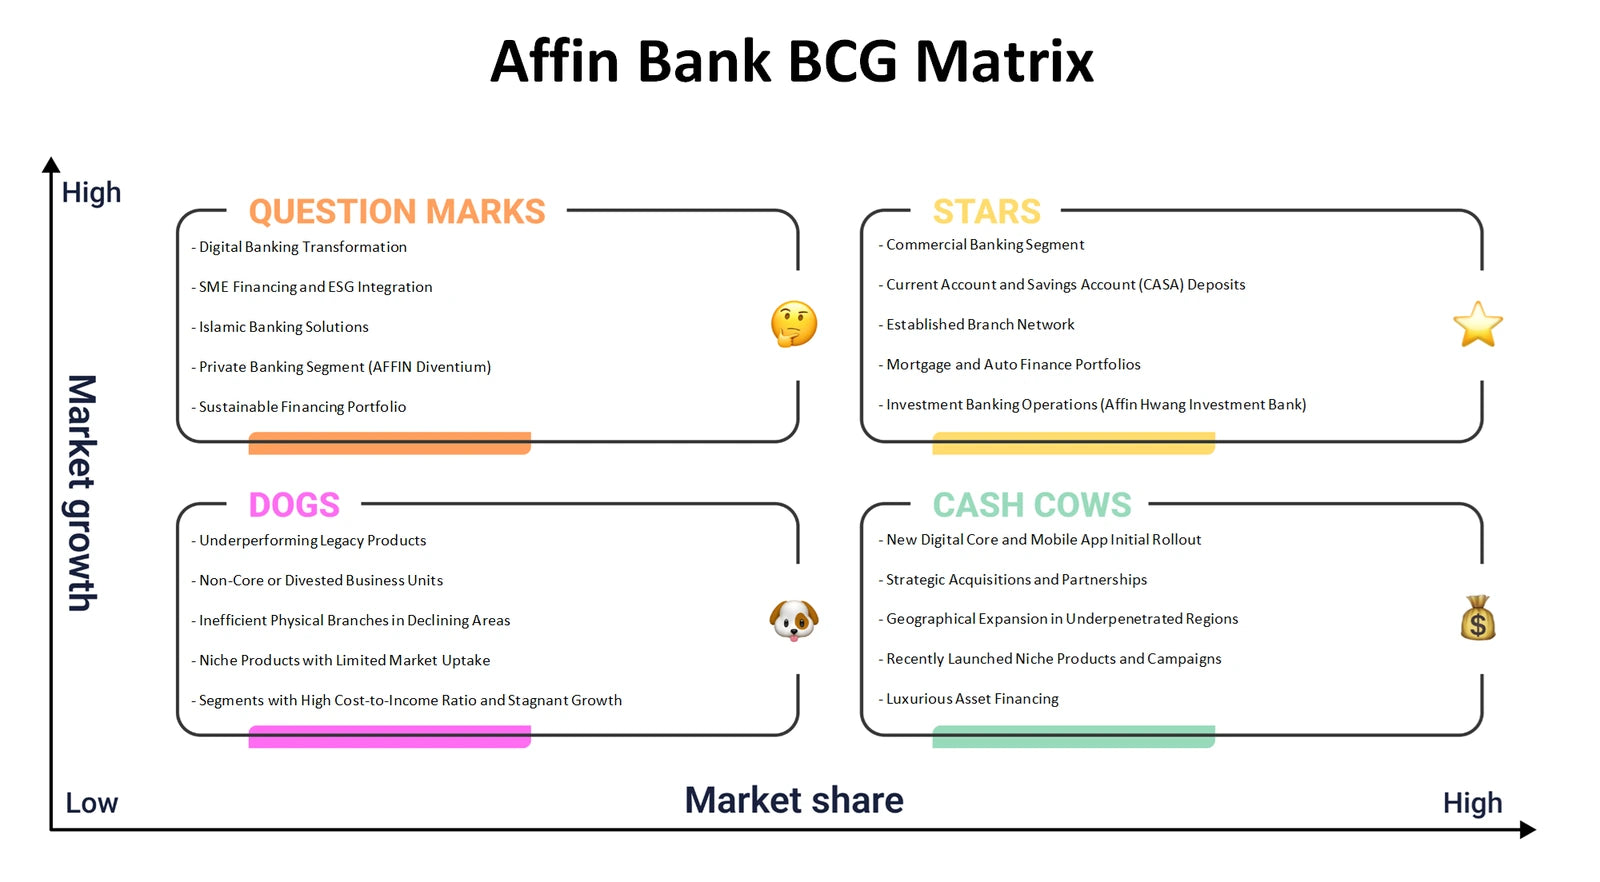
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do Affin Bank's customer relationships, funding activities, lending decisions and partner-led services connect to value creation and economics?
The Affin Bank Business Model Canvas examines the logic linking customer segments, value propositions, channels and customer relationships with revenue streams, key resources, key activities, key partnerships and cost structure. For this banking context, the exercise can connect retail, SME and corporate needs with deposits, financing, advice and protection-related solutions. It also helps distinguish interest-based lending and funding economics from potentially fee-based income generated through wealth or protection distribution. Partnerships may broaden client propositions, but they also raise questions about integration, governance and the division of value between parties. The Canvas is useful because it makes these interdependencies visible rather than considering each product in isolation.
- Customer-value fit. Examine how financing, deposits, advisory and protection offerings may address different financial needs across conventional and Shariah-compliant client segments.
- Economic connections. Trace how funding, credit assessment, relationship management, digital or physical channels and partner arrangements can influence revenues and operating costs.
- Model workshop. Populate the Excel blocks with supported observations, then use the detailed Word analysis to discuss tensions and links across all nine building blocks.
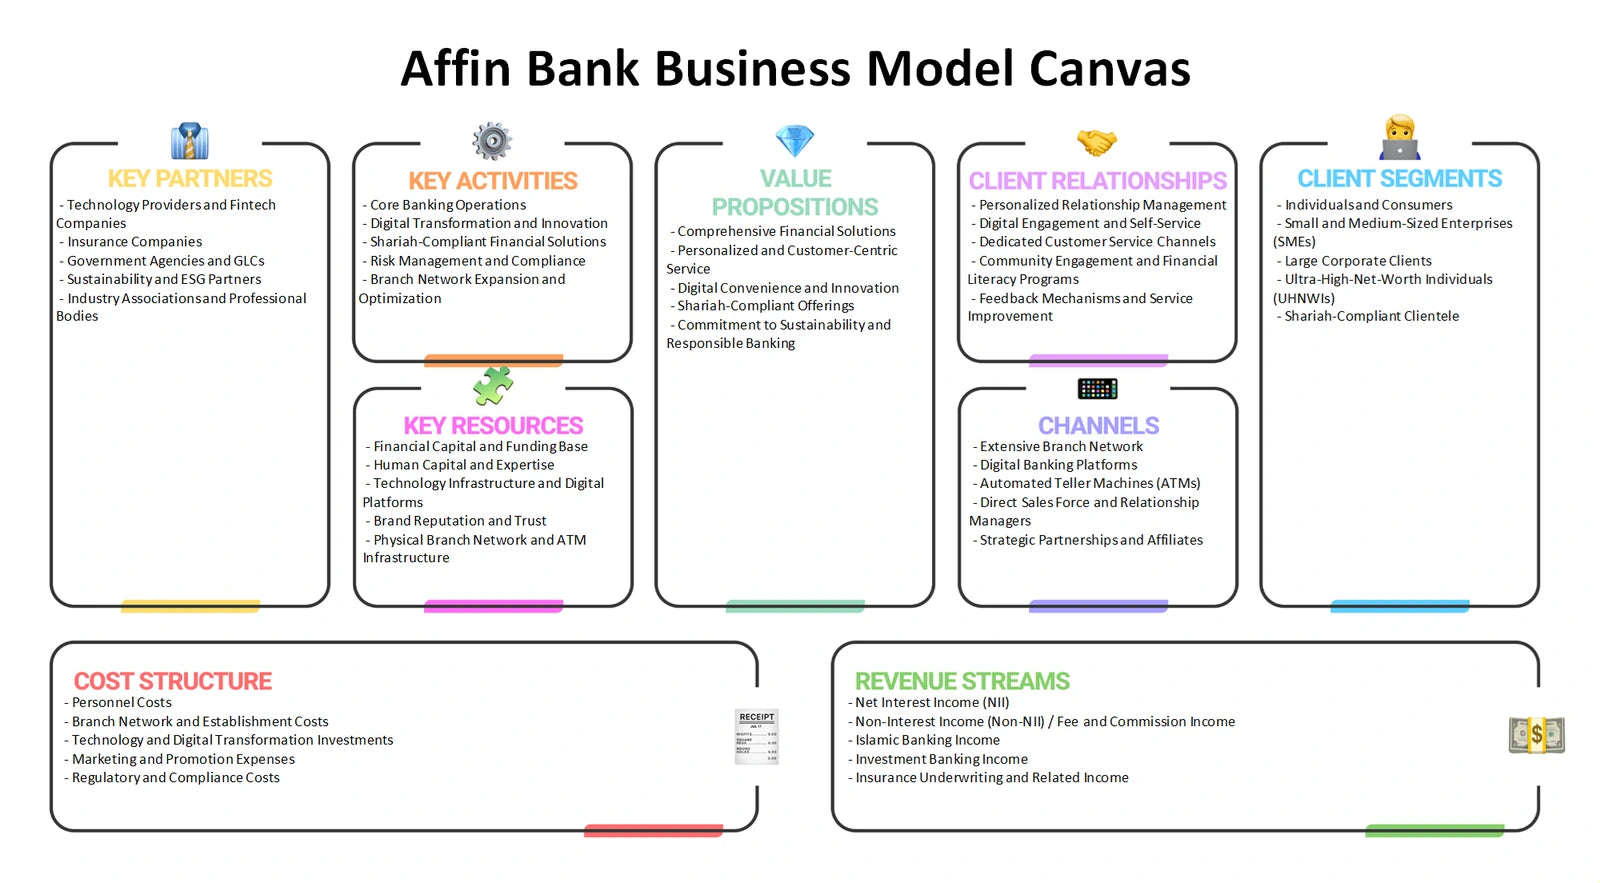
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence Affin Bank's ability to retain customers, manage margins and differentiate its banking proposition?
Affin Bank Porter's Five Forces analysis considers rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes in the Malaysian banking setting. Rivalry can affect deposit gathering, loan pricing, service quality and the pursuit of affluent or business customers. Supplier power is relevant to funding providers, technology vendors, specialist talent and distribution partners. Buyer power considers customers' capacity to compare banking options or move financial relationships. New entrants may include digitally enabled providers, while substitutes extend beyond direct banks to alternative financing, investment, payment or protection routes that meet similar needs. The framework does not claim a force is high or low; it structures the evidence needed to assess pressure.
- Margin pressure. Explore how competition for deposits and creditworthy borrowers may affect pricing flexibility, funding stability and relationship value.
- Alternative solutions. Compare traditional bank services with non-bank ways customers can borrow, save, invest, make payments or obtain protection.
- Evidence-led review. Use the Excel force-by-force layout to record drivers and countermeasures, supported by the Word analysis for banking-specific interpretation.
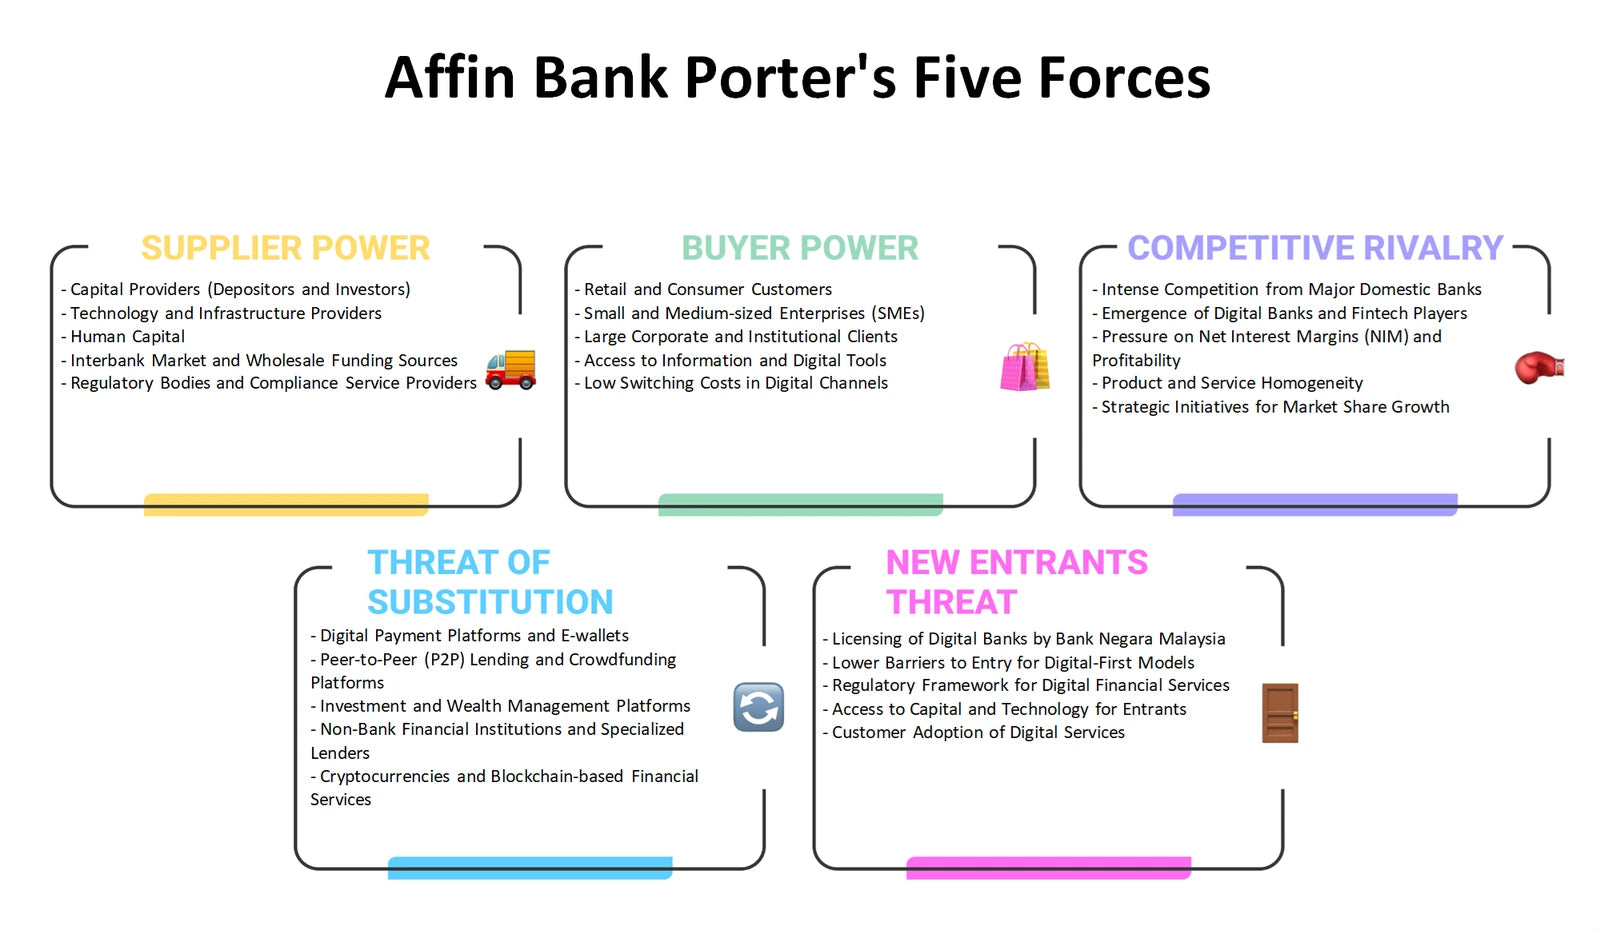
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Affin Bank examine the fit between its service proposition, pricing logic, customer access routes and responsible communication?
An Affin Bank Marketing Mix reviews Product, Price, Place and Promotion in a regulated financial-services environment. Product can include deposit accounts, retail and business financing, wealth advice, investment-related options and protection solutions offered with partners. Price is broader than a headline rate: it can involve deposit returns, financing charges, fees, risk-based terms and the value customers receive from advice or convenience. Place considers branches, relationship managers, digital journeys and partner-enabled distribution. Promotion must communicate benefits clearly while respecting suitability, disclosure and trust requirements. This 4Ps lens helps test whether the route to market matches the complexity of an offering and the needs of each customer group.
- Offer architecture. Compare how product bundles may combine transaction banking, financing, investment guidance and protection for distinct customer situations.
- Channel consistency. Assess whether branch, adviser, digital and partner touchpoints can support discovery, onboarding, service and relationship continuity.
- Planning application. Use the Excel 4Ps structure to organise customer-facing choices, then draw on the Word analysis to consider trade-offs between reach, clarity and service quality.
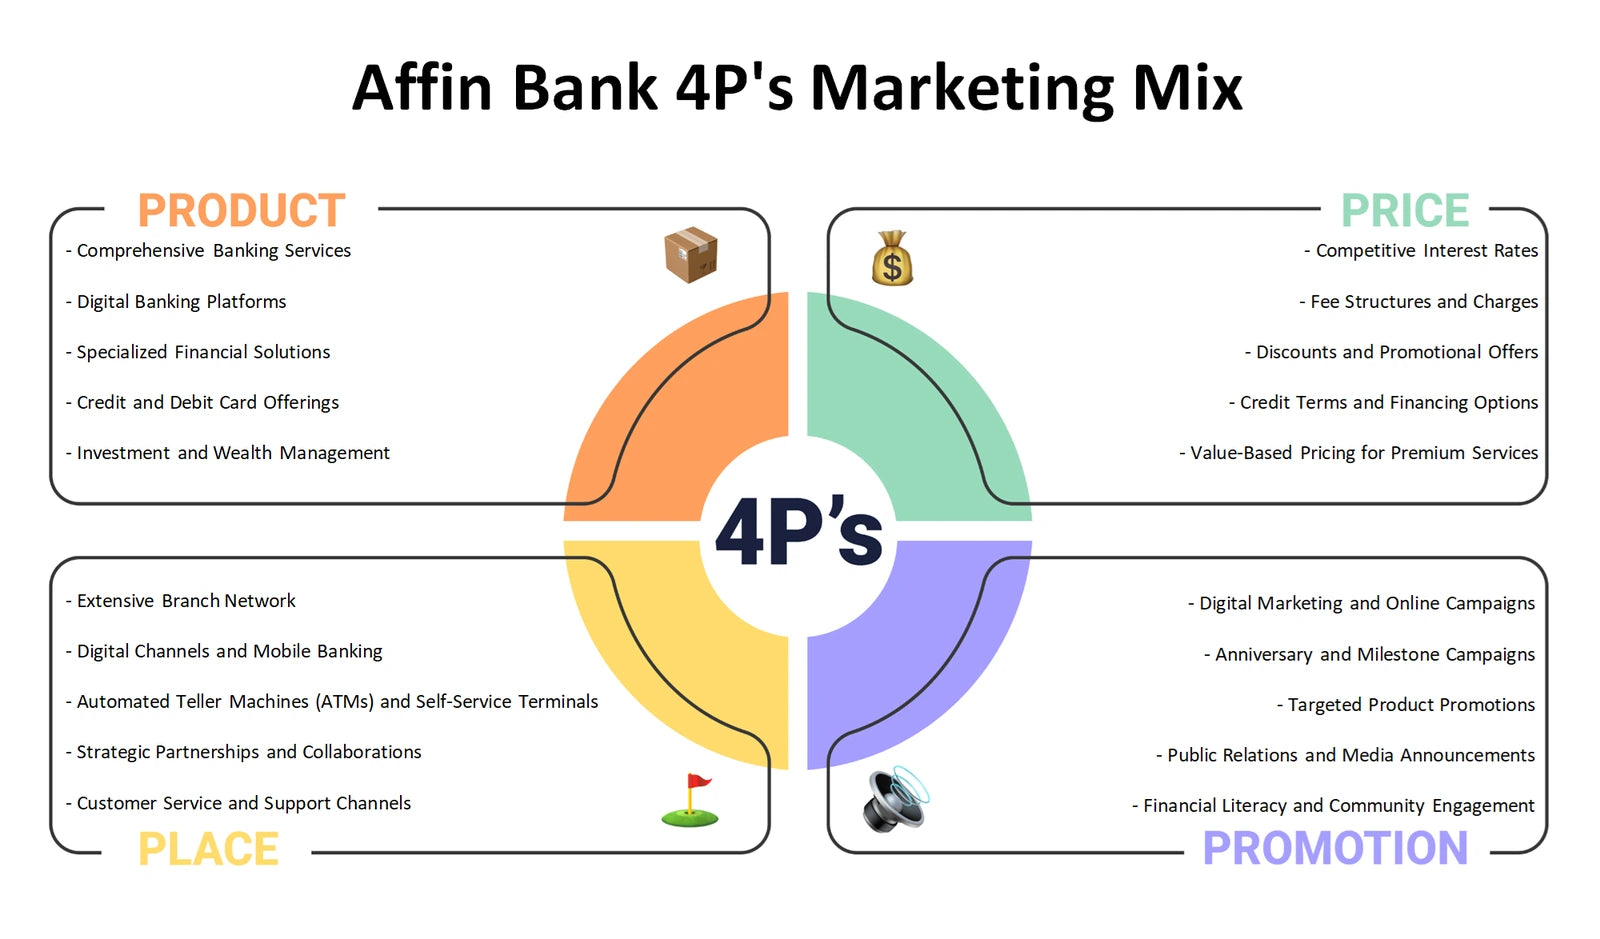
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should Affin Bank monitor when planning lending, funding, customer service and partnership activity in Malaysia?
Affin Bank PESTLE analysis, also commonly called PESTEL analysis, separates Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal considerations can shape banking supervision, consumer protection, disclosure and Shariah-related governance questions. Economic conditions may affect borrowing demand, deposit behaviour, credit quality and funding costs, while social change can influence expectations for convenience, advice and financial inclusion. Technology raises questions around digital service delivery, data security and changing payment habits. Environmental factors can matter through financed-business exposure, operational resilience and stakeholder expectations. The framework should distinguish an external issue to monitor from a verified policy change or current market outcome.
- Macro sensitivities. Identify economic variables that may influence lending appetite, repayment capacity, savings preferences and the balance between yield and risk.
- Operating environment. Consider how regulatory expectations, digital adoption, data responsibilities and environmental concerns could affect banking processes and customer trust.
- Monitoring map. Use the Excel framework to classify signals by PESTLE category and use the Word analysis to relate priority developments to Affin Bank's operating model.
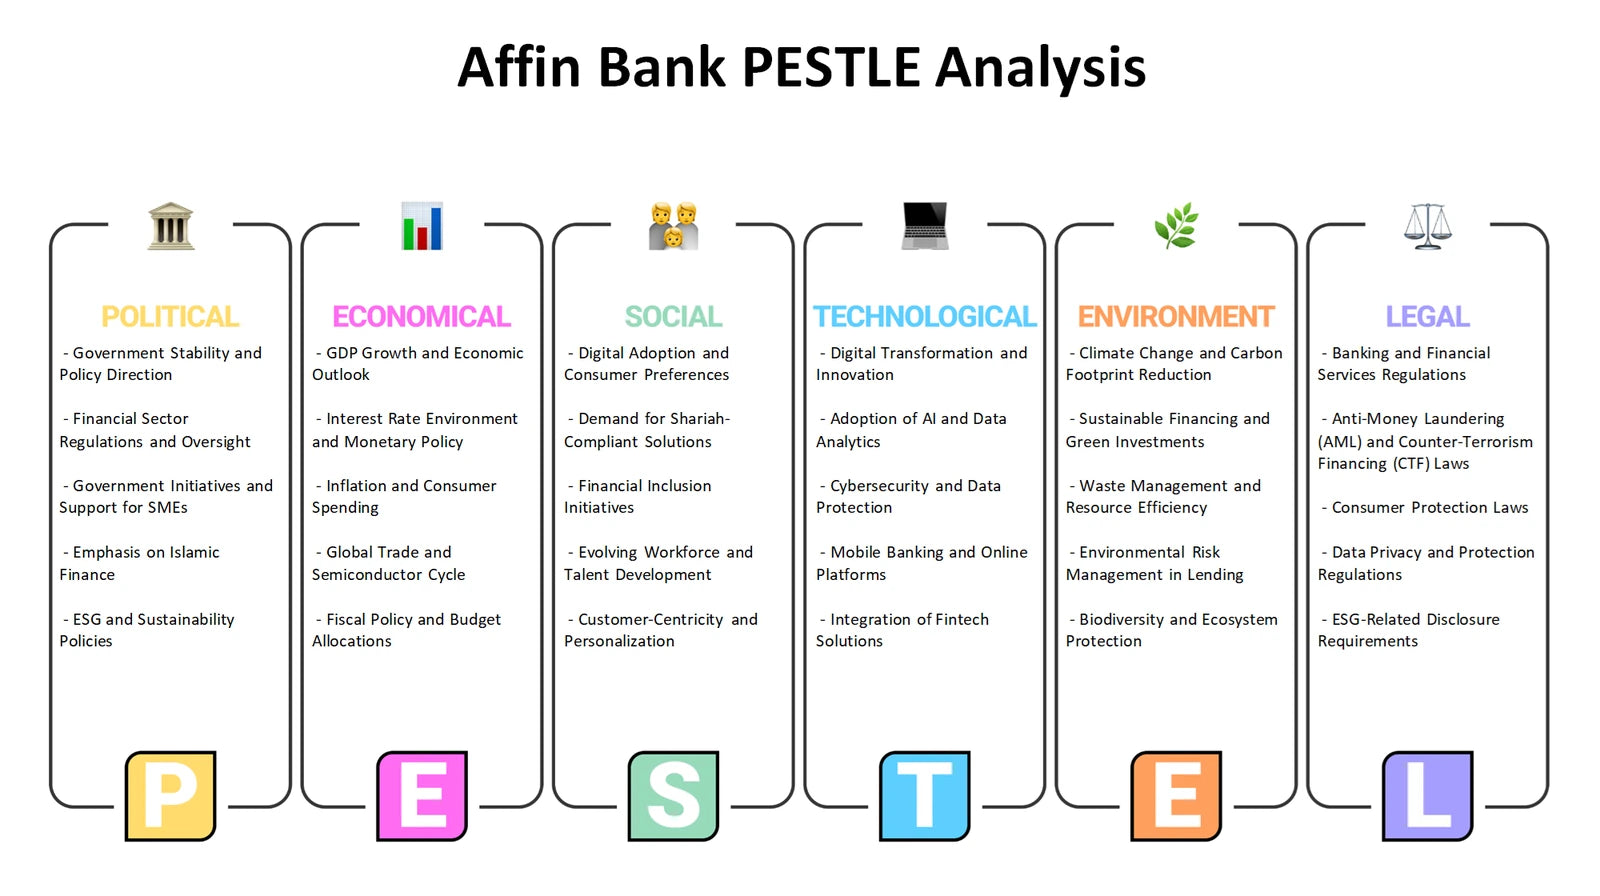
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Affin Bank distinguish internal capabilities and constraints from external opportunities and threats before setting strategic priorities?
An Affin Bank SWOT analysis provides a disciplined distinction between internal Strengths and Weaknesses, and external Opportunities and Threats. Relevant internal topics to assess may include lending and deposit capabilities, credit-risk processes, collateral management, collections, advisory capacity, customer relationships and the ability to work with distribution partners. These are not asserted conclusions; they are areas requiring evidence. External opportunities may arise from changing customer needs for financing, wealth or protection, while threats can include competitive intensity, economic stress, technology disruption or changing regulation. The value of SWOT is in pairing internal realities with the conditions identified through PESTLE and Five Forces, rather than listing generic positives and risks.
- Internal diagnosis. Test which resources, processes and relationships may support service quality, funding resilience, asset quality and cross-service customer engagement.
- External fit. Link potential market openings and threats to specific capabilities or gaps instead of treating them as disconnected observations.
- Priority synthesis. Use the Excel grid to separate evidence by category, then use the Word analysis to turn the resulting combinations into focused discussion points.
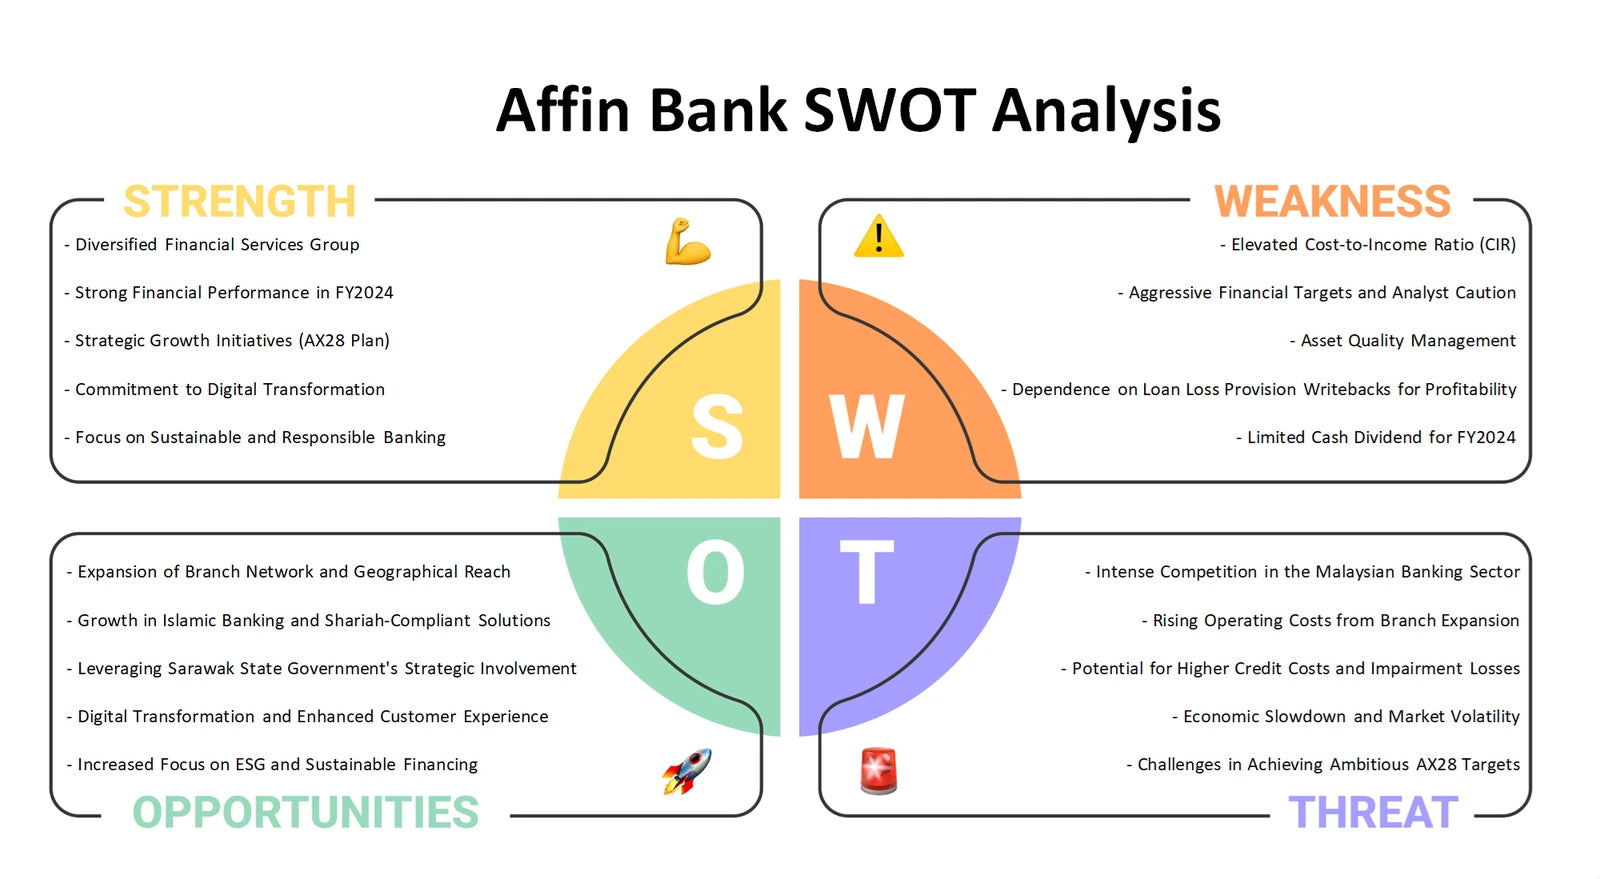
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Affin Bank
Together, the six perspectives move from portfolio questions and business-model economics to industry pressure, customer-facing choices, external conditions and strategic fit. The Excel frameworks help organise comparisons and assumptions, while the detailed Word files help develop a more considered discussion of Affin Bank's lending, funding, advisory, protection and relationship-based banking context.
Company background: Affin Bank — Wikidata entity profile.