

Admiral Group: Licensing and Regulation in Six Frameworks

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Admiral Group Strategy Analysis Bundle
For this bundle, Admiral Group refers to the motor-insurance business described in the supplied product context, rather than an unrelated geographic namesake. The analysis is therefore centred on an insurer serving motorists through insurance propositions, customer billing and claims-related operations, with the customer journey extending from quotation and purchase to renewal, servicing and loss settlement.
The supplied context highlights the importance of reinsurance capacity for absorbing catastrophe and large-loss exposure, alongside banking, payment and regulatory relationships. These are useful starting points for examining portfolio priorities, unit economics, customer acquisition and resilience. The six frameworks organise those questions from different angles; they do not present unverified findings, scores or investment recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance products or customer propositions merit further resource, protection of cash generation, closer testing or possible withdrawal?
An Admiral Group BCG Matrix helps separate a portfolio question from a simple sales question. It compares market growth with relative market share, using the familiar Stars, Cash Cows, Question Marks and Dogs as analytical categories rather than labels already assigned to company activities. For a motor insurer, the comparison can include different propositions, distribution approaches or adjacent customer offers where evidence supports their inclusion. The practical issue is whether underwriting capacity, technology spend, marketing attention and management time should be concentrated on growth opportunities or on protecting dependable earnings.
- Portfolio logic. Compare product areas by market momentum and relative competitive position without assuming a quadrant placement.
- Capital discipline. Consider how reinsurance needs, claims volatility and regulatory capital can affect the resources available for expansion.
- Working view. Use the Excel framework to test consistent inputs, then use the Word analysis to record assumptions and interpret priority trade-offs.
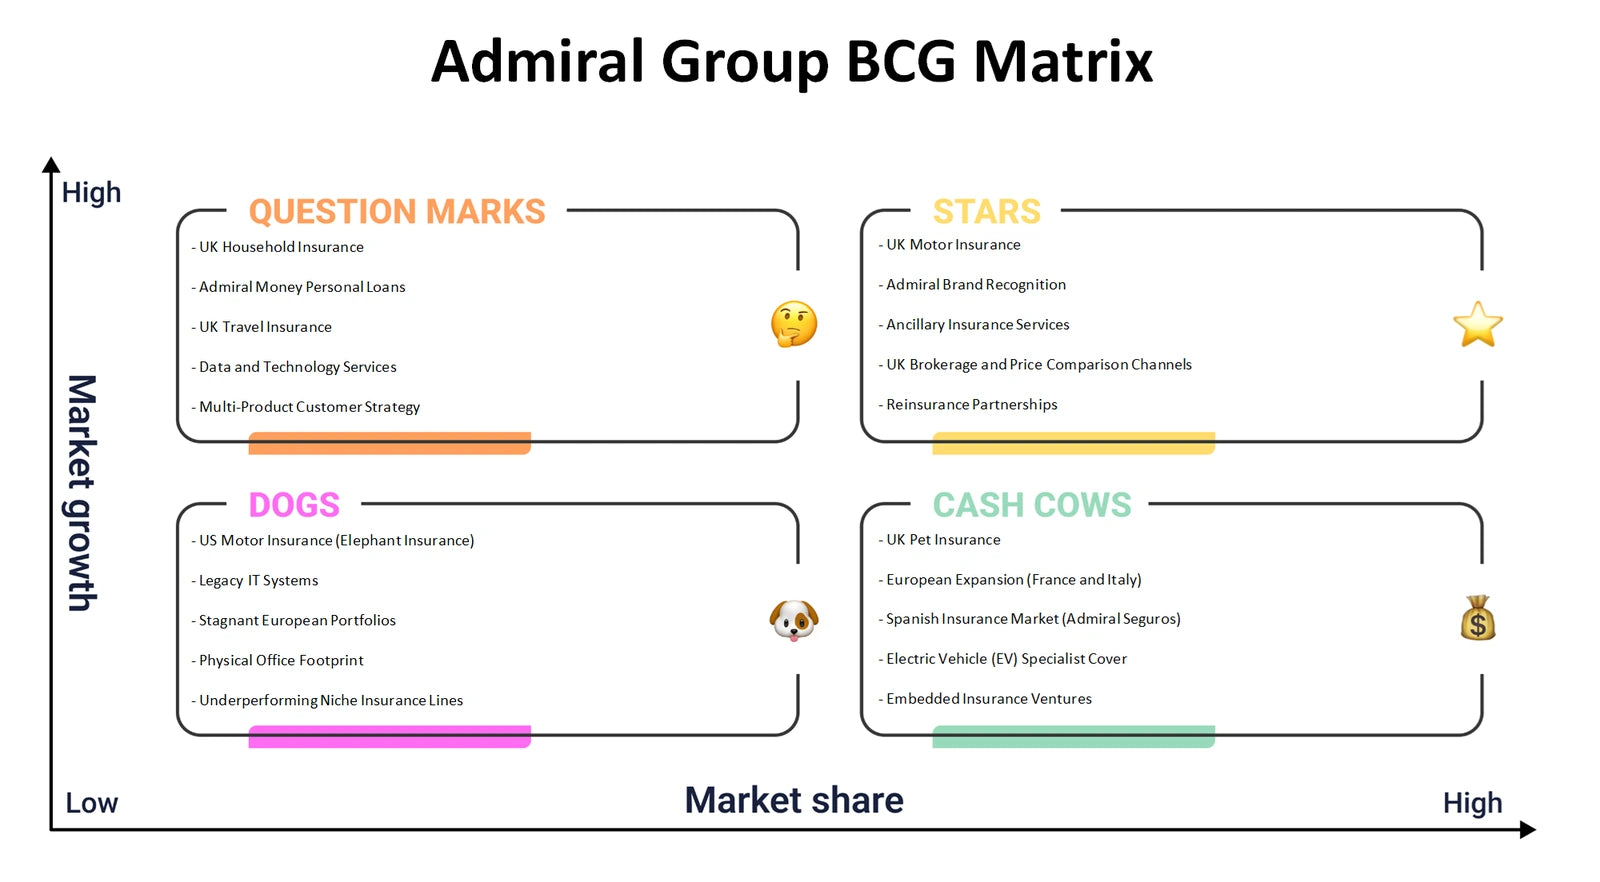
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer trust, risk pricing, service delivery and external partners fit together to create viable insurance economics?
The Admiral Group Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For an insurer, this means tracing how motorists are reached and retained, how insurance cover and service are communicated, and how premium income must support claims, operating costs and risk-transfer arrangements. Reinsurers, banks and payment providers are relevant partnership questions because they can influence capital flexibility, collection reliability and customer checkout. The framework helps distinguish documented operating context from hypotheses that need evidence.
- Value chain. Map the link between a motorist’s need for cover, the quotation-to-renewal experience and the insurer’s underwriting and claims responsibilities.
- Economic connections. Examine how revenue streams, claims exposure, distribution costs and partner dependencies interact rather than treating each in isolation.
- Model mapping. Populate the Excel canvas systematically and use the Word analysis to explain cross-block dependencies, uncertainties and evidence needs.
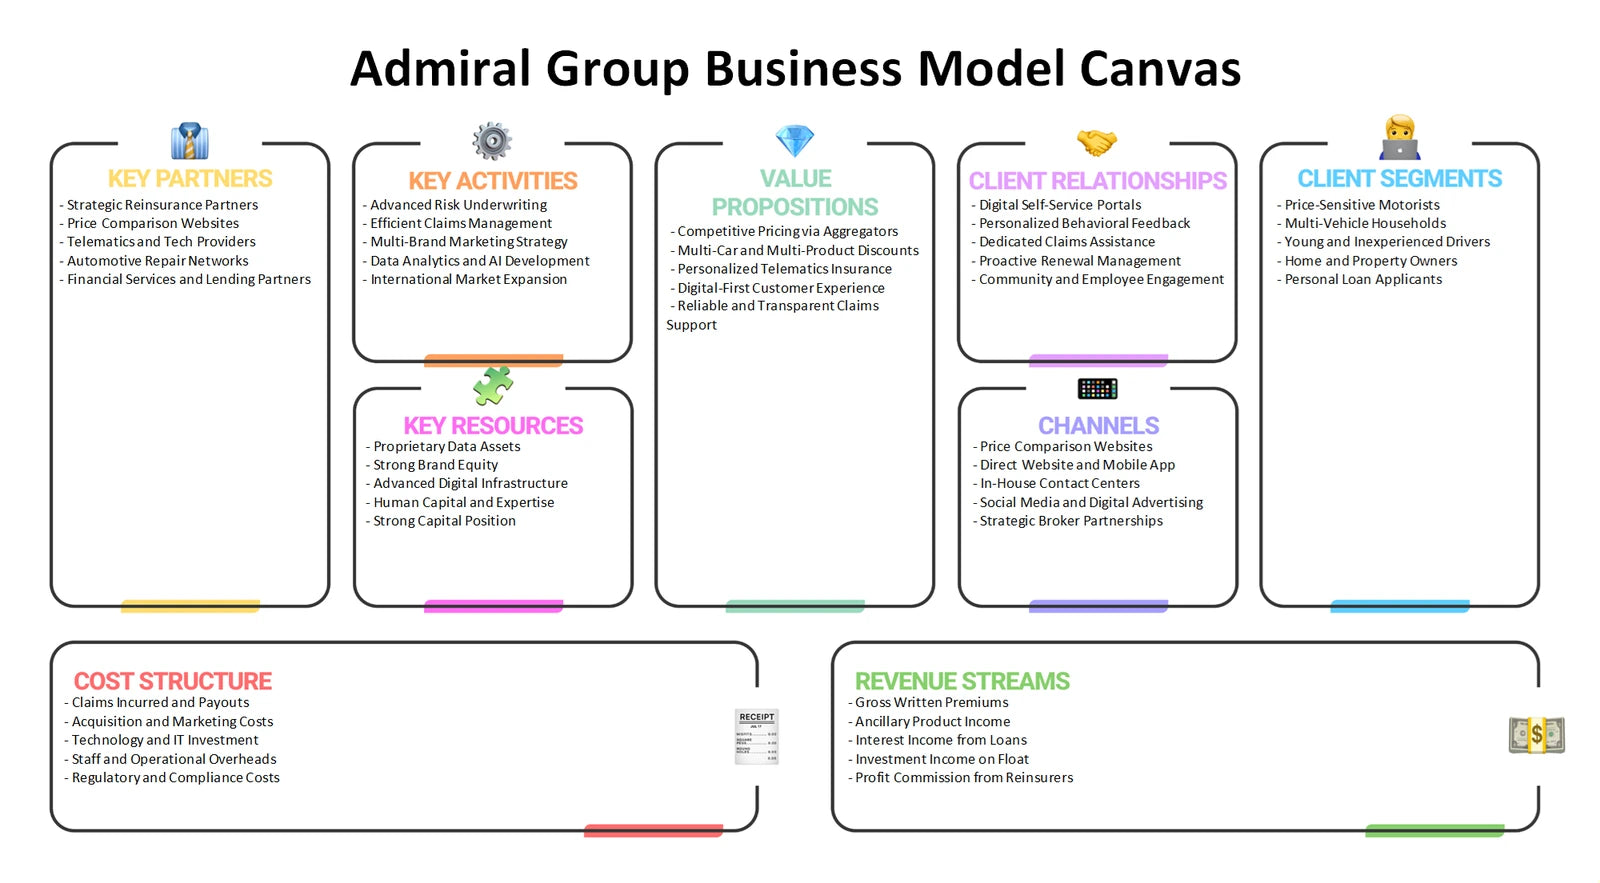
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can influence pricing latitude, customer retention and the long-term attractiveness of motor insurance?
Admiral Group Porter's Five Forces examines the insurance market structure around the business rather than attempting to rank individual competitors. Rivalry can make customer acquisition and renewal pricing difficult, while buyer power matters where consumers can compare cover, excesses and service propositions with limited switching friction. Supplier power includes the influence of repair networks, technology providers, capital markets and reinsurers on cost and capacity. New entrants may be enabled by digital distribution or specialist underwriting platforms. Substitutes are broader alternatives for meeting mobility or protection needs, such as reduced private vehicle use or different risk-sharing arrangements, not simply another insurer.
- Competitive intensity. Assess why price comparison, brand trust, claims experience and underwriting discipline can matter simultaneously.
- Dependency exposure. Explore where third-party repair, data, payment or reinsurance relationships could affect service quality or economics.
- Force comparison. Use the Excel structure to document evidence for each force and the Word analysis to explain how pressures may reinforce one another.
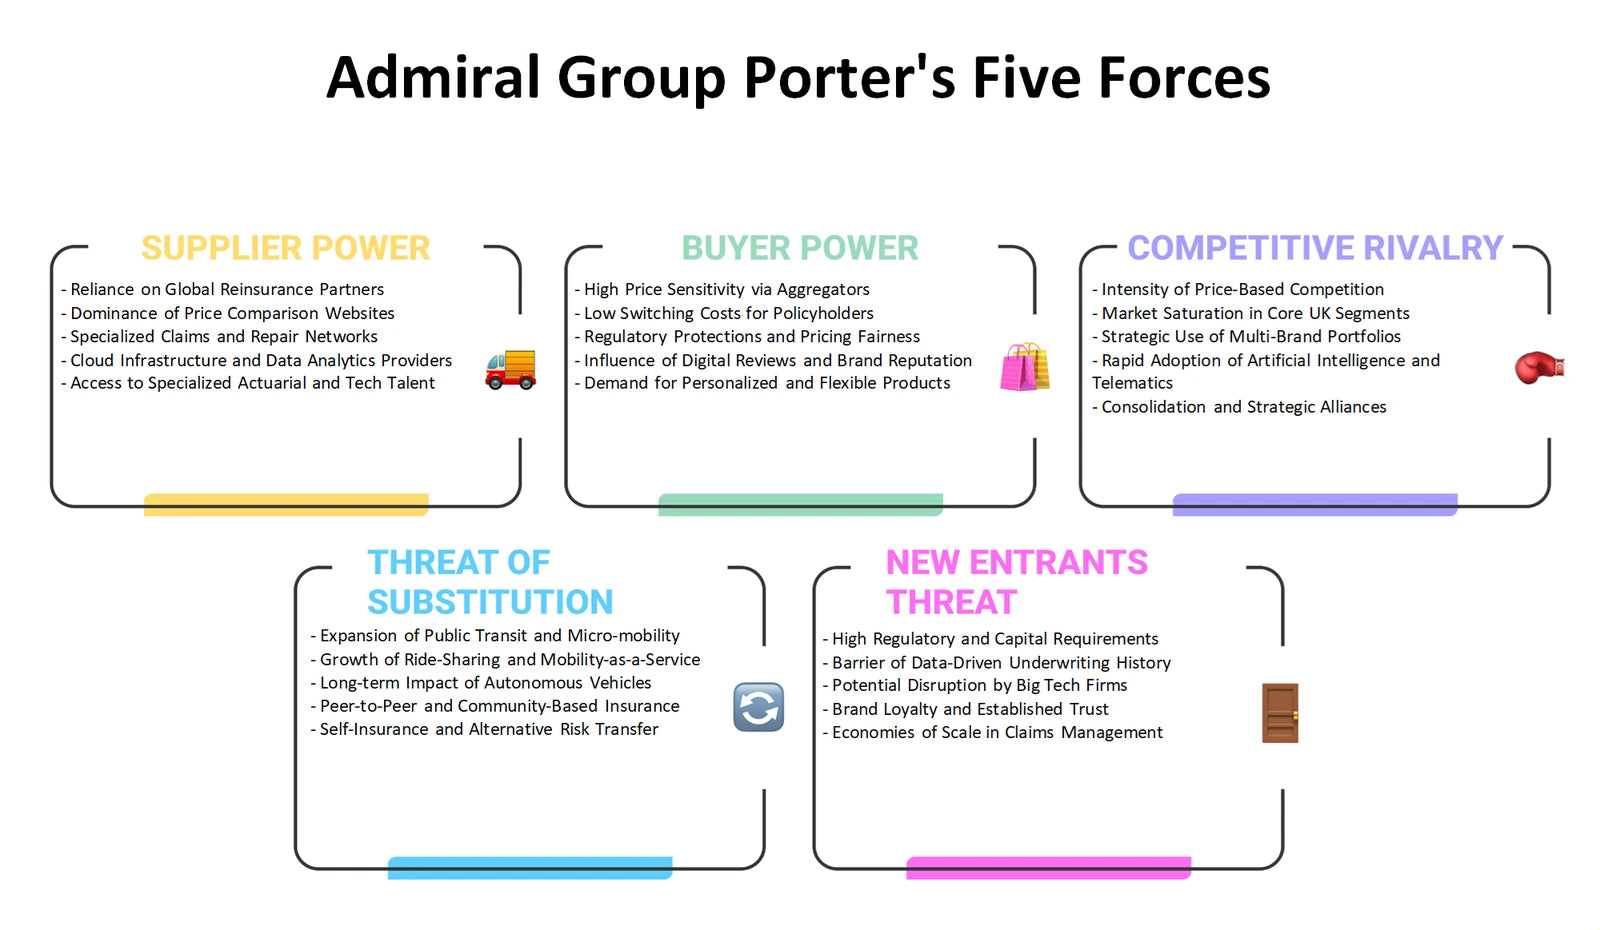
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can an insurance proposition be positioned clearly while balancing customer value, risk selection, distribution and conduct expectations?
The Admiral Group Marketing Mix applies Product, Price, Place and Promotion to a regulated service rather than a physical good. Product analysis considers the scope of motor cover, policy features, claims support and service clarity. Price is not merely a headline premium: it can involve risk-based underwriting, policy terms, payment options and the need for transparent customer communication. Place considers digital journeys, payment rails and other routes through which customers research, buy and manage policies. Promotion explores how messages can communicate reassurance and value without overstating cover or obscuring conditions.
- Product clarity. Review how policy design and customer service may communicate protection at moments of purchase, renewal and claim.
- Responsible pricing. Consider the tension between competitive premiums, risk adequacy, affordability and understandable terms.
- Campaign planning. Use the Excel framework to organise the four Ps, then use the Word analysis to turn observations into a reasoned customer and channel review.
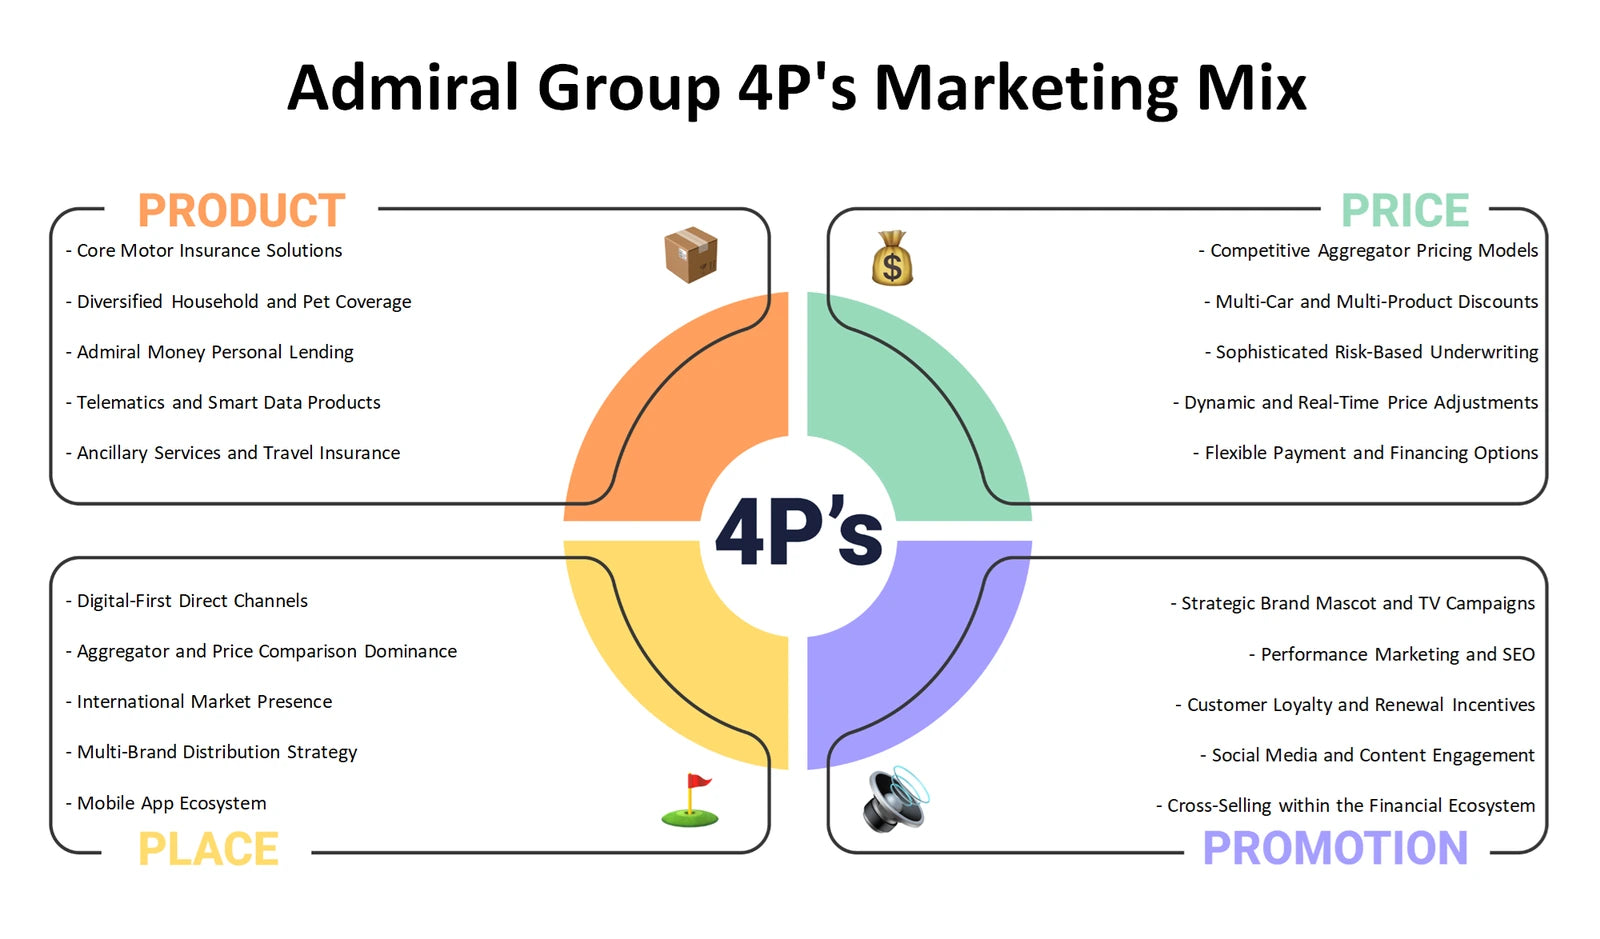
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should an insurer monitor when planning for risk, regulation, technology and changing mobility needs?
An Admiral Group PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental categories. Political and legal questions can include the direction of insurance supervision, consumer-protection expectations and solvency oversight; the supplied context identifies engagement with FCA and PRA requirements as relevant operating context. Economic conditions may affect household budgets, repair costs and financing behaviour. Social changes can alter driving patterns and service expectations. Technology can reshape pricing, fraud prevention, claims handling and digital service. Environmental conditions may change weather-related loss exposure and vehicle-repair requirements.
- External scan. Distinguish documented background conditions from policy, economic or environmental questions that require monitoring.
- Connected risks. Consider how a regulatory change, repair-cost pressure or severe-loss event could affect both customers and insurer operations.
- Scenario register. Organise external signals in the Excel framework and use the Word analysis to add implications, dependencies and questions for follow-up.
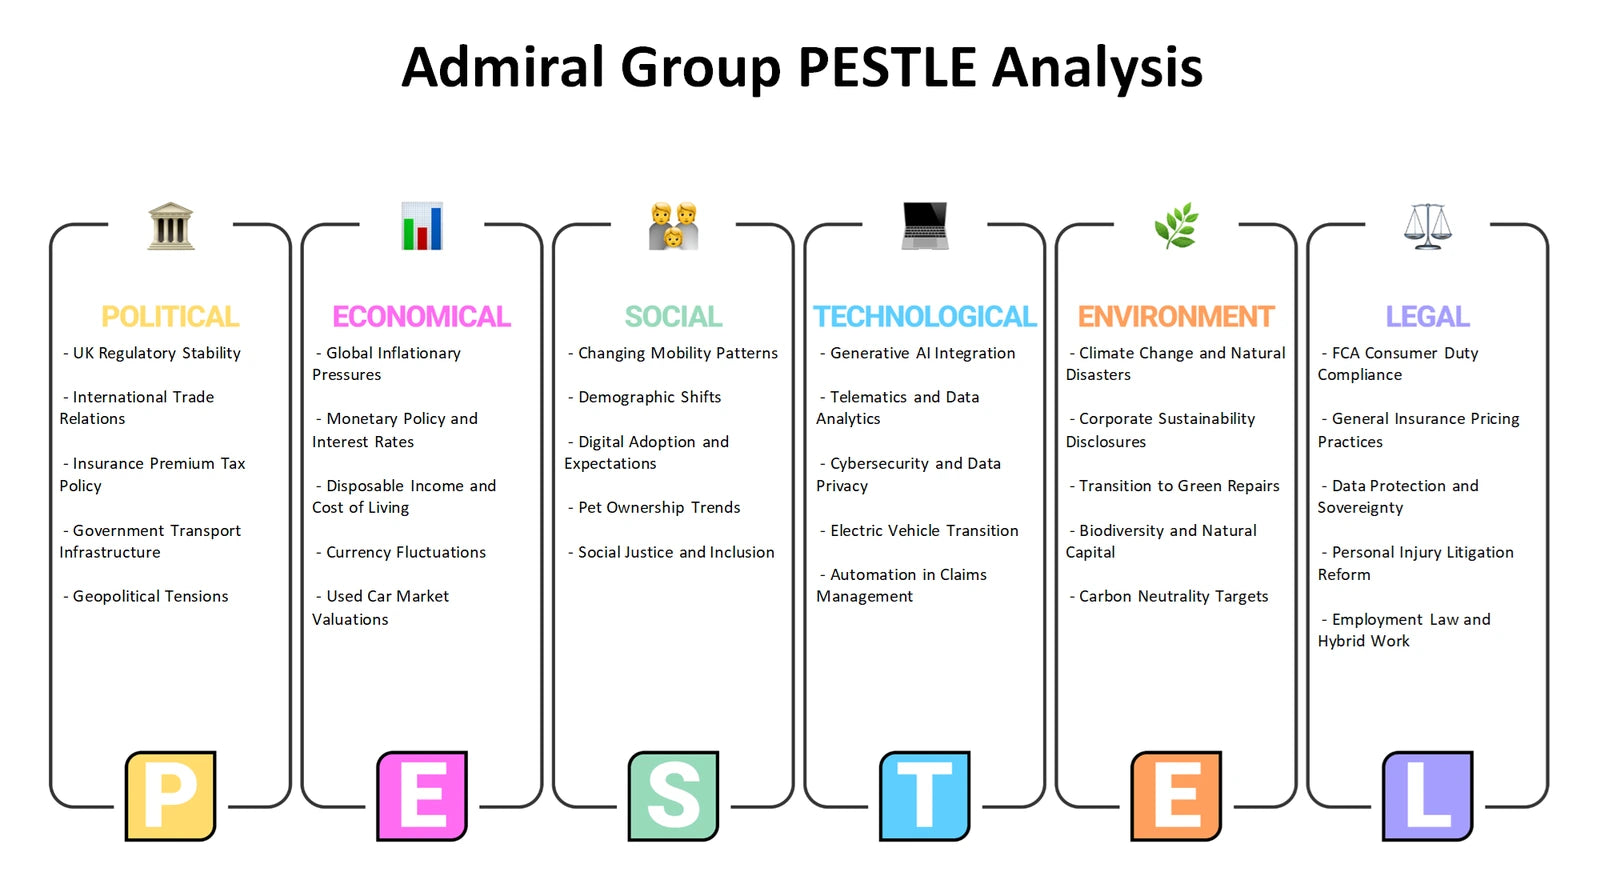
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal insurance capabilities and constraints be considered alongside opportunities and threats outside the business?
An Admiral Group SWOT analysis keeps internal and external factors properly separated. Potential strengths and weaknesses concern capabilities under the organisation’s influence, such as underwriting processes, customer service design, data use, partner management or operational complexity; they should be tested against evidence rather than assumed. Opportunities and threats arise outside the business, including shifts in mobility, technology, regulation, claims inflation, catastrophe exposure and competitive behaviour. The value of SWOT is not a long list. It is the comparison between a plausible internal capability or constraint and an external condition that could make it more important.
- Clear classification. Separate controllable internal capabilities from external market conditions so strategic discussion does not blur cause and response.
- Strategic fit. Explore where a capability may support an opportunity, or where a weakness could amplify an outside threat.
- Priority synthesis. Use the Excel matrix to capture and compare themes, with the Word analysis providing context for which combinations deserve further investigation.
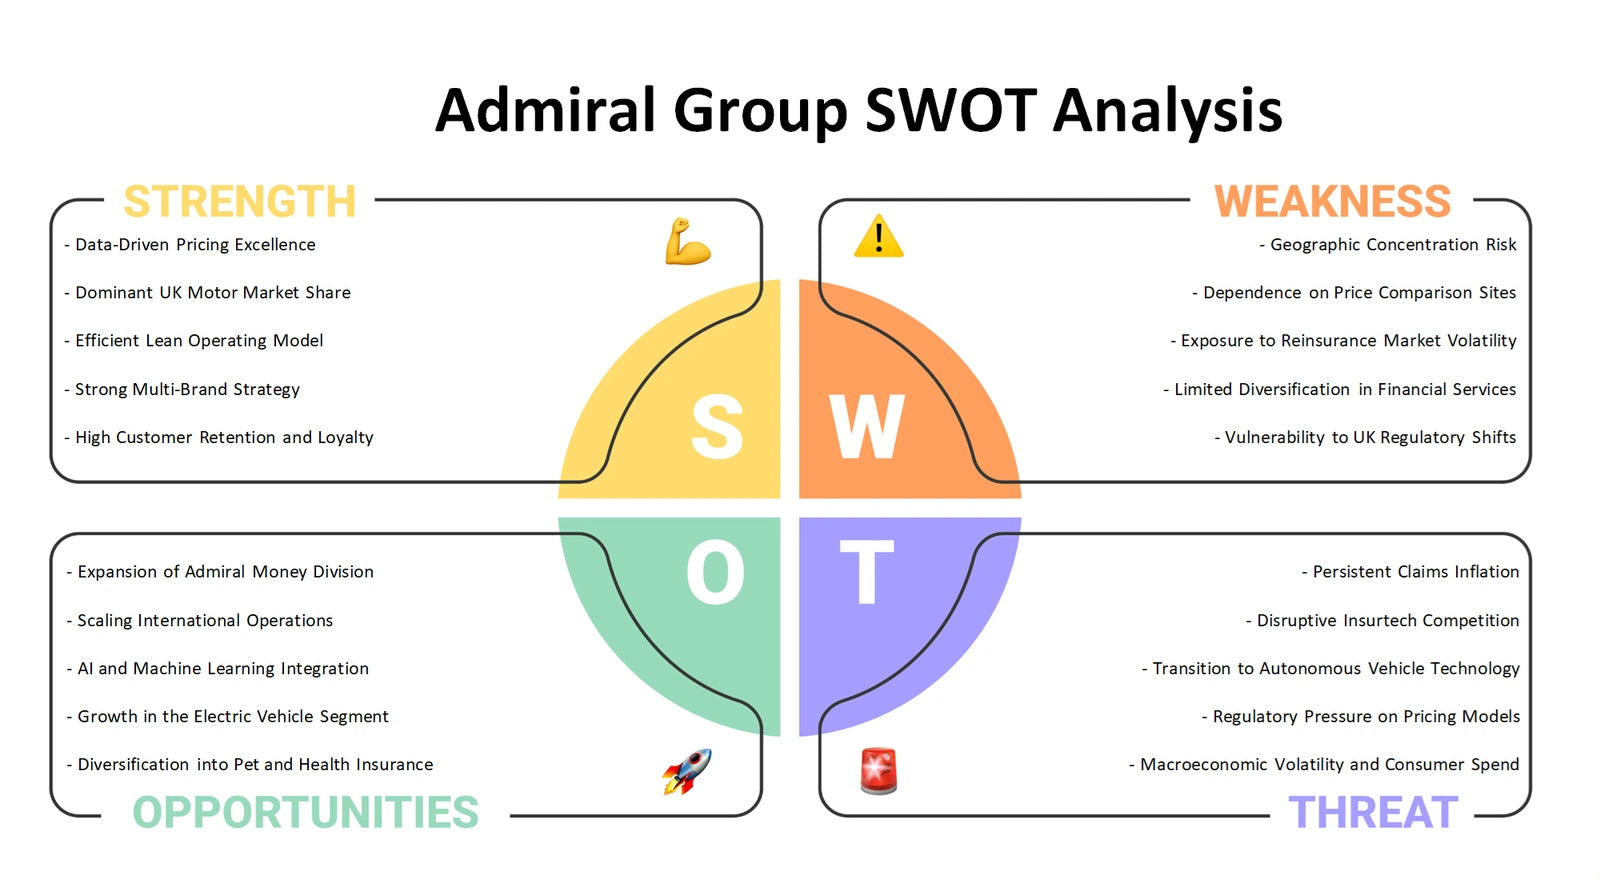
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected strategic view of insurance decisions
Together, the six perspectives move from portfolio allocation and business-model logic to market pressure, customer-facing choices, external change and strategic fit. The Excel frameworks provide a structured way to compare inputs and questions, while the detailed Word materials help develop the reasoning behind them. Used together, they support a more organised discussion of Admiral Group’s motor-insurance context without treating analytical possibilities as established company findings.
Company background: Admiral Group — product-context page.